
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Animal Health Software Market Size 2024 | USD 6890 million |
| Animal Health Software Market, CAGR | 20.8% |
| Animal Health Software Market Size 2032 | USD 31243.1 million |
Market Overview:
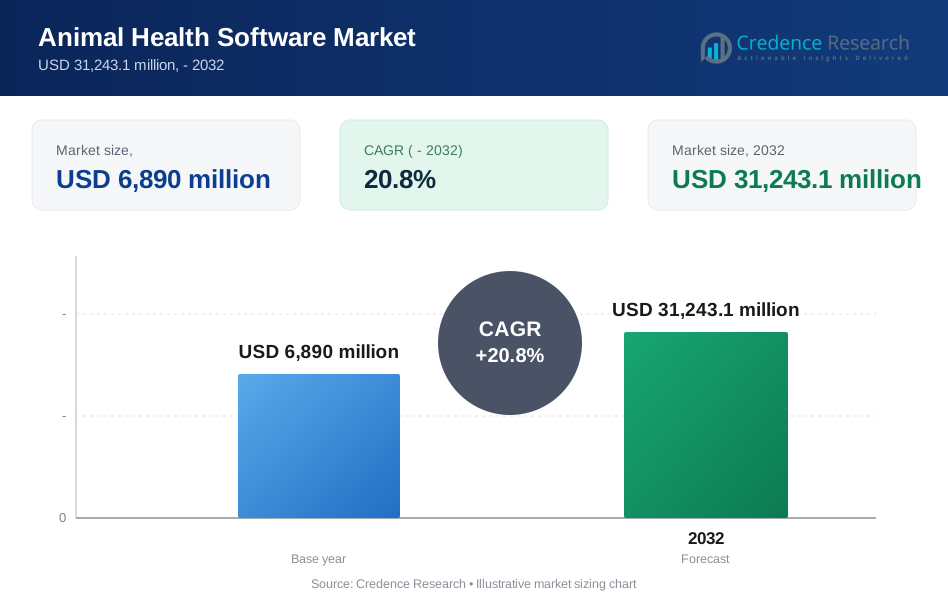
Animal Health Software Market size was valued at USD 6890 million in 2024 and is anticipated to reach USD 31243.1 million by 2032, at a CAGR of 20.8% during the forecast period (2024-2032).
Several factors are driving this market’s rapid development. The surge in pet ownership worldwide and the corresponding rise in expenditure on animal healthcare are key contributors. Technological advancements, including the adoption of artificial intelligence, cloud-based platforms, and telehealth services, are transforming veterinary workflows and enhancing the quality of care. Additionally, the growing emphasis on preventive healthcare, regulatory compliance, and the need for efficient data management in veterinary practices further support the adoption of animal health software. These solutions enable clinics and hospitals to streamline operations, improve patient outcomes, and make data-driven decisions. As a result, veterinary practices are increasingly investing in integrated software platforms to remain competitive and meet evolving client expectations.
Regionally, North America leads the Animal Health Software market, supported by high pet ownership rates, advanced veterinary infrastructure, and the presence of major industry players. The Asia Pacific region is expected to exhibit the fastest growth, fueled by increasing pet adoption, rising disposable incomes, and expanding veterinary healthcare facilities, particularly in countries such as China and India. Europe maintains a significant market share due to the prevalence of pet insurance, a strong focus on preventive care, and stringent data protection regulations. Meanwhile, Latin America and the Middle East & Africa represent emerging markets, with growth driven by rising awareness of animal welfare and supportive government initiatives aimed at improving animal health. Notably, regional collaborations and investments in veterinary education are further accelerating market development across these geographies.
Market Insights:
- The Animal Health Software Market reached USD 6,890 million in 2024 and is projected to hit USD 31,243.1 million by 2032, with a CAGR of 20.8% from 2024 to 2032.
- Rising global pet ownership and increased spending on animal healthcare are major growth drivers, pushing clinics to adopt advanced digital solutions.
- Rapid technological advancements, including artificial intelligence, cloud-based platforms, and telehealth, are transforming veterinary workflows and improving care quality.
- A strong emphasis on preventive healthcare, regulatory compliance, and efficient data management is accelerating software adoption in veterinary practices.
- High implementation costs and limited technical expertise remain significant barriers, especially for smaller clinics and practices.
- North America leads the market with 45% share, followed by Asia Pacific at 25% and Europe at 20%, each region driven by unique infrastructure, policy, and consumer trends.
- Data security concerns, integration challenges, and the need for robust compliance solutions are key issues that vendors must address to support broader market adoption.
Market Drivers:
Rising Pet Ownership and Increased Animal Healthcare Spending Fuel Market Demand
The surge in global pet ownership significantly boosts demand for advanced veterinary services and solutions. Households are allocating more resources toward animal healthcare, driving clinics and hospitals to adopt digital tools that streamline operations. The Animal Health Software Market benefits directly from this trend, as pet owners expect higher standards of care and efficient service delivery. Clinics are under pressure to provide timely diagnostics, treatment, and follow-up care. The need for comprehensive record-keeping and communication tools grows with the rising number of pets. These factors compel veterinary practices to invest in software solutions that enhance both care quality and client satisfaction.
Technological Advancements Accelerate Adoption of Innovative Solutions
Rapid progress in technology transforms the landscape of veterinary medicine. Artificial intelligence, machine learning, and cloud-based platforms introduce new possibilities for diagnostics, treatment planning, and remote monitoring. The Animal Health Software Market leverages these innovations to offer integrated solutions that improve accuracy and operational efficiency. Telehealth services extend access to veterinary care, particularly in underserved regions. Software platforms now support seamless data sharing and interoperability, which strengthens collaboration among veterinary professionals. These advancements create a strong incentive for clinics to upgrade existing systems and adopt cutting-edge software.
- For instance, Covetrus Pulse™, launched in 2022, is a cloud-based veterinary operating system that unites prescription management, client communication, and third-party app integration into a single platform, enabling veterinarians to streamline practice management and spend more time on patient care.
Regulatory Compliance and Data Security Requirements Drive Software Implementation
Stricter regulations in animal healthcare necessitate robust data management and compliance solutions. Veterinary practices must adhere to standards for patient privacy, record-keeping, and reporting. The Animal Health Software Market addresses these requirements by providing secure, compliant platforms that protect sensitive information. Data security features reduce the risk of breaches and ensure regulatory adherence. Clinics value software that simplifies compliance tasks and generates accurate reports for authorities. These demands make regulatory alignment a key driver for software adoption in the sector.
- For instance, Provet Cloud is among the first in the veterinary industry to implement passwordless authentication and holds ISO/IEC 27001:2022 certification, directly supporting over 5,000 veterinary clinics worldwide with advanced compliance and data security features.
Emphasis on Preventive Care and Operational Efficiency Spurs Market Growth
Veterinary professionals increasingly focus on preventive care to improve animal health outcomes and reduce long-term costs. The Animal Health Software Market supports this shift by offering tools for proactive health monitoring, vaccination scheduling, and wellness tracking. Software platforms enable clinics to identify health risks early and engage clients in ongoing care plans. Operational efficiency also remains a priority, with software automating administrative tasks and optimizing resource allocation. Practices that implement these solutions report higher productivity and improved patient outcomes. This dual emphasis on prevention and efficiency continues to shape market growth.
Market Trends:
Integration of Artificial Intelligence and Cloud-Based Solutions Reshapes Veterinary Practice
The integration of artificial intelligence and cloud-based platforms stands out as a defining trend in the Animal Health Software Market. AI-driven tools now support diagnostics, treatment recommendations, and predictive analytics, helping veterinarians make faster, more accurate decisions. Cloud-based solutions enable secure, real-time access to patient data from any location, streamlining collaboration between veterinary teams and specialists. It offers scalable storage and reduces IT maintenance costs for clinics of all sizes. The shift toward digital record-keeping and remote access aligns with the growing demand for flexible, efficient veterinary care. These technologies collectively enhance workflow efficiency and patient outcomes.
- For instance, SignalPET’s SignalRAY is an AI-based radiology test panel that analyzes veterinary X-rays for over 50 common clinical findings, delivering results in under 10 minutes per case, as documented in the company’s technical specifications.
Expansion of Telehealth and Mobile Applications Enhances Client Engagement
Telehealth services and mobile applications are transforming the way veterinary care is delivered and accessed. The Animal Health Software Market reflects this shift, offering platforms that support virtual consultations, remote monitoring, and digital appointment scheduling. It empowers clinics to extend their reach to clients in rural or underserved areas, improving access to care. Mobile apps allow pet owners to manage appointments, access medical records, and receive reminders for preventive care. This trend increases client engagement and satisfaction while reducing administrative burdens for veterinary staff. The widespread adoption of telehealth and mobile solutions signals a new era of convenience and connectivity in animal healthcare.
- For instance, the Vet2Pet app generates an average of 600 appointment requests per year per practice, demonstrating measurable client engagement and operational impact.
Market Challenges Analysis:
High Implementation Costs and Limited Technical Expertise Restrict Market Penetration
High initial costs and ongoing maintenance expenses present significant barriers for many veterinary practices. The Animal Health Software Market faces resistance from smaller clinics that struggle to allocate resources for new technology. It often requires substantial investment in hardware, software licensing, and staff training. Limited technical expertise within veterinary teams further complicates adoption, leading to underutilization of advanced features. Clinics may hesitate to transition from traditional methods due to concerns about workflow disruption. These financial and operational challenges slow the pace of digital transformation in the sector.
Data Security Concerns and Integration Issues Hinder Seamless Adoption
Data security remains a critical concern for veterinary practices adopting digital solutions. The Animal Health Software Market must address risks related to unauthorized access, data breaches, and regulatory compliance. It can be difficult to integrate new software with existing legacy systems, causing compatibility issues and data silos. Practices worry about the reliability and privacy of cloud-based platforms, especially when handling sensitive client and patient information. These concerns create hesitation among decision-makers, limiting widespread adoption. The need for robust security measures and seamless integration remains a top priority for market growth.
Market Opportunities:
Expansion into Emerging Markets and Rural Areas Offers Untapped Growth Potential
Emerging markets and rural regions present significant opportunities for the Animal Health Software Market. Growing pet ownership and rising awareness of animal welfare in these areas drive demand for modern veterinary solutions. It can address the unique needs of underserved communities by offering scalable, cloud-based platforms that require minimal infrastructure. Government initiatives to improve veterinary care and livestock management further support software adoption. Companies that tailor products for local languages and regulatory requirements will gain a competitive edge. Expanding into these regions unlocks new revenue streams and broadens the market’s global footprint.
Development of Advanced Analytics and Personalized Care Solutions Drives Value
Advanced analytics and personalized care modules represent a promising avenue for the Animal Health Software Market. Clinics seek tools that provide actionable insights from patient data, enabling more precise diagnostics and tailored treatment plans. It can leverage artificial intelligence to predict health risks and automate routine tasks, enhancing both efficiency and patient outcomes. Integration with wearable devices and remote monitoring solutions expands the scope of preventive care. Demand for data-driven decision-making continues to rise among veterinary professionals. Developing innovative features that support personalized medicine will position vendors for long-term success.
Market Segmentation Analysis:
By Product Type:
The Animal Health Software Market segments by product type into practice management software, imaging software, and other specialized solutions. Practice management software holds the largest share, driven by its ability to streamline scheduling, billing, and patient records. Imaging software shows strong growth due to rising demand for advanced diagnostic capabilities and integration with digital health records. Specialized modules for inventory, pharmacy, and telemedicine are gaining traction as clinics seek comprehensive, all-in-one platforms.
By Deployment Mode:
Deployment mode divides the market into cloud-based and on-premises solutions. Cloud-based software leads the segment, favored for its flexibility, scalability, and remote accessibility. It reduces IT overhead and supports real-time data sharing across multiple locations. On-premises solutions retain a presence among larger institutions with strict data control requirements, but their share continues to decline as the benefits of cloud adoption become more apparent.
- For instance, Covetrus Pulse users have reported saving 50 hours per month in productivity gains through workflow automation and integration.
By Practice Type:
By practice type, the market includes small animal, mixed animal, and equine practices. Small animal practices represent the largest segment, reflecting the high volume of companion animal visits and growing pet ownership. Mixed animal and equine practices adopt software at a steady pace, driven by the need to manage diverse patient populations and complex workflows. It enables practices of all types to improve operational efficiency and deliver higher standards of care through tailored, integrated solutions.
- For instance, IDEXX Neo allows practices to complete daily operational tasks 5x faster compared to traditional systems, significantly enhancing efficiency for small animal clinics.
Segmentations:
- By Product Type:
- Veterinary Practice Management Software
- Veterinary Imaging Software
- Diagnostic Software
- Disease Tracking and Surveillance Software
- Treatment Planning Software
- Other Software
- By Deployment Mode:
- Cloud-Based
- On-Premises
- Hybrid
- By Practice Type:
- Exclusive Small Animal Practices
- Mixed Animal Practices
- Exclusive Large Animal Practices
- Exclusive Equine Practices
- Predominantly Small Animal Practices
- Predominantly Large Animal Practices
- By End-User:
- Veterinary Clinics and Hospitals
- Research Institutions
- Pharmaceutical Companies
- Livestock Farmers
- Pet Owners
- Others
- By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
- North America
Regional Analysis:
North America: Market Leader with Strong Adoption and Infrastructure
North America holds 45% of the Animal Health Software Market, maintaining its position as the regional leader. The region benefits from advanced veterinary infrastructure, high pet ownership rates, and the presence of major industry players. It sees rapid adoption of digital solutions, supported by favorable reimbursement policies and a strong focus on preventive healthcare. Regulatory standards for data privacy and patient care further accelerate software integration across the United States and Canada. Clinics consistently seek innovative tools to improve operational efficiency and client engagement. North America’s mature market environment continues to set the benchmark for technology adoption in animal health.
Asia Pacific: Fastest Growing Region with Expanding Veterinary Services
Asia Pacific holds 25% of the Animal Health Software Market and demonstrates the fastest growth rate globally. Rising disposable incomes and increasing pet adoption drive demand for advanced veterinary solutions in countries such as China, India, and Australia. It benefits from government initiatives to improve animal welfare and livestock management, creating new opportunities for software vendors. Both local and global companies invest in tailored products that address regional needs and regulatory requirements. The region’s large population and evolving consumer preferences fuel market expansion. Asia Pacific is quickly closing the gap with established markets through rapid technological advancement.
Europe: Significant Share Driven by Preventive Care and Data Security
Europe represents 20% of the Animal Health Software Market, supported by a strong emphasis on preventive care and widespread pet insurance coverage. The region enforces stringent data protection regulations, prompting clinics to adopt secure and compliant software platforms. It benefits from a well-developed veterinary network and growing awareness of animal health management. Countries such as Germany, the United Kingdom, and France lead in technology adoption and innovation. The market’s focus on data-driven care and operational excellence aligns with broader healthcare trends. Europe continues to offer stable growth prospects for vendors targeting advanced veterinary practices.
Key Player Analysis:
- Virbac
- Zoetis
- Elanco
- Mars Inc.
- Ceva Santé Animale
- Vetoquinol S.A.
- Dechra Pharmaceuticals Plc
- Merck & Co., Inc.
- Idexx Laboratories, Inc.
- Boehringer Ingelheim Gmbh
Competitive Analysis:
The Animal Health Software Market features strong competition among established players and emerging entrants. Key companies focus on product innovation, integrating advanced analytics and cloud-based solutions to enhance veterinary practice management. It sees frequent partnerships and acquisitions, with firms aiming to expand their geographic reach and service portfolios. Companies invest in research and development to address evolving regulatory requirements and user demands. Price competitiveness and customer support remain critical differentiators. The market’s landscape reflects rapid technological adoption, driving continuous upgrades and new feature rollouts. It attracts interest from both specialized veterinary solution providers and larger healthcare IT firms, intensifying rivalry.
Recent Developments:
- In June 2025, Zoetis launched "AI Masses," an AI-powered cytologic capability for the Vetscan Imagyst analyzer, enabling rapid in-clinic screening of lymph node and skin/subcutaneous lesions.
- In June 2025, Zoetis announced a strategic collaboration with Infosys to enhance IT operations and digital capabilities using advanced AI and automation.
- In April 2025, Virbac launched Zenidog and Zenifel, a range of electric-free pheromone products for stress management in pets.
Market Concentration & Characteristics:
The Animal Health Software Market exhibits moderate concentration, with a few key players holding significant market shares while numerous smaller firms contribute to competitive diversity. It features a blend of established companies and innovative startups, driving technological advancements and specialized solutions. The market emphasizes scalability, user-friendly interfaces, and integration capabilities with existing veterinary systems. Customer demand for comprehensive data management and real-time monitoring shapes product development. Geographic expansion and customization for regional regulatory compliance influence market dynamics. It maintains steady growth due to increasing adoption of digital tools in veterinary care and livestock management. This combination of concentrated leadership and diverse participants fosters a dynamic environment focused on innovation and customer-centric offerings.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Deployment Mode, Practice Type, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Animal Health Software Market will see rapid adoption of cloud-based and mobile solutions, enhancing accessibility and real-time data management.
- Artificial intelligence and machine learning will drive advancements in diagnostics, treatment planning, and disease surveillance, enabling more accurate interventions.
- Integration of telemedicine features will expand remote consultation and monitoring capabilities, supporting broader access to veterinary care.
- Demand for interoperable platforms will rise, with veterinary practices seeking seamless data exchange between clinics, laboratories, and pharmacies.
- The market will focus on customizable and user-friendly interfaces to address the specific needs of diverse veterinary practices and animal types.
- Preventive care and wellness tracking will become central, with software offering vaccination reminders, health monitoring, and proactive care plans.
- Data security and privacy will remain a top priority, prompting providers to implement robust encryption and compliance measures.
- Emerging markets, particularly in Asia Pacific, will experience significant growth due to rising pet ownership and disposable incomes.
- Strategic partnerships and acquisitions will accelerate, enabling companies to expand portfolios and enter new geographic regions.
- The market will continue to evolve with subscription-based and SaaS models, providing scalable, cost-effective solutions for veterinary professionals.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Animal Health Software Market?
What are the key segments within the Animal Health Software Market?
What are some challenges faced by the Animal Health Software Market?
Who are the major players in the Animal Health Software Market
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Animal Health Software Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Animal Health Software Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 6,890 million → 2032: USD 31,243.1 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Animal Health Software Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Animal Health Software Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Animal Health Software Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Animal Health Software Market Drivers
- 3.3 Animal Health Software Market Restraints & Challenges
- 3.4 Animal Health Software Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Animal Health Software Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Animal Health Software Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Animal Health Software category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Animal Health Software Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Animal Health Software Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Animal Health Software market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Animal Health Software Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Animal Health Software Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Animal Health Software Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Animal Health Software (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Animal Health Software Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Animal Health Software Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Animal Health Software Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Animal Health Software Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Animal Health Software Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Animal Health Software Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Animal Health Software Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Animal Health Software Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Animal Health Software Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
