
Microwave Oven Market Overview:
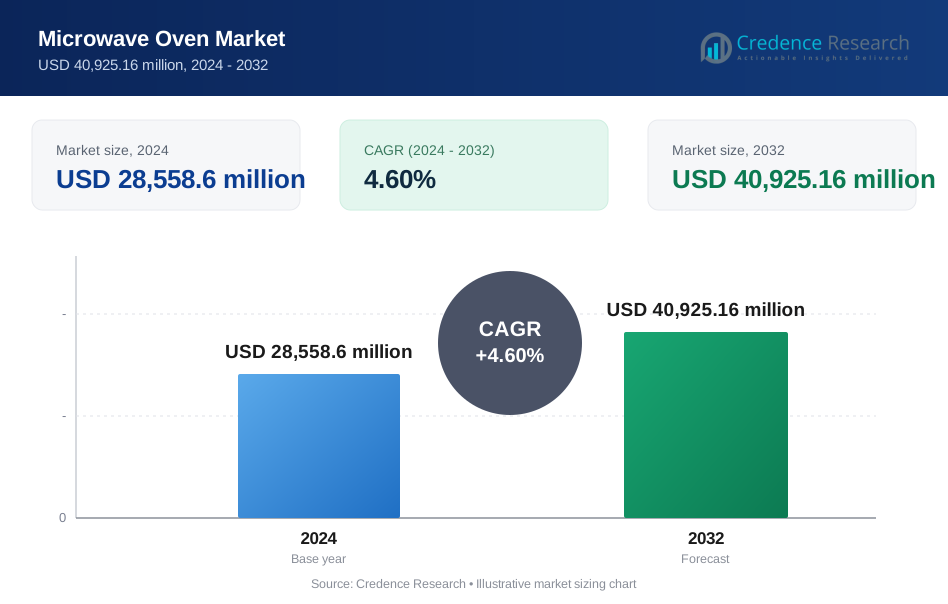
The global microwave oven market was valued at USD 28,558.6 million in 2024 and is projected to reach USD 40,925.16 million by 2032, expanding at a CAGR of 4.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Microwave Oven Market Size 2024 | USD 28,558.6 million |
| Microwave Oven Market, CAGR | 4.6% |
| Microwave Oven Market Size 2032 | USD 40,925.16 million |
Microwave Oven Market Insights
- Market growth is primarily driven by rising urbanization, increasing dual-income households, and growing dependence on convenient cooking solutions, with convection microwave ovens emerging as the dominant product segment due to their multifunctional capabilities.
- Key market trends include premiumization, growing adoption of built-in structures, and rising preference for digital control microwave ovens, which collectively account for a majority share as consumers seek smart, integrated, and aesthetically aligned kitchen appliances.
- The competitive landscape is marked by strong global manufacturers and regional players competing through innovation, pricing strategies, and distribution scale, while intense competition in solo and entry-level segments continues to pressure margins.
- Regionally, Asia Pacific leads with approximately 36% market share, followed by North America at 28% and Europe at 24%, supported by high household penetration, replacement demand, and expanding urban housing markets.

Microwave Oven Market Segmentation Analysis:
By Product:
By product, convection microwave ovens represent the dominant sub-segment, accounting for the largest market share due to their multifunctionality and suitability for modern cooking needs. Convection models combine microwave heating with grilling and baking capabilities, allowing users to prepare a wide range of dishes using a single appliance. Their dominance is driven by rising demand for all-in-one kitchen solutions, growing interest in home baking, and increasing adoption among urban households with limited kitchen space. Grill microwave ovens follow, supported by demand for browning and roasting features, while solo models remain popular in cost-sensitive markets for basic reheating and defrosting applications.
- For instance, BSH Home Appliances Group equips its Bosch Series 8 ovens and convection microwaves with 4D Hotair technology, which achieves uniform heat distribution using a specialized fan wheel that periodically alternates its direction of rotation. This ensures consistent cooking results across up to four shelf levels simultaneously.
By Structure:
By structure, built-in microwave ovens hold the dominant market share, supported by increasing demand for modular kitchens and premium home renovation projects. Built-in models offer seamless integration with cabinetry, improved aesthetics, and optimized space utilization, making them highly attractive in urban apartments and high-income households. Growth is further driven by real estate developments emphasizing modern kitchen layouts and rising consumer preference for integrated appliance ecosystems. Cooktop microwave ovens continue to witness steady demand, particularly in emerging markets and rental housing, due to their lower upfront cost, portability, and ease of installation without structural modifications.
- For instance, Miele’s built-in microwave series integrates touch-controlled interfaces and stainless-steel cavities engineered for 1,000 W microwave output with precise electronic power modulation to ensure consistent heating in enclosed cabinetry environments.
By Control Feature:
By control feature, digital microwave ovens dominate the segment, accounting for the majority market share as consumers increasingly prefer precision, convenience, and smart functionality. Digital controls enable preset cooking programs, sensor-based heating, and touch-panel interfaces that enhance usability and cooking accuracy. The shift toward connected and feature-rich appliances further supports digital adoption across both residential and commercial users. Analog microwave ovens maintain a presence in entry-level and price-sensitive segments, where simplicity, durability, and ease of operation remain key purchase drivers, particularly in developing regions and small foodservice establishments.
Key Growth Drivers
Rising Urbanization and Changing Lifestyles
Rapid urbanization and evolving consumer lifestyles continue to be a primary growth driver for the microwave oven market. Increasing numbers of dual-income households and longer working hours have intensified demand for time-efficient cooking solutions. Microwave ovens address this need by enabling quick meal preparation, reheating, and defrosting with minimal effort. The growing reliance on ready-to-eat and frozen foods further supports adoption, as these products are designed for microwave compatibility. Urban households, particularly in apartments with limited kitchen space, increasingly favor compact and multifunctional appliances. As a result, microwave ovens have transitioned from optional appliances to essential kitchen equipment, sustaining consistent demand across residential and light commercial segments.
- For instance, Panasonic Corporation equips its inverter microwave ovens with continuous power control supporting 1,000 W output, allowing uniform heating without intermittent power cycling, which reduces cooking time for ready-to-eat meals.
Technological Advancements and Product Innovation
Continuous technological innovation is significantly enhancing the appeal of microwave ovens. Manufacturers are integrating advanced features such as inverter technology for precise power control, sensor-based cooking for optimized heating, and smart connectivity for remote operation and recipe guidance. These innovations improve cooking consistency, reduce energy consumption, and enhance overall user experience. Touchscreen digital panels, preset menus, and safety enhancements such as child-lock systems further increase product adoption. Innovation also enables premium pricing strategies, particularly in convection and built-in models, encouraging consumers to upgrade from basic units. This steady flow of product advancements remains a strong catalyst for market expansion.
- For instance, LG Electronics’ Smart Inverter models integrate humidity and temperature sensors that automatically adjust cooking time across up to 28 preset programs, reducing manual intervention.
Expansion of Foodservice and Commercial Applications
The growing foodservice industry is another key driver supporting microwave oven demand. Quick-service restaurants, cafés, cloud kitchens, and institutional foodservice operators increasingly rely on microwave ovens for reheating, defrosting, and rapid food preparation. Their ability to ensure speed, consistency, and hygiene aligns well with commercial operational requirements. Rising urban populations and changing eating habits have accelerated the growth of takeaway and delivery-based food models, further boosting commercial appliance demand. Additionally, compact commercial microwave ovens are gaining traction in offices, hospitals, and educational institutions, broadening the application base and reinforcing sustained market growth.
Key Trends & Opportunities
Growing Demand for Smart and Connected Microwave Ovens
The integration of smart technologies represents a major trend and opportunity within the microwave oven market. Consumers increasingly expect connectivity features that enable remote operation, voice control, and app-based monitoring. Smart microwave ovens offer guided cooking, automatic power adjustments, and compatibility with broader smart home ecosystems. These features enhance convenience and appeal to tech-savvy consumers, particularly in developed markets. As smart kitchens gain popularity, manufacturers have opportunities to differentiate through software-driven functionality, personalized cooking experiences, and seamless integration with other connected appliances.
- For instance, Samsung Electronics equips its SmartThings-enabled microwave ovens with Wi-Fi modules primarily supporting 2.4 GHz connectivity to ensure wider home coverage. While users can remotely monitor cooking status and stop cycles via the SmartThings app, they cannot typically "start" cooking remotely due to safety regulations requiring a physical interaction with the appliance.
Premiumization and Demand for Built-in Models
Premiumization is emerging as a strong market trend, driven by rising disposable incomes and growing interest in aesthetically integrated kitchens. Built-in microwave ovens are gaining popularity due to their sleek design, space optimization, and alignment with modular kitchen concepts. Consumers increasingly view kitchen appliances as lifestyle products rather than purely functional tools. This trend creates opportunities for manufacturers to expand premium product lines, offer customization options, and bundle microwave ovens with other built-in appliances. The shift toward high-end housing developments further supports this opportunity.
- For instance, Brandt (France) offers built-in microwave models engineered for 45 cm installation height with 25-40 L cavity capacities and 900 W microwave output, enabling seamless pairing with Brandt wall ovens in unified kitchen columns.
Energy Efficiency and Sustainable Design Focus
Energy efficiency and sustainability are becoming key purchasing considerations, creating new opportunities for innovation. Consumers are increasingly aware of energy consumption and environmental impact, encouraging demand for microwave ovens with improved power efficiency and eco-friendly materials. Features such as inverter technology, reduced standby power, and recyclable components enhance product appeal. Manufacturers that prioritize sustainable design and compliance with energy standards can strengthen brand positioning and gain competitive advantage, particularly in regions with strict regulatory frameworks.
Key Challenges
Intense Price Competition and Market Saturation
The microwave oven market faces significant challenges from intense price competition, particularly in mature regions. High market penetration has led to slower replacement cycles, forcing manufacturers to compete aggressively on pricing. Entry-level and solo microwave ovens are especially exposed to commoditization, limiting profit margins. The presence of numerous local and regional players further intensifies competition, making brand differentiation difficult. As a result, manufacturers must balance cost efficiency with innovation investments, which can strain profitability and complicate long-term growth strategies.
Consumer Perception and Health-Related Concerns
Persistent consumer concerns regarding the safety and health impact of microwave cooking present another challenge. Misconceptions about radiation exposure and nutrient loss in microwaved food continue to influence purchasing decisions, particularly in developing markets. These concerns can slow adoption among first-time buyers and restrict usage frequency. Additionally, the learning curve associated with advanced features may discourage less tech-oriented consumers. Addressing these challenges requires continuous consumer education, clear communication of safety standards, and simplified user interfaces to build trust and expand market acceptance.
Regional Analysis
North America
North America accounts for approximately 28% of the global microwave oven market, supported by high household penetration, strong replacement demand, and widespread adoption of advanced kitchen appliances. Consumers in the region show a strong preference for convection and built-in microwave ovens equipped with digital controls, smart connectivity, and energy-efficient technologies. The presence of established manufacturers, well-developed retail infrastructure, and high awareness of premium appliance features further supports market maturity. Growth is reinforced by demand from foodservice outlets, offices, and institutional kitchens, while ongoing home renovation activities continue to drive upgrades to modern, integrated microwave solutions.
Europe
Europe represents around 24% of the global microwave oven market, driven by demand for premium, energy-efficient, and built-in appliances aligned with modern kitchen designs. Consumers place strong emphasis on aesthetics, sustainability, and compliance with energy regulations, supporting adoption of inverter-based and low-energy-consumption models. Western Europe leads regional demand due to higher disposable incomes and widespread modular kitchen adoption, while Eastern Europe contributes through steady replacement and first-time purchases. The region’s mature housing market, combined with strong retail and e-commerce channels, sustains consistent demand for digital and convection microwave ovens.
Asia Pacific
Asia Pacific dominates the global microwave oven market with an estimated 36% market share, making it the largest and fastest-growing regional segment. Growth is driven by rapid urbanization, rising middle-class populations, increasing disposable incomes, and expanding nuclear households. Countries such as China, India, and Southeast Asian nations are witnessing strong demand for both solo and convection microwave ovens due to affordability improvements and lifestyle shifts. Expanding residential construction, growing awareness of convenience cooking, and the rapid penetration of organized retail and online platforms continue to fuel market expansion across the region.
Latin America
Latin America holds approximately 7% of the global microwave oven market, supported by gradual urban expansion and improving consumer access to home appliances. Demand is primarily driven by freestanding and cost-effective microwave ovens, particularly in middle-income households. Countries such as Brazil and Mexico lead regional consumption due to larger urban populations and growing retail networks. While premium adoption remains limited, rising exposure to modern cooking appliances and increasing participation of women in the workforce are encouraging microwave usage. The region shows steady growth potential as appliance affordability and distribution continue to improve.
Middle East & Africa
The Middle East & Africa region accounts for about 5% of the global microwave oven market, characterized by moderate but steadily rising demand. Growth is supported by increasing urban development, expanding residential construction, and rising expatriate populations in Gulf countries. Demand is concentrated in urban centers, with preference for durable, easy-to-use microwave ovens suitable for diverse cooking needs. While penetration remains relatively low in parts of Africa, improving retail access and rising consumer awareness are gradually expanding the market. The hospitality and foodservice sectors also contribute to incremental regional demand.
Microwave Oven Market Segmentations:
By Product
- Convection
- Grill
- Solo
By Structure
- Built-in
- Cooktop
By Control Feature
- Digital
- Analog
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The microwave oven market features a competitive landscape characterized by the presence of well-established global appliance manufacturers alongside strong regional players competing on technology, pricing, and distribution reach. Leading companies focus on broad product portfolios spanning solo, grill, and convection models, while increasingly emphasizing built-in and digitally controlled variants to address premium demand. Competitive differentiation is driven by continuous innovation in inverter technology, sensor-based cooking, smart connectivity, and energy efficiency. Companies leverage strong brand equity, extensive retail and e-commerce networks, and after-sales service capabilities to maintain customer loyalty. Strategic initiatives such as product launches, design upgrades, and regional manufacturing expansion help players optimize costs and respond to local preferences. At the same time, intense price competition in entry-level segments encourages operational efficiency and localized sourcing. Overall, sustained innovation, brand strength, and distribution scale remain critical to securing long-term competitive advantage in the microwave oven market.
Key Player Analysis
- Galanz (Guangdong Galanz Enterprises Co. Ltd.) - China
- Miele - Germany
- Midea Group - China
- Electrolux AB - Sweden
- BSH Home Appliances Group - Germany
- Breville - Australia
- Brandt - France
- Alto-Shaam Inc. - USA
- AmazonBasics (Amazon.com) - USA
- Dongbu Daewoo Electronics - South Korea
Recent Developments
- In September 2025, Galanz announced the expansion of its home appliance portfolio in India, including a range of microwave ovens featuring 73 auto-cook menus, 11 power levels, and extended magnetron warranties of 5 years, aimed at boosting brand presence in the Indian market through e-commerce partnerships.
- In February 2025, Midea unveiled its Easy to Install Over-the-Range Microwave at the 2025 Kitchen and Bath Industry Show (KBIS). This model features a “push and snap” installation mechanism for single-person setup, 1,000 W microwave power, a spacious 1.7 cu ft cavity, and a 300 CFM hood ventilation system to remove smoke and odors during cooking reflecting a focus on user-friendly designs for modern kitchens.
Report Coverage
The research report offers an in-depth analysis based on Product, Structure, Control feature and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for microwave ovens will continue to rise as urban households increasingly prioritize convenience and time-efficient cooking solutions.
- Convection microwave ovens will see higher adoption due to their ability to combine baking, grilling, and reheating functions in a single appliance.
- Built-in microwave ovens will gain traction as modular kitchens and integrated appliance layouts become more common in residential construction.
- Digital control microwave ovens will increasingly replace analog models as consumers seek precision, ease of use, and preset cooking programs.
- Smart and connected microwave ovens will expand steadily with growing integration into broader smart home ecosystems.
- Energy-efficient technologies will become a key differentiator as consumers and regulators emphasize reduced power consumption.
- Manufacturers will focus on compact and space-saving designs to address smaller urban living spaces.
- Commercial demand from quick-service restaurants and cloud kitchens will support consistent appliance replacement cycles.
- Product differentiation through design, safety features, and user-friendly interfaces will intensify competitive dynamics.
- Emerging markets will play a critical role in long-term growth through rising appliance penetration and expanding retail access.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the microwave oven market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the microwave oven market projected to grow between 2024 and 2032?
Which microwave oven segment held the largest share in 2024?
What are the primary factors fueling the growth of the microwave oven market?
Who are the leading companies in the microwave oven market?
Which region commanded the largest share of the microwave oven market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 28,558.6 million → 2032: USD 40,925.16 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Microwave Oven Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Microwave Oven Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Microwave Oven Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Microwave Oven Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Microwave Oven Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Microwave Oven Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Microwave Oven Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Microwave Oven Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 28,558.6 million → 2032: USD 40,925.16 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Microwave Oven Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Microwave Oven Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Microwave Oven Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Microwave Oven Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
