
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Anti-Pollution Ingredients Market Size 2024 | USD 929 million |
| Anti-Pollution Ingredients Market, CAGR | 8.6% |
| Anti-Pollution Ingredients Market Size 2032 | USD 1797.43 million |
Market Overview
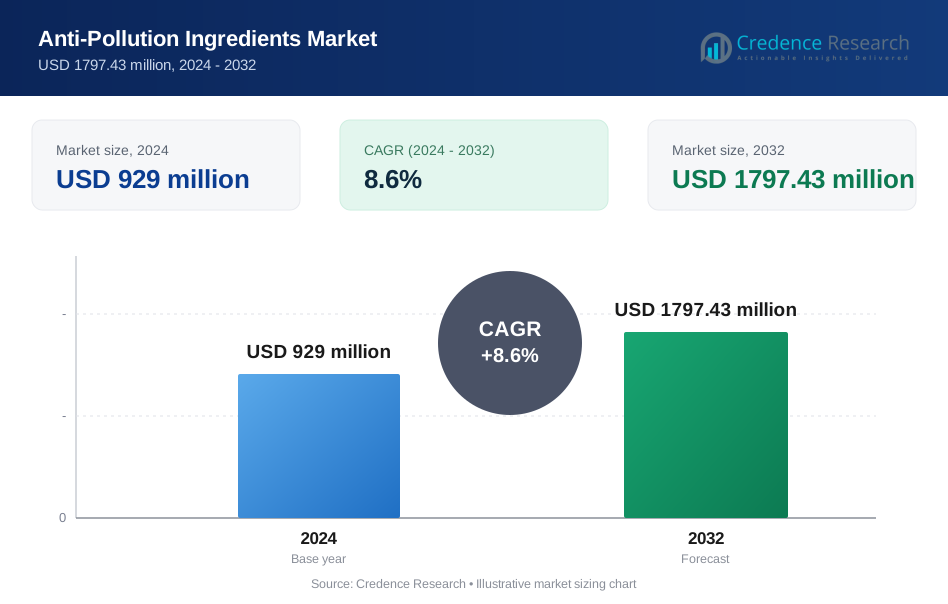
The Anti-Pollution Ingredients Market is projected to grow from USD 929 million in 2024 to an estimated USD 1797.43 million by 2032, with a compound annual growth rate (CAGR) of 8.6% from 2024 to 2032.
Key drivers of the anti-pollution ingredients market include rising consumer awareness about the harmful effects of air and environmental pollution on health and skin, which is driving demand for products that offer protection against pollutants. The growing trend of clean beauty and sustainable product formulations is also pushing the market forward, as consumers demand ingredients that are both effective and environmentally friendly. Moreover, the increasing prevalence of respiratory and skin conditions, such as asthma, allergies, and premature aging, associated with pollution exposure, is contributing to the market's growth. Companies are investing in the development of advanced ingredients, such as antioxidants, anti-inflammatory agents, and UV filters, that help neutralize pollution and protect the skin and body.
Regionally, North America and Europe are leading the anti-pollution ingredients market, driven by high consumer awareness, regulatory frameworks favoring clean products, and a strong market for beauty and skincare products. In Asia Pacific, countries like China and India are experiencing rapid growth due to increasing pollution levels in urban areas, a rising middle class, and growing demand for personal care products. The region is expected to continue witnessing significant market expansion as awareness about pollution-related health risks increases. Latin America and the Middle East & Africa are also witnessing growth in the market, as urbanization and industrialization lead to higher pollution levels, driving the demand for anti-pollution skincare and wellness products.
Market Insights
- The Anti-Pollution Ingredients Market is expected to grow from USD 929 million in 2024 to USD 1797.43 million by 2032, with a CAGR of 8.6%.
- Growing awareness of the adverse effects of air and environmental pollution on health and skin is driving market demand.
- Consumer preference for clean beauty products and sustainable formulations is contributing to market expansion.
- Increasing respiratory and skin conditions linked to pollution exposure are encouraging the adoption of anti-pollution ingredients.
- High R&D investments are leading to the development of advanced ingredients like antioxidants, UV filters, and anti-inflammatory agents.
- North America and Europe are leading the market, supported by strong consumer awareness and regulatory frameworks for clean products.
- Rapid growth is expected in Asia Pacific due to rising pollution levels and a growing demand for personal care products.
Market Drivers
Increasing Consumer Awareness
Increasing awareness about the harmful effects of pollution on health and skin is a critical driver for the Anti-Pollution Ingredients Market. Consumers are becoming more educated on the impact of air pollution, particularly in urban areas, where levels of pollutants are higher. For instance, the World Health Organization (WHO) reports that more than 90% of the world’s population breathes polluted air, contributing to respiratory diseases and skin damage. As consumers seek to protect themselves from these risks, there is a growing demand for products that can shield against environmental pollutants. This awareness is prompting companies in the beauty and skincare industry to invest in anti-pollution ingredients. In 2021, 45% of consumers in the U.S. indicated they were willing to pay a premium for products that provide protection from pollution.
Regulatory Support for Clean Beauty
Government policies and regulations supporting clean beauty are fueling the demand for anti-pollution ingredients. In 2020, the European Union allocated €1 billion toward research and innovation for environmental sustainability, which includes support for cleaner, safer cosmetics and skincare formulations. This funding is helping to drive the development of ingredients that meet stricter environmental standards. Additionally, the European Commission has introduced regulations under the European Green Deal to improve environmental protection by reducing harmful emissions and promoting sustainable practices. For instance, the European Commission is aiming to reduce carbon emissions by at least 55% by 2030 compared to 1990 levels . Such regulatory frameworks have spurred the beauty industry to adopt cleaner, more sustainable formulations.
Health and Skin Conditions Linked to Pollution
Pollution-related health issues, including respiratory diseases and skin problems, have become a global concern. According to the World Bank, air pollution is responsible for 7 million premature deaths annually. Furthermore, studies have shown that exposure to pollutants accelerates the aging process and contributes to skin damage, such as pigmentation and wrinkles. In response, consumers are increasingly seeking skincare products that can help mitigate the effects of pollution. For instance, in 2019, the World Bank reported that pollution-related healthcare costs were approximately $5.11 trillion globally, highlighting the financial impact of pollution on health .This data underscores the growing demand for products designed to protect against the harmful effects of environmental pollutants.
Technological Advancements in Product Development
Technological advancements in the skincare industry are accelerating the development of anti-pollution ingredients. Companies are increasingly investing in research to create effective solutions to protect consumers from air pollutants, UV radiation, and environmental toxins. For instance, L'Oréal, a leader in the global beauty market, invested over €1 billion in research and innovation in 2020, with a focus on developing products that address consumer needs related to pollution. L'Oréal’s research into pollution-blocking ingredients led to the launch of several skincare lines in 2020 that incorporate advanced pollution-protective formulas. Additionally, the U.S. Environmental Protection Agency (EPA) is supporting research into the development of safer, non-toxic ingredients to protect consumers from pollution’s harmful effects, including the creation of pollutant-neutralizing compounds. These technological innovations are expected to further drive the market for anti-pollution ingredients.
Market Trends
Rising Demand for Clean and Sustainable Beauty Products
There is an increasing demand for clean and sustainable beauty products as consumers prioritize ingredients that are both effective and environmentally friendly. Governments and regulatory bodies around the world are taking steps to encourage sustainable product formulations. For example, the U.S. Environmental Protection Agency (EPA) allocated $50 million in 2020 to support projects aimed at developing safer chemical alternatives for consumer products. This push toward cleaner products is influencing the beauty industry to incorporate pollution-protective ingredients and sustainable packaging to meet consumer expectations. Additionally, the European Union is expected to direct €3.3 billion toward sustainability initiatives by 2023 to help industries reduce environmental impact and encourage greener practices (Source: European Investment Bank, 2020).
Technological Integration in Product Development
Technological advancements in product formulation and ingredient development are becoming key trends in the anti-pollution ingredients market. Companies are investing heavily in R&D to create new ingredients that offer superior protection against pollutants and environmental stressors. For example, Procter & Gamble invested approximately $3 billion in research and development in 2020, focusing on developing new and advanced skincare solutions. The rise of skin protection technologies, such as pollution-blocking compounds, is expected to further drive product innovation in this space. Government agencies, such as the U.S. Department of Energy, are also funding research into sustainable technology development to improve product formulations that can better protect consumers from environmental harm.
Rise of Urbanization and Pollution
The increasing levels of urbanization are driving the growth of the anti-pollution ingredients market. For Instance, According to the United Nations, more than 55% of the world’s population now lives in urban areas, and this figure is expected to rise to 68% by 2050. As cities become more congested and air pollution levels rise, there is a growing demand for solutions that help protect people from pollution-related health issues. The U.S. government, through its Centers for Disease Control and Prevention (CDC), reported that 45% of the U.S. population lives in areas with unhealthy air quality, further driving the need for protective skincare products.
Shift Toward Personalized Skincare Solutions
The trend of personalized skincare is rapidly gaining traction as consumers seek products that address their unique needs, particularly in relation to pollution. In response, many companies are developing customizable products that allow consumers to tailor their skincare routines based on factors such as pollution exposure and individual skin concerns. For example, in 2020, the U.S. Food and Drug Administration (FDA) approved the use of personalized skincare products containing pollution-protective ingredients. This regulatory shift has opened the door for the growth of customized anti-pollution solutions that cater to specific environmental factors, further expanding market potential.
Market Challenges Analysis
High Cost of Research and Development
One of the key challenges in the Anti-Pollution Ingredients Market is the significant investment required in research and development (R&D) to create new, effective, and safe ingredients. Developing anti-pollution ingredients requires advanced scientific research, which involves high costs, extensive testing, and regulatory approval processes. Companies must balance the need for innovation with the substantial financial resources needed to bring new products to market. For instance, in 2020, Procter & Gamble allocated $3 billion to R&D to improve the efficacy and safety of its skincare products, including those with pollution-protective ingredients. These high R&D costs can limit the ability of smaller companies to compete, as they may lack the necessary resources to invest in advanced ingredient development. Consequently, the market is often dominated by larger companies with the financial capacity to absorb the costs of innovation.
Regulatory Challenges and Compliance
The anti-pollution ingredients market also faces regulatory hurdles that can delay product development and market entry. Different countries have varying regulations regarding the safety, labeling, and approval of cosmetic and skincare ingredients, which adds complexity to the formulation and marketing processes. For example, the European Union’s regulatory framework for cosmetics is one of the strictest globally, requiring comprehensive testing and safety assessments before any product can be marketed. This includes ensuring that the ingredients used in anti-pollution products do not cause adverse effects on human health or the environment. In addition, the increasing pressure for sustainability and eco-friendly practices adds another layer of complexity, as companies must ensure their products meet evolving environmental standards. These regulatory challenges can result in extended timeframes for product development, increased costs, and, in some cases, restricted market access, which can hinder overall market growth.
Market Opportunities
The Anti-Pollution Ingredients Market presents significant opportunities for growth as consumer awareness continues to rise regarding the harmful effects of pollution on both health and beauty. This heightened awareness has spurred a demand for skincare and wellness products that offer protection against environmental pollutants, creating a lucrative market for anti-pollution ingredients. Companies can leverage this opportunity by developing innovative, science-backed products that offer multi-functional benefits such as anti-aging, hydration, and pollution defense. With increasing research into novel ingredients and their effectiveness in neutralizing pollutants, businesses can create advanced formulations that cater to a wide range of consumer needs. Additionally, as consumers seek sustainable and eco-friendly solutions, brands that prioritize clean and natural ingredients will benefit from growing market interest.
The Asia Pacific region, in particular, presents considerable opportunities due to the rapid urbanization and industrialization in countries like China, India, and Southeast Asia. As pollution levels rise in these areas, the demand for anti-pollution skincare products is expected to increase significantly. Companies entering this market can gain a competitive edge by developing region-specific products that address local pollution concerns. Moreover, the expansion of e-commerce platforms and increasing internet penetration in emerging markets further opens up distribution channels, making it easier for brands to reach a broader audience. This dynamic growth in Asia Pacific, combined with a strong push for clean beauty trends globally, offers ample opportunities for brands to expand their market share in both established and emerging markets.
Market Segmentation Analysis
By Type:
The market is primarily divided into ingredients such as antioxidants, anti-inflammatory agents, UV filters, and others. Antioxidants are the most commonly used anti-pollution ingredients due to their ability to neutralize free radicals produced by environmental pollutants. Anti-inflammatory agents help reduce skin irritation caused by pollutants, while UV filters are added to protect against UV radiation, which can be exacerbated by pollution. The demand for these ingredients is increasing as consumers become more concerned about pollution’s harmful effects on skin health.
By Technology:
The market is also segmented by technology, which includes advanced delivery systems, encapsulation technologies, and nanotechnology. Advanced delivery systems are increasingly used to enhance the effectiveness of anti-pollution ingredients by ensuring that they penetrate deeper into the skin. Encapsulation technology allows for controlled release of active ingredients, ensuring sustained protection throughout the day.
By End-User:
The anti-pollution ingredients market caters to various end-users, including skincare, haircare, and cosmetics industries. The skincare segment holds the largest share due to growing consumer demand for products that protect the skin from environmental damage. The haircare segment is also experiencing significant growth as consumers seek solutions to combat pollution-induced hair damage. Cosmetics companies are increasingly incorporating anti-pollution ingredients into their products to meet consumer demand for multi-functional solutions.
Segmentations
Based on Product Type:
- Antioxidants
- Anti-inflammatory Agents
- UV Filters
- Other Active Ingredients
Based on Technology:
- Advanced Delivery Systems
- Encapsulation Technologies
- Nanotechnology
- Other Technologies
Based on End-User:
- Skincare Industry
- Haircare Industry
- Cosmetics Industry
- Other Personal Care Industries
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the Anti-Pollution Ingredients Market, accounting for 35% of the global market. The region is characterized by high consumer awareness about pollution-related health risks and a strong demand for clean beauty products. The United States, in particular, has seen a growing trend of consumers seeking skincare and wellness products that offer protection against environmental pollutants. This demand is further fueled by the rise of urbanization and pollution in major cities like Los Angeles and New York, where air quality is often compromised. Additionally, regulatory support for clean beauty and sustainable formulations is further driving market growth in North America.
Europe
Europe is another dominant region in the Anti-Pollution Ingredients Market, holding a market share of around 30%. The European market benefits from stringent environmental regulations and a strong emphasis on sustainability. The European Union’s Green Deal, which aims to reduce carbon emissions by 2030, is contributing to the shift toward more eco-friendly products. Countries like Germany, the United Kingdom, and France are seeing an increased demand for skincare products that protect against pollution and environmental stressors. Moreover, European consumers are highly conscious about the ingredients in their skincare products, which has driven a surge in demand for natural, pollution-blocking solutions. Leading brands in the region, such as L'Oréal and Unilever, are capitalizing on this trend by offering a range of anti-pollution skincare lines.
Asia Pacific
Asia Pacific is expected to experience rapid growth in the Anti-Pollution Ingredients Market, driven by increasing pollution levels and a rising middle class in countries like China, India, and Japan. The region holds a market share of around 25% and is forecasted to see substantial expansion in the coming years. This environmental concern has led to greater consumer interest in products that offer protection against pollutants. Additionally, India’s rapidly growing urban population is contributing to rising pollution levels, further driving the demand for anti-pollution ingredients. As awareness about the harmful effects of pollution on skin health increases, the region is seeing a surge in demand for skincare solutions designed to protect against these environmental stressors.
Key Player Analysis
- L'Oréal
- Estée Lauder
- Unilever
- Procter & Gamble
- Johnson & Johnson
- Shiseido
- Amorepacific Corporation
- Coty Inc.
- Beiersdorf AG
- Clarins Group
Competitive Analysis
The Anti-Pollution Ingredients Market is highly competitive, with leading players constantly innovating to meet the growing demand for products that offer protection against environmental pollutants. Major companies like L'Oréal, Estée Lauder, and Procter & Gamble dominate the market by investing heavily in research and development to create advanced anti-pollution formulations. For instance, L'Oréal has been at the forefront, incorporating pollution-protective ingredients in its skincare lines through its Active Cosmetics division. Additionally, Unilever and Johnson & Johnson have focused on sustainability, incorporating eco-friendly ingredients and packaging into their products to appeal to environmentally conscious consumers. The competition is also intensifying from emerging regional players, particularly in Asia Pacific, where countries like China and India are experiencing a surge in demand for anti-pollution skincare. As regulatory frameworks tighten and consumer preferences evolve, these companies are also adapting by integrating advanced technologies like nanotechnology and encapsulation systems to enhance the efficacy of their products.
Recent Developments
- October 14, 2024: L'Oréal partnered with Abolis Biotechnologies and Evonik to develop bio-based ingredients that aim to reduce environmental pollution. This collaboration focuses on creating sustainable, bio-identical ingredients to enhance the eco-friendliness of L'Oréal's product formulations, supporting its sustainability goals.
- November 27, 2024: Unilever partnered with Nufarm to develop a new variety of sugar cane capable of producing plant-based oils for cleaning products and personal care items. This initiative aims to reduce reliance on petrochemical ingredients and supports Unilever’s goal of achieving net-zero emissions across its value chain by 2039.
- January 1, 2025: Procter & Gamble reaffirmed its commitment to achieving net-zero greenhouse gas emissions across its supply chain by 2040. The company is prioritizing sustainability in its product formulations, including developing anti-pollution ingredients to meet consumer demand for safer and more environmentally friendly products.
- March 9, 2024: Johnson & Johnson announced an $800 million investment through its Healthy Lives Mission to enhance the sustainability of its products. The investment focuses on recyclable packaging and transparent ingredient sourcing to improve consumer trust and reduce environmental impact.
Market Concentration & Characteristics
The Anti-Pollution Ingredients Market exhibits moderate concentration, with a few large multinational companies dominating the landscape. Key players such as L'Oréal, Estée Lauder, Unilever, and Procter & Gamble control a significant portion of the market, benefiting from their established brand recognition, extensive R&D capabilities, and global distribution networks. These companies are continuously investing in innovative technologies and sustainable practices to meet consumer demand for eco-friendly and effective anti-pollution solutions. However, the market also features numerous regional and smaller players that cater to niche markets, particularly in emerging economies like China and India, where pollution levels are high. The characteristics of the market include strong competition for product differentiation, with a focus on clean, sustainable ingredients and advanced delivery technologies. Furthermore, regulatory standards and consumer preference for transparency in ingredient sourcing are pushing companies toward more sustainable and environmentally friendly product formulations.
Report Coverage
The research report offers an in-depth analysis Based on Product Type, Based on Technology, Based on End-User, Based on Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for anti-pollution ingredients is expected to continue growing as awareness of the harmful effects of pollution on skin health and overall well-being increases globally.
- Regulatory support for clean and sustainable beauty products will drive further innovation and compliance with eco-friendly standards in the skincare industry.
- Technological advancements, such as nanotechnology and encapsulation methods, will continue to enhance the efficacy of anti-pollution ingredients, offering consumers more effective protection.
- The Asia Pacific region will likely see the highest growth in the anti-pollution ingredients market due to increasing urbanization and rising pollution levels in countries like China and India.
- Companies are expected to focus more on developing customized anti-pollution solutions tailored to specific regional pollution concerns and consumer preferences.
- Growing investments in R&D by both established players and new entrants will lead to the introduction of innovative products designed to tackle a broader range of environmental pollutants.
- Consumers’ shift toward clean beauty and sustainable products will push companies to focus on eco-friendly ingredients and packaging, reducing their environmental footprint.
- As urban populations continue to grow, there will be a greater emphasis on pollution-related skincare solutions, particularly in cities with poor air quality and rising pollution levels.
- The growing incidence of skin conditions linked to pollution exposure will further boost the demand for anti-pollution skincare products, especially among consumers in high-pollution areas.
- Increased collaboration between skincare companies, research institutions, and government bodies will foster the development of more advanced and effective anti-pollution technologies in the coming years.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Consumer Awareness
Growing knowledge about the harmful effects of air and environmental pollution on health and skin is prompting consumers to seek products with anti-pollution ingredients, especially in urban areas with high pollution levels.
Regulatory Support for Clean Beauty
Government policies and regulations in regions like the EU and North America are encouraging the use of clean, sustainable, and safe ingredients, pushing companies to innovate and adopt anti-pollution formulations.
Rising Incidence of Pollution-Related Health and Skin Conditions
The increasing prevalence of respiratory diseases, allergies, and premature skin aging linked to pollution exposure is driving demand for ingredients that can protect and repair the skin and body.
Technological Advancements in Ingredient Development
Investments in R&D are leading to the creation of advanced anti-pollution ingredients such as antioxidants, encapsulated actives, and nanotechnology-based solutions, enhancing product efficacy and consumer appeal.
Urbanization and Pollution Growth in Emerging Markets
Rapid urbanization and industrialization in regions like Asia Pacific are resulting in higher pollution levels, which in turn is fueling demand for anti-pollution personal care products tailored to local environmental challenges.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the growth forecast for the Anti-Pollution Ingredients Market?
What is driving the growth of the Anti-Pollution Ingredients Market?
Which regions are leading the Anti-Pollution Ingredients Market?
What opportunities exist for growth in the Anti-Pollution Ingredients Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Skincare Industry
- 1.2.2 Haircare Industry
- 1.2.3 Cosmetics Industry
- 1.2.4 Other Personal Care Industries
- 1.3 By Technology
- 1.3.1 Advanced Delivery Systems
- 1.3.2 Encapsulation Technologies
- 1.3.3 Nanotechnology
- 1.3.4 Other Technologies
- 1.4 By Product Type
- 1.4.1 Antioxidants
- 1.4.2 Anti-inflammatory Agents
- 1.4.3 UV Filters
- 1.4.4 Other Active Ingredients
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 929 million → 2032: USD 1797.43 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Anti-Pollution Ingredients Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Anti-Pollution Ingredients Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Anti-Pollution Ingredients Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Anti-Pollution Ingredients Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Anti-Pollution Ingredients Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Anti-Pollution Ingredients Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Anti-Pollution Ingredients Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Anti-Pollution Ingredients Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 929 million → 2032: USD 1797.43 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Anti-Pollution Ingredients Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Skincare Industry
- 12.3.7.2 Haircare Industry
- 12.3.7.3 Cosmetics Industry
- 12.3.7.4 Other Personal Care Industries
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Advanced Delivery Systems
- 12.4.7.2 Encapsulation Technologies
- 12.4.7.3 Nanotechnology
- 12.4.7.4 Other Technologies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Antioxidants
- 12.5.7.2 Anti-inflammatory Agents
- 12.5.7.3 UV Filters
- 12.5.7.4 Other Active Ingredients
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Anti-Pollution Ingredients End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Anti-Pollution Ingredients Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Anti-Pollution Ingredients Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Anti-Pollution Ingredients Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 L'Oréal
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Estée Lauder
- 18.4 Unilever
- 18.5 Procter & Gamble
- 18.6 Johnson & Johnson
- 18.7 Shiseido
- 18.8 Amorepacific Corporation
- 18.9 Coty Inc.
- 18.10 Beiersdorf AG
- 18.11 Clarins Group
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
