
Anti Pollution Skincare Products Market Overview:
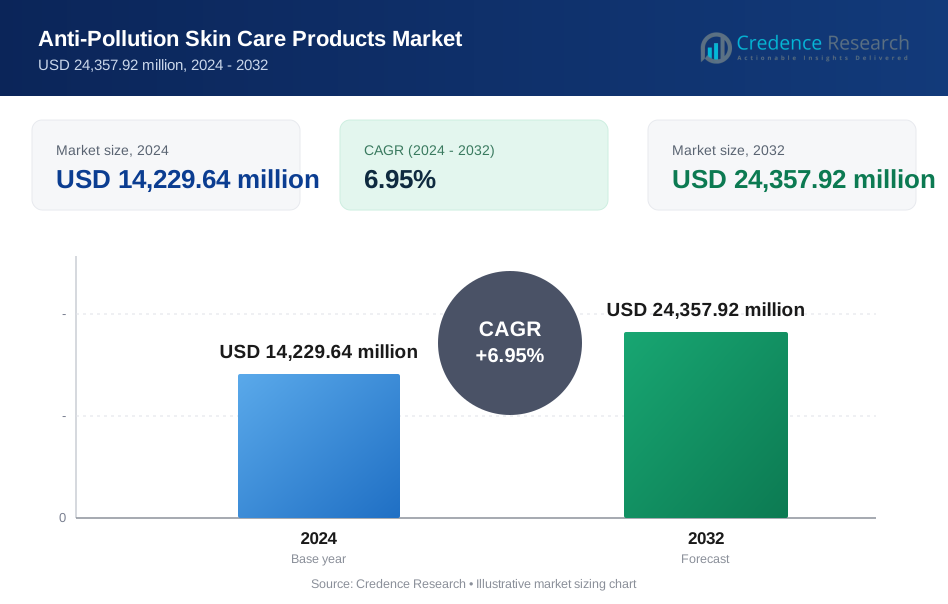
Anti Pollution Skincare Products Market size was valued USD 14229.64 million in 2024 and is anticipated to reach USD 24357.92 million by 2032, at a CAGR of 6.95% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Anti Pollution Skincare Products Market Size 2024 | USD 14229.64 million |
| Anti Pollution Skincare Products Market, CAGR | 6.95% |
| Anti Pollution Skincare Products Market Size 2032 | USD 24357.92 million |
Anti Pollution Skincare Products Market Insights
- Market growth is primarily driven by increasing urban air pollution, higher incidence of premature aging, and growing demand for preventive skincare, with moisturizers and creams emerging as the dominant product segment due to daily-use relevance.
- Key market trends include strong adoption of antioxidant-rich formulations, barrier-repair ingredients, and multifunctional products combining anti-pollution, hydration, and UV protection benefits.
- The competitive landscape remains intense, with leading players focusing on clinically validated claims, rapid product innovation, premiumization strategies, and expansion across digital and direct-to-consumer channels.
- Asia-Pacific leads the market with an exact 41% share, while North America and Europe follow, although high product pricing and regulatory scrutiny act as moderate restraints in price-sensitive regions.

Anti Pollution Skincare Products Market Segmentation Analysis:
By Product Type
By product type, cleansers & face washes emerge as the dominant sub-segment in the anti-pollution skincare products market, accounting for an estimated 31% market share. Their leadership is driven by their role as the first line of defense against urban pollutants, particulate matter, and excess sebum accumulated on the skin surface. Daily usage frequency, compatibility with all skin types, and innovation in sulfate-free, pH-balanced, and micellar-based formulations further support adoption. Moisturizers & creams follow, supported by demand for long-lasting protective barriers, while serums & essences gain traction due to high active concentration and targeted pollution-defense claims.
- For instance, Kao Corporation has developed Fine Fiber Technology, which creates an ultra-thin membrane to protect against and remove particulate contaminants as small as 2.5 micrometers (PM2.5). Separately, their high-density micro-bubble cleansing technology (found in brands like Bioré) uses fine foam to penetrate pores and remove impurities while maintaining a skin-friendly environment.
By Ingredient Type
By ingredient type, antioxidants dominate the segment with an estimated 29% market share, driven by their proven ability to neutralize free radicals generated by pollution exposure. Ingredients such as vitamin C, vitamin E, and niacinamide are widely incorporated due to their efficacy in reducing oxidative stress and strengthening skin resilience. Botanical extracts follow, benefiting from consumer preference for natural and plant-based solutions. Activated charcoal remains relevant in detoxifying products, particularly cleansers and masks, while barrier repair agents gain momentum as consumers seek formulations that reinforce the skin’s natural defense against environmental aggressors.
- For instance, L’Oréal’s Beauty Tech ecosystem maintains and analyzes over 17,300 terabytes of skin and beauty data as of late 2025. This vast database is used to refine predictive models for how ingredients like antioxidants perform across diverse skin profiles, enabling personalized 'Longevity Integrative Science' and enhanced ingredient-to-benefit mapping in its product pipelines.
By Skin Concern
By skin concern, anti-aging represents the leading sub-segment, holding approximately 34% market share, as pollution-induced oxidative stress accelerates fine lines, wrinkles, and loss of elasticity. Urban consumers increasingly associate pollution exposure with premature aging, driving demand for preventive and corrective solutions. Hyperpigmentation and dullness & fatigue follow, supported by rising cases of uneven skin tone and lackluster appearance linked to environmental stressors. Products targeting sensitive skin and redness also see steady growth, reflecting heightened awareness of pollution-triggered inflammation and barrier damage among consumers living in densely populated cities.
Key Growth Drivers
Rising Urbanization and Pollution Exposure
Accelerating urbanization has intensified daily exposure to airborne pollutants such as particulate matter, nitrogen oxides, and heavy metals, directly impacting skin health. Consumers increasingly link pollution to premature aging, hyperpigmentation, and barrier damage, driving demand for protective skincare solutions. Anti-pollution products that claim detoxification, antioxidant defense, and barrier reinforcement are gaining traction, particularly in densely populated cities. This heightened awareness, supported by dermatological research and media coverage, continues to expand the consumer base seeking preventive and corrective skincare solutions tailored to polluted environments.
- For instance, P&G’s R&D organization maintains a global intellectual property portfolio with over 35,000 active patents supporting breakthroughs in formulation chemistry, skin-friendly delivery systems, and multifunctional actives that strengthen resilience against environmental stressors while maintaining consumer-preferred sensorial properties.
Increasing Consumer Awareness and Preventive Skincare Adoption
Growing awareness around preventive skincare is a key driver for anti-pollution products. Consumers are shifting from reactive treatments to daily regimens that protect against environmental aggressors. Educational campaigns, dermatologist endorsements, and digital content explaining the link between pollution and skin aging have strengthened this shift. As skincare routines become more sophisticated, consumers actively seek formulations with antioxidants, chelating agents, and barrier-repair ingredients. This proactive mindset supports sustained demand across age groups, especially among millennials and urban professionals focused on long-term skin health.
- For instance, Avon’s Protinol™ technology developed through over a decade of proprietary research and integrated into its ANEW range has been shown in controlled consumer studies of 129 participants to increase structural collagen and elastin synthesis in the epidermis within 7 days of daily application, outperforming traditional retinol benchmarks documented in company reports.
Innovation in Formulations and Ingredient Technologies
Continuous innovation in ingredient science significantly fuels market growth. Brands are developing advanced formulations incorporating encapsulated antioxidants, botanical extracts, and multifunctional actives that neutralize pollutants and strengthen the skin barrier. Improved delivery systems enhance ingredient stability and skin penetration, increasing product efficacy. Additionally, the integration of anti-pollution benefits into everyday products such as cleansers, moisturizers, and sunscreens broadens usage occasions. This steady pipeline of innovation differentiates products in a competitive landscape and encourages repeat purchases.
Key Trends & Opportunities
Expansion of Clean, Natural, and Sustainable Product Lines
A strong trend toward clean and sustainable beauty is shaping the anti-pollution skincare market. Consumers increasingly prefer products formulated with natural, plant-based, and ethically sourced ingredients, free from harsh chemicals. This creates opportunities for brands to combine anti-pollution claims with clean-label positioning and eco-friendly packaging. Transparency in sourcing, biodegradable materials, and cruelty-free certifications further enhance brand credibility, enabling companies to attract environmentally conscious consumers while aligning with broader sustainability goals.
- For instance, Estée Lauder’s CollaNight-8™ technology has been quantified through in-vitro assays to deliver up to a 10 fold increase in skin’s natural collagen production potential over 96 hours versus untreated controls, with measurable barrier fortification and resilience improvements observed within 4 hours of application in clinical testing.
Integration of Anti-Pollution Benefits into Multifunctional Products
Multifunctionality is emerging as a major opportunity, as consumers favor streamlined skincare routines. Products that combine anti-pollution protection with hydration, UV defense, anti-aging, or brightening benefits are gaining popularity. This trend supports premiumization, as consumers are willing to invest in high-performance, all-in-one solutions. Brands that successfully communicate multiple benefits without compromising efficacy can expand their addressable market and increase average spending per consumer.
- For instance, Unilever has secured more than 100 patents in skin microbiome research and maintains one of the world’s largest human skin microbiome datasets encompassing over 30,000 analysed samples, enabling quantifiable insights into microbiome actives interactions and personalised product development.
Growth of Digital Channels and Personalized Skincare
Digital platforms are reshaping how anti-pollution skincare products reach consumers. Online consultations, AI-driven skin diagnostics, and personalized product recommendations enable brands to tailor solutions based on individual pollution exposure and skin concerns. This creates opportunities for data-driven personalization and direct-to-consumer models, improving customer engagement and loyalty. As digital literacy increases, especially in urban regions, brands leveraging technology can gain a competitive advantage.
Key Challenges
Regulatory Scrutiny and Claim Substantiation
One of the primary challenges is increasing regulatory scrutiny around product claims. Anti-pollution benefits are often complex to measure, requiring robust scientific validation and standardized testing methods. Regulatory bodies closely examine claims related to detoxification, protection, and repair, raising compliance costs and extending product development timelines. Brands must invest in clinical testing and transparent communication to avoid misleading claims, which can strain smaller players and slow innovation cycles.
Intense Competition and Product Differentiation
The market faces intense competition due to the low entry barrier in skincare and the rapid proliferation of anti-pollution claims. Many products offer similar ingredient profiles and benefits, making differentiation challenging. Price competition and marketing noise can erode brand value and margins. To stand out, companies must continuously innovate, invest in branding, and clearly demonstrate efficacy, which increases operational complexity and costs in an already crowded marketplace.
Regional Analysis
North America
North America leads the anti-pollution skincare products market with an estimated 38% market share, driven by high urban pollution awareness, strong dermatological research, and premium skincare adoption. Consumers actively seek products with antioxidants, blue-light protection, and barrier-repair claims, particularly in the U.S. and Canada. Established beauty brands leverage clinical testing, dermatologist endorsements, and omnichannel retail strategies to reinforce trust and visibility. The region also benefits from advanced regulatory frameworks and high disposable incomes, supporting demand for multifunctional formulations such as anti-pollution serums and sunscreens integrated into daily routines. Innovation in clean-label and dermatologist-tested products further sustains market leadership.
Europe
Europe accounts for approximately 27% market share, supported by stringent environmental regulations, rising pollution concerns in major cities, and a strong preference for sustainable skincare. Countries such as France, Germany, and the UK emphasize natural, organic, and cruelty-free formulations with anti-oxidative and detoxifying benefits. Consumers show high awareness of long-term skin damage caused by particulate matter, encouraging adoption of anti-pollution cleansers and moisturizers. The market benefits from strong pharmacy and specialty retail channels, while regulatory focus on ingredient transparency and eco-friendly packaging accelerates innovation. Premiumization and science-backed claims remain central to competitive positioning across the region.
Asia-Pacific
Asia-Pacific holds nearly 24% market share and represents the fastest-growing region due to severe urban air pollution, dense populations, and evolving beauty standards. Countries such as China, India, South Korea, and Japan drive demand for anti-pollution skincare as part of daily preventive routines. Consumers favor lightweight formulations, multi-step regimens, and products infused with botanical and fermented ingredients. Rapid expansion of e-commerce, social-media-driven beauty trends, and rising middle-class incomes significantly boost market penetration. Local brands and global players increasingly tailor products to regional skin types and climatic conditions, strengthening adoption across both mass and premium segments.
Latin America
Latin America captures around 7% market share, supported by increasing urbanization, traffic-related pollution, and growing skincare awareness. Brazil and Mexico dominate regional demand, driven by expanding middle-income populations and rising exposure to global beauty trends. Consumers increasingly seek affordable anti-pollution solutions integrated into daily skincare, particularly cleansers and moisturizers. Growth is reinforced by wider availability through drugstores, supermarkets, and online platforms. Although price sensitivity remains a challenge, brands focusing on multifunctional benefits, natural extracts, and climate-specific formulations are gaining traction. Educational marketing around pollution-related skin damage continues to support gradual market expansion.
Middle East & Africa
The Middle East & Africa region accounts for approximately 4% market share, with growth driven by harsh climatic conditions, dust pollution, and increasing beauty consciousness. Urban centers in the GCC countries show rising demand for protective skincare addressing pollution, UV exposure, and dehydration. Premium products perform well due to higher disposable incomes, while mass-market offerings gain traction in emerging African economies. Expansion of modern retail formats and digital beauty platforms improves product accessibility. Although awareness levels vary across countries, targeted marketing, climate-adapted formulations, and growing interest in dermatology-backed skincare support steady regional market development.
Anti Pollution Skincare Products Market Segmentations:
By Product Type:
- Cleansers & Face Washes
- Moisturizers & Creams
By Ingredient Type:
- Activated Charcoal
- Antioxidants (e.g., Vitamin C, E, Niacinamide)
By Skin Concern:
- Anti-Aging
- Dryness & Dehydration
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the anti-pollution skincare products market players such as Kao Corporation; Revlon; L'Oréal S.A.; ORIFLAME COSMETICS S.A.; Procter & Gamble; AVON PRODUCTS, INC; Estée Lauder; Coty Inc.; Unilever; Shiseido. the anti-pollution skincare products market is moderately consolidated and shaped by continuous innovation, strong branding, and expanding global distribution.
Companies compete by developing advanced formulations that incorporate antioxidants, anti-adhesion agents, and skin barrier–strengthening actives designed to protect against particulate matter, heavy metals, and environmental stressors. Differentiation largely depends on clinically supported performance claims, premium product positioning, and customization for urban and high-pollution consumer segments. Market participants actively adopt digital marketing strategies, influencer partnerships, and direct-to-consumer channels to enhance brand visibility and consumer engagement.
Expansion across e-commerce, specialty beauty retailers, and dermatology-focused outlets further strengthens competitive reach. In parallel, sustainability has become a critical competitive factor, with increasing emphasis on clean formulations, ethical sourcing, and recyclable packaging. Overall, innovation capability, marketing effectiveness, and omnichannel presence remain the primary drivers shaping competition in this evolving market.
Key Player Analysis
- Kao Corporation
- Revlon
- L'Oréal S.A.
- ORIFLAME COSMETICS S.A.
- Procter & Gamble
- AVON PRODUCTS, INC
- Estée Lauder
- Coty Inc.
- Unilever
- Shiseido
Recent Developments
- In May 2025, The U.S. Medical Glove Company (USMGC) began operations at its new face mask manufacturing facility, strengthening the domestic healthcare supply chain. The facility operates six high-speed production lines for manufacturing 3 ply disposable face masks, supporting USMGC's commitment to producing medical supplies in the United States.
- In December 2024, SCINQ Neurocosmetics, a pioneering skincare brand, has launched in India, bringing a transformative approach that bridges skin health and mental wellness. The brand was founded by wellness advocates Shrishti Yadav and Shubham Godara. SCINQ unveiled a line of neurocosmetic skincare products to showcase modern-day challenges.
- In April 2024, Cipla Limited, one of the prominent organizations in the pharmaceutical industry, acquired the global distribution and marketing business of Ivia Beaute Private Limited, India, including its brands Ikin, Astaberry, and Bhimsaini, through its wholly-owned subsidiary Cipla Health Limited.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Ingredient Type, Skin Concern and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Rising urban air pollution levels will continue to drive daily-use anti-pollution skincare adoption across mass and premium segments.
- Demand will strengthen for products offering multifunctional benefits such as cleansing, barrier repair, antioxidant protection, and UV defense.
- Innovation will increasingly focus on advanced antioxidants, bio-fermented ingredients, and skin microbiome–friendly formulations.
- Consumers will favor clinically validated products with proven efficacy against particulate matter, heavy metals, and oxidative stress.
- Growth will accelerate in Asia-Pacific due to dense urban populations, worsening air quality, and strong beauty awareness.
- Brands will expand gender-neutral and men-specific anti-pollution skincare lines to capture underserved consumer groups.
- Digital skin diagnostics and personalized product recommendations will gain importance in product positioning and marketing strategies.
- Sustainable, clean-label, and environmentally responsible formulations will become key purchase decision factors.
- E-commerce and direct-to-consumer channels will play a larger role in product launches and consumer education.
- Regulatory scrutiny and ingredient transparency will shape product development and claims over the coming years.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Urbanization and Pollution Exposure
Accelerating urbanization has increased daily exposure to airborne pollutants, which directly impacts skin health and drives demand for anti-pollution skincare solutions that detoxify, protect, and reinforce the skin barrier, especially in densely populated cities.
Increasing Consumer Awareness and Preventive Skincare Adoption
Consumers are shifting from reactive treatments to daily preventive regimens, seeking products with antioxidants and barrier-repair ingredients due to growing awareness of pollution's link to premature aging and skin damage, supported by educational campaigns and dermatologist endorsements.
Innovation in Formulations and Ingredient Technologies
Continuous advancements in ingredient science, such as encapsulated antioxidants and multifunctional actives, are enabling brands to offer more effective anti-pollution products, broadening usage occasions and encouraging repeat purchases through improved efficacy and stability.
Expansion of Clean, Natural, and Sustainable Product Lines
A strong consumer preference for clean-label, plant-based, and sustainably packaged products is driving brands to innovate with natural ingredients and eco-friendly packaging, attracting environmentally conscious buyers and aligning with global sustainability trends.
Growth of Digital Channels and Personalized Skincare
The rise of digital platforms, AI-driven diagnostics, and personalized product recommendations is enabling brands to tailor anti-pollution skincare solutions to individual needs, enhancing customer engagement and expanding reach through direct-to-consumer and e-commerce channels.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Anti Pollution Skincare Products Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Anti Pollution Skincare Products Market projected to grow between 2024 and 2032?
Which Anti Pollution Skincare Products Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Anti Pollution Skincare Products Market?
Who are the leading companies in the Anti Pollution Skincare Products Market?
Which region commanded the largest share of the Anti Pollution Skincare Products Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Cleansers & Face Washes
- 1.2.2 Moisturizers & Creams
- 1.2.3 Serums & Essences
- 1.2.4 Masks & Peels
- 1.2.5 Sunscreens
- 1.3 By Skin Concern
- 1.3.1 Anti-Aging
- 1.3.2 Hyperpigmentation
- 1.3.3 Dullness & Fatigue
- 1.3.4 Sensitive Skin & Redness
- 1.3.5 Dryness & Dehydration
- 1.4 By Ingredient Type
- 1.4.1 Antioxidants (e.g., Vitamin C, E, Niacinamide)
- 1.4.2 Botanical Extracts
- 1.4.3 Activated Charcoal
- 1.4.4 Barrier Repair Agents
- 1.4.5 Chelating Agents
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 14,229.64 million → 2032: USD 24,357.92 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Anti-Pollution Skin Care Products Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Anti-Pollution Skin Care Products Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Anti-Pollution Skin Care Products Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Anti-Pollution Skin Care Products Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Anti-Pollution Skin Care Products Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Anti-Pollution Skin Care Products Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Anti-Pollution Skin Care Products Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Anti-Pollution Skin Care Products Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 14,229.64 million → 2032: USD 24,357.92 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Anti-Pollution Skin Care Products Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cleansers & Face Washes
- 12.3.7.2 Moisturizers & Creams
- 12.3.7.3 Serums & Essences
- 12.3.7.4 Masks & Peels
- 12.3.7.5 Sunscreens
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Skin Concern - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Anti-Aging
- 12.4.7.2 Hyperpigmentation
- 12.4.7.3 Dullness & Fatigue
- 12.4.7.4 Sensitive Skin & Redness
- 12.4.7.5 Dryness & Dehydration
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Ingredient Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Antioxidants (e.g., Vitamin C, E, Niacinamide)
- 12.5.7.2 Botanical Extracts
- 12.5.7.3 Activated Charcoal
- 12.5.7.4 Barrier Repair Agents
- 12.5.7.5 Chelating Agents
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Anti-Pollution Skin Care Products Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Anti-Pollution Skin Care Products Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Anti-Pollution Skin Care Products Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Kao Corporation
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 L'Oréal S.A.
- 17.4 Unilever
- 17.5 Estée Lauder
- 17.6 Shiseido
- 17.7 Procter & Gamble
- 17.8 AVON PRODUCTS, INC
- 17.9 Coty Inc.
- 17.10 Revlon
- 17.11 ORIFLAME COSMETICS S.A.
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
