
Arthroscopy Devices Market Overview:
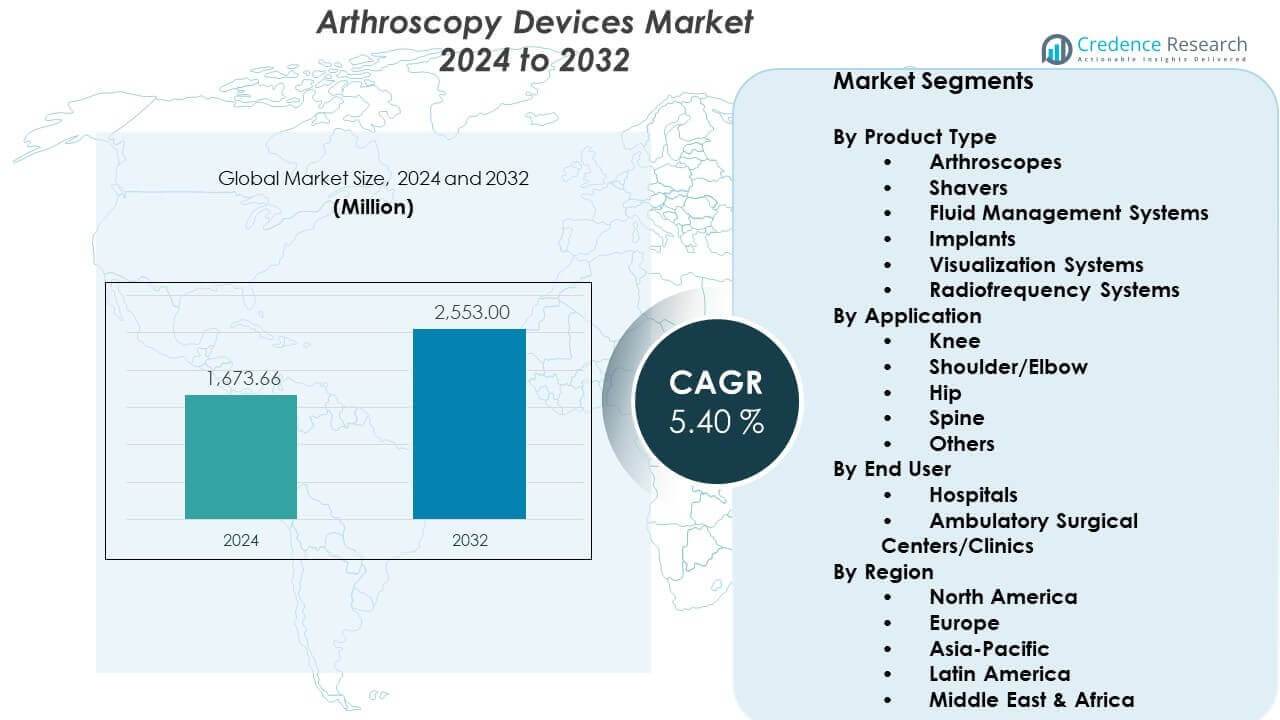
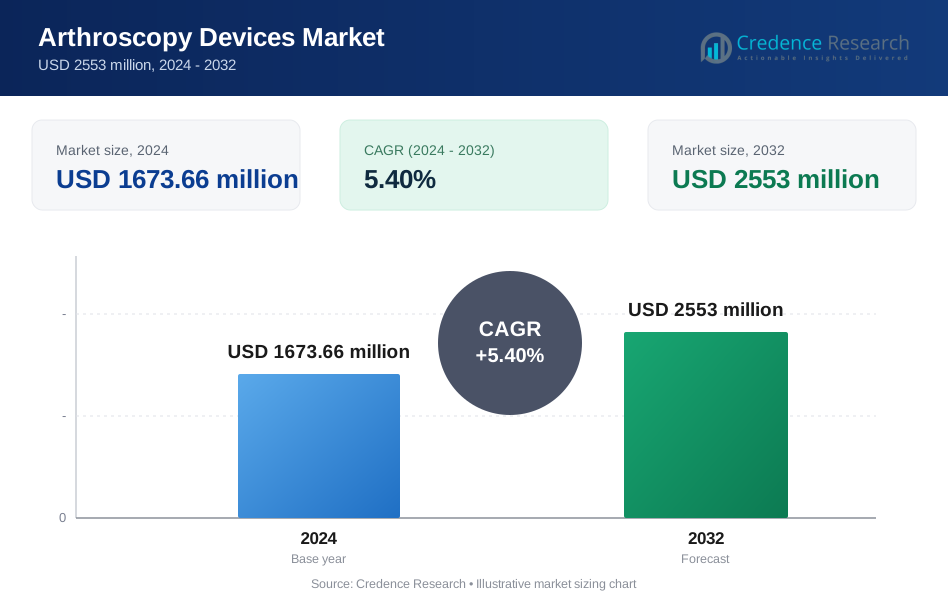
The Arthroscopy Devices Market is projected to grow from USD 1673.66 million in 2024 to an estimated USD 2553 million by 2032, with a compound annual growth rate (CAGR) of 5.40% from 2024 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Arthroscopy Devices Market Size 2024 | USD 1673.66 million |
| Arthroscopy Devices Market, CAGR | 5.40% |
| Arthroscopy Devices Market Size 2032 | USD 2553 million |
Market drivers center on rising cases of sports injuries, osteoarthritis, and trauma-related joint issues, which push healthcare providers to adopt advanced arthroscopic tools. Surgeons prefer minimally invasive methods because these systems reduce surgical complications, increase procedural precision, and support faster patient mobility. Leading companies expand their portfolios with 4K and 3D imaging platforms, flexible scopes, and energy devices to meet the growing need for efficiency in operating rooms. Hospitals also upgrade equipment to improve diagnostic accuracy and treatment reliability.
North America leads the global Arthroscopy Devices Market due to strong orthopedic procedure volumes, an established hospital network, and rapid integration of advanced surgical systems. Europe follows, supported by favorable reimbursement structures and steady demand for minimally invasive orthopedic interventions. Asia Pacific emerges as the fastest-growing region, driven by rising healthcare investments, expanding medical tourism, and growing awareness about early joint treatment. Countries in Latin America and the Middle East show increasing adoption as healthcare infrastructure modernizes and access to specialized orthopedic care improves.
Arthroscopy Devices Market Insights:
- The Arthroscopy Devices Market is projected to grow from USD 1673.66 million in 2024 to USD 2553 million by 2032, advancing at a 5.40% CAGR, driven by rising minimally invasive orthopedic procedures and steady technology adoption.
- North America holds 40% of the market due to high procedure volumes and strong adoption of advanced surgical systems; Europe accounts for 30% supported by established orthopedic networks; Asia-Pacific captures 20% with rapid investment in healthcare modernization.
- Asia-Pacific is the fastest-growing region with a 20% share, supported by expanding orthopedic capacity, higher sports injury incidence, and broader access to advanced visualization systems.
- Knee applications represent about 45% of total procedure usage, supported by high sports-related injury rates and strong demand for ligament repair and reconstruction.
- Hospitals account for nearly 70% of overall device utilization due to broader caseloads, advanced imaging access, and higher adoption of integrated arthroscopy towers.
Arthroscopy Devices Market Drivers:
Rising Procedure Volumes and Expanding Demand for Minimally Invasive Joint Interventions
The Arthroscopy Devices Market grows due to rising joint disorder cases and wider use of minimally invasive procedures. Surgeons prefer these tools because they improve accuracy and reduce recovery periods. Hospitals invest in upgraded scopes to support complex orthopedic needs. Sports injury cases push higher adoption across major care centers. Younger patients seek faster recovery paths, which strengthens demand. It encourages manufacturers to design integrated visualization systems. Clinicians value systems that provide real-time clarity during surgery. Many providers report steady gains in arthroscopy volumes each year.
- For instance, Arthrex’s NanoScope system utilizes a 1.9 mm chip-on-tip camera technology, which has enabled a shift toward needle arthroscopy in physician offices, allowing for diagnostic procedures that take less than 20 minutes and eliminate the need for general anesthesia.
Advancements in Imaging Platforms That Improve Diagnostic and Surgical Precision
High-definition imaging innovations strengthen the Arthroscopy Devices Market by improving joint assessment quality. Surgeons depend on sharper visuals to guide complex procedures. Manufacturers invest in 4K workflows that support precision-driven decisions in operating rooms. It allows clinicians to detect micro-tears with greater accuracy. Compact camera heads give surgeons better maneuverability during fast-paced cases. Integrated light systems offer stable brightness across tight joint spaces. Hospitals report better outcomes with advanced visualization packages. Growing demand for clarity encourages higher adoption across mid-sized care facilities.
- For instance, Stryker’s 1688 AIM 4K Platform features a 32-inch monitor with 4K resolution and fluorescence imaging capabilities, allowing surgeons to visualize blood flow and critical anatomy in real-time with 4 times the pixel density of standard HD systems.
Growing Preference for Day-Care Orthopedic Procedures Across Expanding Hospital Networks
Outpatient orthopedic centers support the Arthroscopy Devices Market by enabling faster scheduling and reduced patient stays. Care providers shift procedures to ambulatory settings to improve efficiency. It supports wider device procurement across independent surgical centers. Surgeons gain flexibility through standardized device trays and portable towers. Patient demand for shorter stays pushes more hospitals to upgrade systems. New workflow designs reduce bottlenecks in crowded orthopedic units. Expansion of outpatient facilities increases device turnover rates. Health systems continue to integrate arthroscopy suites into new buildings.
R&D Expansion and Technology Integration That Enhances Procedure Outcomes and Surgical Efficiency
Manufacturers strengthen the Arthroscopy Devices Market through investments in next-generation handheld tools and energy systems. Engineers design platforms that improve tissue handling and safety. It drives strong interest in multifunctional systems that reduce instrument changes. New ergonomic handles improve surgeon comfort during long procedures. Electromechanical tools support controlled movements in delicate joint regions. Robotics-assisted modules enter development pipelines across major players. Hybrid solutions pair imaging and navigation features for better alignment. Hospitals seek integrated stacks that unify imaging, insufflation, and recording.
Arthroscopy Devices Market Trends:
Rapid Shift Toward Fully Integrated Surgical Towers With Unified Control Systems
The Arthroscopy Devices Market sees a rising trend toward integrated towers that streamline workflows. Hospitals seek systems that combine imaging, recording, and power controls. It reduces clutter in tight operating rooms and enhances staff efficiency. Standardized towers also improve training for new surgeons. Networks purchase compatible components to simplify procurement. Many facilities aim to unify arthroscopy, laparoscopy, and ENT platforms. This trend helps reduce maintenance complexity across departments. Surgeons report improved coordination when all devices operate under a single interface.
Growing Adoption of Disposable Visualization and Instrumentation Lines Across High-Volume Centers
High-volume surgical units expand disposable arthroscopy tool usage to improve sterility assurance. Many hospitals shift to single-use scopes to limit contamination risks. It reduces downtime linked to reprocessing delays. Procedural consistency improves through standardized disposable sets. Centers handling sports injuries adopt these products for quick turnover. Manufacturers respond by designing premium disposable visualization chips. Cost-management teams evaluate lifecycle savings from reduced repairs. Demand grows in regions with strict infection-control policies.
- For instance, Trice Medical’s mi-eye 2 is a fully disposable, single-use in-office arthroscopy system that provides real-time visualization through an integrated camera and light source. It removes the need for reprocessing reusable scopes and supports rapid diagnostic assessments within orthopedic clinics.
Increased Use of Digital Workflow Platforms That Support Data Capture and Remote Collaboration
Digital platforms gain traction in the Arthroscopy Devices Market due to rising interest in connected surgery. Hospitals deploy solutions that capture intraoperative data for training and auditing. It improves communication between surgeons and support teams. Remote viewing functions help specialists guide procedures across locations. Recorded footage supports skill development for young clinicians. AI-supported software offers automated tagging of key surgical events. Clinical teams store case data for comparative planning. Adoption grows in advanced centers with strong digital infrastructures.
Wider Movement Toward Energy-Efficient Devices and Environmentally Conscious Surgical Technologies
Sustainability trends shape procurement decisions across orthopedic departments. Many hospitals evaluate devices with lower energy footprints. It supports long-term cost reduction goals across large facilities. Manufacturers redesign pumps and shavers for improved efficiency. Packaging reductions become a priority across supply chains. Hospitals also pursue reusable components with longer life cycles. Environmental audits push for low-waste device models. Sustainable procurement standards influence contract terms in several regions. This trend encourages innovation across arthroscopy developers.
- For instance, Smith & Nephew’s LENS Surgical Imaging System uses a high-performance LED light source with a verified 30,000-hour lifespan, offering a durable and energy-efficient alternative to traditional xenon lamps. The system supports 4K UHD imaging within a compact 3-in-1 control unit and reduces downtime by eliminating frequent bulb replacements.
Arthroscopy Devices Market Challenges Analysis:
High Capital Costs, Complex Training Needs, and Technology Gaps Across Expanding Healthcare Systems
The Arthroscopy Devices Market faces challenges linked to high upfront costs for imaging stacks and powered instruments. Smaller facilities struggle with procurement budgets. It limits access to advanced platforms in many regions. Surgeons need extensive training to achieve mastery with new tools. Operating room teams require time to adjust to upgraded workflows. Limited staff availability slows training cycles in crowded hospitals. Technology gaps remain between high-income and emerging regions. Some providers delay upgrades due to budget cycles and procurement hurdles.
Regulatory Constraints, Sterility Concerns, and Limited Device Standardization Across Diverse Surgical Environments
Regulatory variations impose hurdles on global device launches. The Arthroscopy Devices Market encounters delays due to approval timelines in several countries. It creates inconsistencies in technology availability across regions. Sterility assurance remains difficult in centers with limited reprocessing capacity. Variation in device tray designs complicates standard operating protocols. Surgeons often face compatibility issues between legacy and upgraded systems. Procurement teams struggle to balance cost and performance needs. Environmental concerns also push hospitals to reconsider high-waste devices.
Arthroscopy Devices Market Opportunities:
Growing Demand for Early Joint Preservation, Outpatient Expansion, and Digital Integration Across Orthopedic Programs
The Arthroscopy Devices Market benefits from rising demand for early joint care pathways. Patients seek faster interventions that prevent joint deterioration. It supports growth across outpatient orthopedic networks. Hospitals adopt digital platforms to guide post-operative care. Developers introduce software that improves alignment planning. Surgeons pursue tools that handle complex tasks with greater control. Sports medicine units expand capacity to treat younger populations. New procurement cycles open opportunities for bundled imaging and instrumentation upgrades.
Rising Innovation in Disposable Systems, Robotics-Assisted Modules, and Smart Visualization Tools
Manufacturers gain opportunities by advancing disposable product lines and robotics modules. The Arthroscopy Devices Market gains momentum from interest in smart visualization systems. It drives demand for devices that offer automated clarity control. Hospitals evaluate hybrid reusable-disposable mixes for cost balance. AI-supported imaging upgrades enhance precision during difficult procedures. Robotics development pipelines attract investor attention. Providers consider these technologies to improve consistency across surgeons. Growth potential strengthens across technologically progressive regions.
Arthroscopy Devices Market Segmentation Analysis:
By Product Type
The Arthroscopy Devices Market expands through strong demand across key product categories that support precision-driven orthopedic procedures. Arthroscopes lead usage due to their central role in diagnosis and treatment, supported by steady upgrades in optical quality. Shavers gain traction in high-volume centers that require efficient tissue resection tools. Fluid management systems hold vital importance because they maintain joint visibility and stable pressure control. Implants see rising adoption with complex ligament repair cases. Visualization systems benefit from growing interest in 4K and 3D clarity. Radiofrequency systems secure steady demand for controlled tissue sculpting during surgical repair.
- For instance, the Smith & Nephew WEREWOLF Coblation System uses plasma-based radiofrequency technology designed to remove soft tissue with controlled thermal spread, helping protect surrounding structures during arthroscopy. The CrossFlow Integrated Arthroscopy Pump complements this by delivering automated fluid management that maintains consistent intra-articular pressure for clear joint visualization.
By Application
Knee procedures drive high utilization across the Arthroscopy Devices Market because they represent the largest share of sports injuries and degenerative conditions. Shoulder and elbow interventions grow due to expanding athletic treatment volumes. It supports consistent procurement of tools that handle delicate soft-tissue repair. Hip arthroscopy adoption rises as surgeons broaden indications for early joint preservation. Spine applications gain attention in specialized centers that integrate minimally invasive workflows. The others segment includes ankle and wrist procedures that gain adoption in orthopedic and trauma care settings.
By End User
Hospitals dominate usage due to higher patient inflow, wider case complexity, and broader access to advanced imaging systems. Large orthopedic departments procure integrated towers to support heavy procedural loads. Ambulatory surgical centers and clinics record faster growth through rising preference for outpatient orthopedic procedures. It encourages investment in compact, portable, and standardized arthroscopy systems that support efficient scheduling and shorter recovery timelines. These centers strengthen market expansion through steady procedure turnover and streamlined workflows.
- For instance, the Arthrex SynergyUHD4 4K imaging system is engineered for the ASC environment through a 4-in-1 console that combines a 4K camera, LED light source, image management platform, and connectivity functions in a single compact unit. Its integrated design reduces equipment footprint and streamlines setup in smaller outpatient operating suites. The system supports efficient workflows by consolidating multiple imaging components into one platform.
Segmentation:
By Product Type
- Arthroscopes
- Shavers
- Fluid Management Systems
- Implants
- Visualization Systems
- Radiofrequency Systems
By Application
- Knee
- Shoulder/Elbow
- Hip
- Spine
- Others
By End User
- Hospitals
- Ambulatory Surgical Centers/Clinics
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The Arthroscopy Devices Market secures its largest share in North America, holding around 40% of global revenue. High procedure volumes, strong reimbursement frameworks, and broad adoption of minimally invasive orthopedic techniques support steady growth. Hospitals invest in advanced visualization platforms that improve diagnostic clarity and surgical precision. It benefits from a mature provider network and strong presence of leading manufacturers. Sports injury rates remain high, pushing continuous demand for arthroscopy tools across major centers. Ambulatory surgical facilities expand their arthroscopy capabilities, strengthening market penetration across the United States and Canada.
Europe
Europe accounts for about 30% of the global Arthroscopy Devices Market and records consistent adoption across established orthopedic systems. Hospitals prioritize technology upgrades that support efficient workflows and improved patient outcomes. It sees rising demand from countries with aging populations that experience higher joint degeneration rates. Sports medicine programs expand across Germany, France, and the UK, pushing wider use of visualization and fluid management systems. Procurement teams evaluate integrated towers that meet regional safety and sterility standards. Clinics and day-care centers gain traction, contributing to broader market access across Western and Northern Europe.
Asia-Pacific, Latin America, and Middle East & Africa
Asia-Pacific holds roughly 20% of the market and grows at the fastest pace due to expanding healthcare infrastructure and increasing investments in orthopedic services. Rising sports participation and growing awareness of early joint treatment support higher adoption. Latin America represents around 6% of the Arthroscopy Devices Market, driven by modernization efforts in Brazil, Mexico, and Argentina. It gains momentum through rising private hospital expansions and improved insurance coverage. The Middle East & Africa contributes about 4%, supported by rising demand in Gulf countries and gradual upgrades across public hospitals. Investments in training and modern equipment strengthen long-term potential across emerging economies.
Key Player Analysis:
- Arthrex, Inc.
- Smith & Nephew Plc
- Stryker Corporation
- Johnson & Johnson (DePuy Synthes)
- CONMED Corporation
- KARL STORZ GmbH & Co. KG
- Medtronic Plc
- Zimmer Biomet Holdings
- Olympus Corporation
Competitive Analysis:
The Arthroscopy Devices Market remains highly competitive, with major companies expanding portfolios through innovation, strategic partnerships, and product enhancements. Leading players focus on advanced visualization platforms, ergonomic handheld tools, and disposable systems that support faster workflows. It benefits from strong R&D pipelines across established brands that aim to improve clinical precision and safety. Companies strengthen market positions by integrating imaging, energy devices, and fluid management into unified surgical systems. Rising adoption of outpatient procedures pushes firms to design compact and portable platforms. Competitive intensity increases as global manufacturers target growth in Asia-Pacific and Latin America. Continuous innovation shapes product differentiation across core segments.
Recent Developments:
- In January 2026, Smith & Nephew Plc completed the $450 million acquisition of Integrity Orthopaedics, integrating the innovative Tendon Seam™ system into its portfolio. This disruptive rotator cuff repair technology is designed to reduce re-tear rates and improve patient outcomes compared to the current standard of care, further strengthening the company's leading position in the sports medicine market.
- In December 2025, Medtronic Plc collaborated with Symbiosis to launch "The TechKnow Verse," a next-generation cadaveric training and surgical simulation hub. This initiative is designed to advance surgeon proficiency in minimally invasive techniques, supporting the broader adoption of Medtronic's arthroscopic and orthopedic diagnostic technologies.
- In September 2025, Arthrex, Inc. announced the successful completion of the first surgical case using its NanoNeedle™ Scope 2.0, a next-generation visualization system for minimally invasive procedures. This follows the July 2025 FDA clearance of the NanoScope™ System for pediatric use in orthopedic and laparoscopic procedures and the June 2025 launch of the Synergy Power™ system, a versatile battery-powered instrument for sports medicine and trauma.
- In January 2025, Stryker Corporation entered into a definitive agreement to acquire Inari Medical, Inc. for approximately $4.9 billion, a deal that closed in February 2025 to significantly expand its vascular and neurotechnology offerings. Additionally, in September 2025, Stryker launched its next-generation 1788 advanced surgical camera in new global markets, providing vibrant 4K high-resolution imaging and enhanced fluorescence capabilities for detailed anatomical visualization.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Application, and End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising adoption of minimally invasive orthopedic surgery strengthens long-term growth, supported by higher patient preference for faster recovery and improved joint preservation outcomes across diverse clinical settings.
- Advancements in HD, 3D, and chip-on-tip visualization systems improve surgical precision, guiding wider use of enhanced optics in complex procedures performed in high-volume orthopedic centers.
- Outpatient and ambulatory care facilities expand their role in arthroscopy delivery, driven by shorter procedure times, reduced hospital stays, and strong investments in portable surgical platforms.
- Disposable arthroscopy instruments gain broader acceptance due to improved sterility control, predictable performance, and reduced reprocessing constraints in busy clinical environments.
- Robotics-enabled arthroscopy and navigation modules move closer to mainstream adoption, offering enhanced accuracy in joint repair and greater consistency in technique across surgical teams.
- Rising global sports participation and increased injury incidence push steady demand for joint reconstruction and soft-tissue repair tools across both developed and emerging regions.
- AI-supported imaging, automated tissue recognition, and digital case-planning platforms integrate into orthopedic practices, shaping a new phase of data-driven arthroscopy workflows.
- Hospitals invest in unified surgical towers and integrated control systems that streamline operating room functions, strengthen efficiency, and reduce equipment redundancy.
- Emerging economies accelerate procurement of advanced arthroscopy systems due to expanding orthopedic training programs, growing private hospital investments, and rising medical tourism.
- Sustainability-driven design improvements influence device selection, with providers prioritizing energy-efficient consoles, optimized packaging, and extended-life reusable components.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Procedure Volumes and Minimally Invasive Demand
Increasing cases of sports injuries, osteoarthritis, and trauma-related joint issues are driving higher adoption of arthroscopy devices, as surgeons and patients prefer minimally invasive procedures that reduce complications and speed up recovery.
Advancements in Imaging and Visualization Platforms
Continuous innovation in 4K, 3D, and chip-on-tip imaging systems enhances diagnostic accuracy and surgical precision, encouraging hospitals and clinics to upgrade to advanced arthroscopy platforms.
Expansion of Outpatient and Ambulatory Care
The shift toward day-care orthopedic procedures and the growth of ambulatory surgical centers support higher device utilization, as these settings require compact, efficient, and integrated arthroscopy systems for faster patient turnover.
Growing Adoption of Disposable and Energy-Efficient Devices
Hospitals and high-volume centers are increasingly using disposable arthroscopy instruments to improve sterility and workflow efficiency, while sustainability concerns drive demand for energy-efficient and long-life devices.
Healthcare Infrastructure Modernization in Emerging Markets
Rising investments in healthcare, expanding orthopedic training, and increased medical tourism in Asia Pacific, Latin America, and the Middle East & Africa are accelerating the adoption of advanced arthroscopy devices in these regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Arthroscopy Devices Market, and what is its projected size in 2032?
t what Compound Annual Growth Rate is the Arthroscopy Devices Market projected to grow between 2024 and 2032?
Which Arthroscopy Devices Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Arthroscopy Devices Market?
Who are the leading companies in the Arthroscopy Devices Market?
Which region commanded the largest share of the Arthroscopy Devices Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals
- 1.2.2 Ambulatory Surgical Centers/Clinics
- 1.3 By Application
- 1.3.1 Knee
- 1.3.2 Shoulder/Elbow
- 1.3.3 Hip
- 1.3.4 Spine
- 1.3.5 Others
- 1.4 By Product Type
- 1.4.1 Arthroscopes
- 1.4.2 Shavers
- 1.4.3 Fluid Management Systems
- 1.4.4 Implants
- 1.4.5 Visualization Systems
- 1.4.6 Radiofrequency Systems
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1673.66 million → 2032: USD 2553 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Arthroscopy Devices Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Arthroscopy Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Arthroscopy Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Arthroscopy Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Arthroscopy Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Arthroscopy Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Arthroscopy Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Arthroscopy Devices Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1673.66 million → 2032: USD 2553 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Arthroscopy Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Ambulatory Surgical Centers/Clinics
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Knee
- 12.4.7.2 Shoulder/Elbow
- 12.4.7.3 Hip
- 12.4.7.4 Spine
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Arthroscopes
- 12.5.7.2 Shavers
- 12.5.7.3 Fluid Management Systems
- 12.5.7.4 Implants
- 12.5.7.5 Visualization Systems
- 12.5.7.6 Radiofrequency Systems
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Arthroscopy Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Arthroscopy Devices Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Arthroscopy Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Arthroscopy Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Arthrex, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Smith & Nephew Plc
- 18.4 Stryker Corporation
- 18.5 Johnson & Johnson (DePuy Synthes)
- 18.6 CONMED Corporation
- 18.7 KARL STORZ GmbH & Co. KG
- 18.8 Medtronic Plc
- 18.9 Zimmer Biomet Holdings
- 18.10 Olympus Corporation
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

