
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Carnauba Wax Market Size 2024 | USD 292 million |
| Carnauba Wax Market, CAGR | 2.95% |
| Carnauba Wax Market Size 2032 | USD 368 million |
Market Overview:
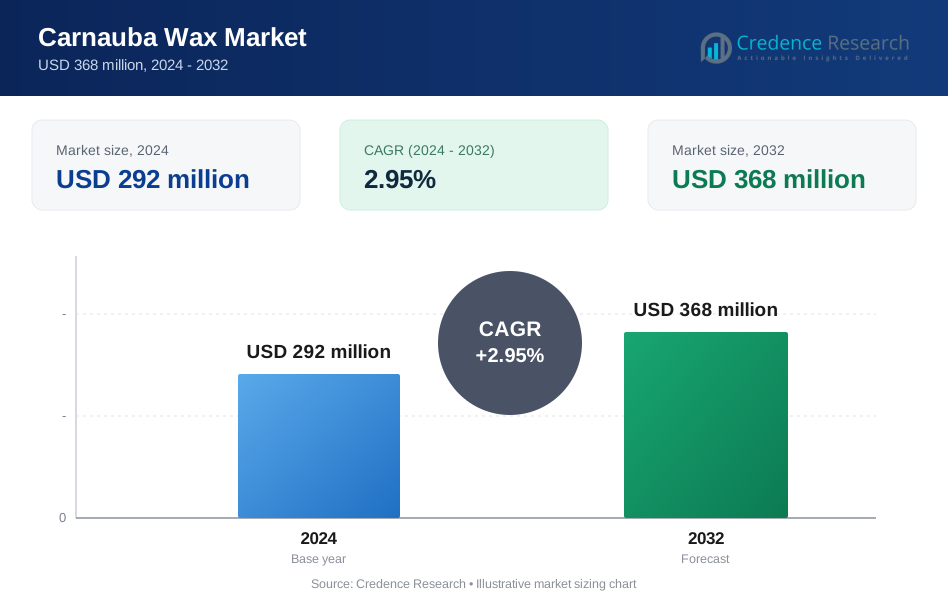
The Carnauba wax market is projected to grow from USD 292 million in 2024 to an estimated USD 368 million by 2032, with a compound annual growth rate (CAGR) of 2.95% from 2024 to 2032.
Key drivers behind the carnauba wax market's expansion include increasing consumer awareness of natural and plant-based ingredients, especially in cosmetics and personal care products. Its hypoallergenic and non-toxic properties make it ideal for use in lipsticks, mascaras, and skincare formulations. The food industry uses carnauba wax as a safe, edible coating for candies, fruits, and baked goods, helping preserve freshness and enhance appearance. In the automotive sector, carnauba wax remains a preferred choice for high-performance polishes and protective coatings, with growing demand from premium vehicle owners and detailing professionals. Pharmaceutical companies use it as a tablet-coating agent to control drug release and improve stability. Moreover, the rise in clean-label product development across all these industries is driving manufacturers to integrate carnauba wax into their formulations, resulting in higher demand and improved market visibility.
Regionally, North America accounts for approximately 31–34% of global market revenue, driven by strong automotive, food, and cosmetics industries that demand high-quality, sustainable ingredients. The U.S. remains a leading consumer, backed by innovation in product formulation and advanced distribution networks. Europe also holds a significant share, supported by regulatory support for natural ingredients and well-established personal care and food sectors. Asia-Pacific is the fastest-growing region, currently contributing 33–35% of the market, fueled by expanding middle-class populations, increasing disposable incomes, and high consumption of processed foods and personal care products in China, India, and Southeast Asia. Latin America plays a dual role as both a major production hub—primarily Brazil, the world’s largest carnauba wax exporter—and an emerging market for consumption. The Middle East and Africa are gradually expanding their presence, supported by improvements in industrial capacity and growing interest in sustainable materials. The global shift toward natural, functional, and eco-conscious products will continue to shape regional dynamics and overall market expansion.
Market Insights:
- The Carnauba wax market is projected to grow from USD 292 million in 2024 to USD 368 million by 2032, reflecting a CAGR of 2.95%.
- Rising consumer demand for clean-label, plant-based, and biodegradable ingredients is boosting carnauba wax use in cosmetics and personal care products.
- Food and pharmaceutical industries are increasing adoption of carnauba wax for edible coatings and tablet film applications due to its safety and functional properties.
- Automotive detailing products continue to rely on carnauba wax for high-gloss finishes and surface protection, supporting steady industrial demand.
- Supply chain risks remain due to Brazil’s dominance in global production, which exposes the market to climate, labor, and export disruptions.
- Synthetic wax alternatives challenge pricing competitiveness, but carnauba wax retains an edge through sustainability and regulatory approval.
- Asia-Pacific leads growth by volume and value, while North America and Europe maintain stable demand through advanced personal care, food, and automotive sectors.
Market Drivers:
Rising Consumer Preference for Natural and Biodegradable Ingredients:
The global push for safer, eco-friendly, and plant-based ingredients is a major driver of the carnauba wax market. Consumers are actively seeking products that exclude synthetic chemicals and favor natural origins. Carnauba wax fits this preference, offering non-toxic, biodegradable, and hypoallergenic properties suitable for personal care, cosmetics, and food coatings. The market benefits from its widespread approval by food and drug regulatory authorities, which supports its inclusion in clean-label formulations. Demand is particularly strong in skincare, lip care, and confectionery products. The carnauba wax market gains traction as industries align with consumer values emphasizing sustainability and health.
- For instance, the U.S. Food and Drug Administration (FDA) lists carnauba wax as Generally Recognized as Safe (GRAS) for use in food, while the European Food Safety Authority (EFSA) authorizes its use as food additive E903. Tridge, Brazil accounted for 78.08% of global carnauba wax export value in 2024, with $108 million in exports, reflecting its dominance in supplying this natural wax.
Expanding Use in Automotive Care and Surface Protection Products:
Automotive maintenance and detailing products continue to rely on carnauba wax for its ability to deliver a high-gloss finish and strong surface protection. Carnauba wax resists heat, water, and UV radiation, making it ideal for automotive polishes and waxes. With rising demand for premium car care, manufacturers are blending carnauba with synthetic compounds to enhance durability and application ease. Growth in vehicle ownership in emerging markets contributes to broader demand for exterior maintenance products. Both professional detailers and individual consumers favor products featuring natural ingredients for superior results. The carnauba wax market maintains relevance through its proven performance in this specialized application.
- For instance, Turtle Wax, a leading U.S. automotive care company, reports that over 60% of its premium paste waxes contain carnauba as a key ingredient.
Increasing Demand for Functional Coatings in Food and Pharmaceuticals:
The food industry uses carnauba wax extensively as a coating for candies, fruits, and baked goods, where it enhances appearance and extends shelf life. Its edibility and safety approval across global markets make it a dependable ingredient for large-scale food production. The pharmaceutical sector also adopts it for tablet coatings to control release rates and improve stability. Nutraceuticals and dietary supplements use carnauba wax in capsule formulations to meet growing demand for plant-based, allergen-free products. The carnauba wax market sees growing volumes in these sectors driven by functional benefits, regulatory acceptance, and consumer demand for clean ingredients.
Global Shift Toward Sustainable Raw Materials and Ethical Sourcing:
Sustainability concerns influence procurement strategies in multiple industries, with companies committing to ethical sourcing and environmental responsibility. Carnauba wax, harvested from Brazilian palm leaves, supports this shift through renewable sourcing and minimal processing. Brands emphasize ethical and traceable supply chains, encouraging producers to meet international labor and environmental standards. Certifications and responsible harvesting practices are becoming central to purchasing decisions, especially among multinational companies. The carnauba wax market aligns with this trend, offering a material that supports both environmental goals and product performance. It continues to grow as businesses seek low-impact, socially responsible raw materials.
Market Trends:
Rising Demand for Natural and Plant-Based Ingredients Across Industries:
Consumers and manufacturers are increasingly shifting toward natural, plant-derived materials in food, cosmetics, and pharmaceuticals. Carnauba wax, sourced from the Copernicia prunifera palm, meets this demand due to its non-toxic, biodegradable, and hypoallergenic properties. Its application in clean-label cosmetic formulations such as lip balms, mascaras, and skincare products continues to expand. Food producers use it for edible coatings on confectionery, fruits, and bakery products to preserve texture and visual appeal. The carnauba wax market benefits from growing preference for sustainable and renewable raw materials. It aligns with global clean beauty and green packaging movements, positioning itself as a viable alternative to synthetic waxes.
- For instance, Brazil produced approximately 22,000 metric tons of carnauba wax in 2023, supplying over 90% of the world’s demand.
Growth in Automotive Care and Detailing Product Innovations:
The automotive industry remains a key consumer of carnauba wax, particularly in high-end car care products. It provides a glossy, water-resistant finish that enhances vehicle appearance and protects surfaces from weathering. Manufacturers are innovating by blending carnauba wax with polymers and synthetic compounds to improve durability and ease of application. The market sees increased demand from both commercial detailing services and do-it-yourself car care enthusiasts. Expanding vehicle ownership in emerging economies adds to volume growth. The carnauba wax market continues to evolve with these advancements, maintaining relevance in a competitive automotive maintenance segment.
- For instance, According to the International Carwash Association, 65% of U.S. carwashes offer detailing services that include carnauba-based wax applications.
Increasing Adoption in Pharmaceutical and Nutraceutical Coatings:
Pharmaceutical companies use carnauba wax as a coating material in tablets and capsules for controlled release, moisture protection, and product stability. Its compatibility with other excipients and regulatory approval in major markets make it a preferred choice for solid dosage forms. The growing nutraceutical and dietary supplement market further expands its pharmaceutical applications. Consumer interest in plant-based and allergen-free supplements reinforces demand for natural coatings. Manufacturers are optimizing formulations for better shelf life and patient compliance. The carnauba wax market sees growing traction in this segment as producers prioritize functionality and clean-label compliance.
Sustainability and Ethical Sourcing Practices Influencing Procurement Strategies:
Sustainability plays a larger role in product development and sourcing across global industries. Buyers increasingly demand transparency in supply chains, pushing manufacturers to ensure ethical harvesting and traceability of carnauba wax. Certifications like Fair Trade and adherence to biodiversity standards gain importance in supplier selection. The market responds by adopting sustainable harvesting techniques and improving labor practices in producing regions such as Brazil. Brands highlight eco-friendly sourcing in product marketing to appeal to environmentally conscious consumers. The carnauba wax market benefits from this trend by reinforcing its image as a responsible, nature-based raw material.
Market Challenges Analysis:
Supply Chain Disruptions and Dependence on Single-Origin Sourcing:
The carnauba wax market faces a significant challenge due to its dependence on Brazil, which produces over 90% of the global supply. Seasonal harvesting, labor shortages, and environmental factors such as drought or deforestation impact availability and price stability. Disruptions in local infrastructure or export logistics can cause delays and limit global supply, affecting downstream industries. This geographic concentration limits diversification opportunities and exposes buyers to sourcing risks. Producers and buyers must navigate fluctuating raw material costs and unpredictable harvest cycles. The carnauba wax market remains vulnerable to external shocks unless sustainable expansion and multi-origin sourcing strategies are developed.
Price Volatility and Competitive Pressure from Synthetic Alternatives:
Carnauba wax prices fluctuate due to supply constraints, inconsistent yields, and rising labor and compliance costs in producing regions. These dynamics make it difficult for manufacturers to maintain stable pricing for end products. Synthetic and petroleum-based waxes offer lower-cost alternatives with more predictable availability, especially in applications where natural sourcing is not a priority. While demand for natural ingredients is growing, some buyers still opt for cost-effective substitutes when budgets are limited. The carnauba wax market must continuously communicate its performance advantages and sustainability credentials to maintain competitive positioning. Investment in value-added processing and long-term supplier partnerships can help stabilize costs and retain market share.
Market Opportunities:
Rising Demand in Emerging Economies and Untapped Industrial Applications:
The carnauba wax market holds strong growth potential in emerging economies where industrial expansion, rising disposable incomes, and consumer awareness of natural products are accelerating. Rapid development in personal care, food processing, and automotive sectors across Asia-Pacific, Latin America, and parts of Africa creates new demand for multifunctional, plant-based ingredients. Local manufacturers are beginning to adopt carnauba wax for coatings, finishes, and product formulations. Investments in regional distribution and education on application benefits can support deeper market penetration. The carnauba wax market can strengthen its position by offering tailored grades and competitive pricing to suit varying industrial needs.
Innovation in Blended Formulations and High-Performance Alternatives:
Formulation innovation presents a key opportunity for value creation. By combining carnauba wax with other natural or synthetic materials, producers can enhance performance properties such as heat resistance, spreadability, and durability. These blends can appeal to industries seeking improved functionality without compromising sustainability. Niche markets like natural packaging coatings, vegan cosmetics, and biopolymer surface treatments offer room for growth. The carnauba wax market can leverage these trends to develop specialized products that meet evolving regulatory and performance demands. Collaboration with R&D partners and end-use industries can accelerate adoption of next-generation formulations.
Market Segmentation Analysis:
By Product Type
The Carnauba wax market is segmented into Type 1, Type 3, and Type 4 grades. Type 1, the purest form, finds use in pharmaceuticals, premium automotive waxes, and food products. Type 3 dominates market volume due to its versatility across industries. Type 4 serves industrial applications that require lower purity. Purity-based classifications such as cosmetic-grade, food-grade, and technical-grade align with specific regulatory and functional requirements.
- For instance, Purity-based classifications such as cosmetic-grade, food-grade, and technical-grade waxes align with specific regulatory and functional requirements.
By Form
Flakes lead in market share due to ease of storage, handling, and formulation integration. Powder form supports high-speed production and precision blending, making it suitable for large-scale cosmetic and food manufacturing. Paste form caters to concentrated dispersions in specialized industrial and cosmetic uses.
- For instance, Paste form caters to concentrated dispersions in specialized industrial and cosmetic uses, with 12% of surveyed manufacturers in the EU reporting use of carnauba wax paste for specialty applications.
By Application/End-Use Industry
Automotive remains the leading application, accounting for nearly half of global demand due to Carnauba wax's polishing and protective properties. Food and beverages follow, where it acts as a natural coating agent. Personal care and cosmetics use it to enhance product texture and finish. Pharmaceutical applications rely on its coating ability for controlled-release tablets. Other sectors include furniture polishes, industrial coatings, and candles.
Segmentation:
By Product Type
- Type 1 (Purest Grade)
- Type 3
- Type 4
- Purity Grades (Cosmetic-grade, Food-grade, Technical-grade)
By Form
- Flakes
- Powder
- Paste
By Application/End-Use Industry
- Automotive
- Food & Beverages
- Personal Care & Cosmetics
- Pharmaceuticals
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America and Europe Maintain Consistent Demand Through Established End-Use Industries
North America accounts for approximately 31–34% of the global carnauba wax market, driven by demand from automotive, food, and cosmetics industries. The United States leads regional consumption due to strong aftermarket car care culture and rising preference for natural ingredients in personal care. Regulatory support for clean-label food coatings and eco-friendly product development sustains growth across industrial and consumer applications. In Europe, which holds about 28% of global market share, countries such as Germany, France, and the UK demonstrate consistent demand through well-developed confectionery, pharmaceuticals, and skincare sectors. European buyers prioritize certified sourcing and traceability, encouraging suppliers to maintain ethical and sustainable practices. The carnauba wax market continues to perform well in these regions due to its alignment with high-quality standards and functional versatility.
Asia-Pacific Emerges as the Fastest-Growing Region by Volume and Value
Asia-Pacific currently holds around 33–35% of the global carnauba wax market and is projected to grow at the fastest CAGR over the forecast period. Rising disposable income, expanding middle-class populations, and rapid growth in cosmetics, food processing, and automotive sectors support rising demand. China, India, Japan, and Southeast Asian nations represent key growth markets for both import and local processing. Manufacturers are responding by expanding regional distribution networks and offering tailored product grades. Growing demand for natural and sustainable alternatives to petroleum-based materials also drives carnauba wax use in industrial applications such as packaging and polishes. The market in this region benefits from strong consumption trends and increasing interest in renewable raw materials.
Latin America and MEA Present Long-Term Development Potential
Latin America plays a dual role in the carnauba wax market, with Brazil serving as the dominant producer and exporter. While most wax is exported to developed markets, domestic consumption is rising in automotive, packaging, and food sectors. Local initiatives to promote value-added processing and certification compliance are strengthening Brazil’s position as a global supplier. The Middle East and Africa (MEA), holding a smaller market share, are showing gradual growth, supported by rising urbanization and interest in natural ingredients. MEA markets import carnauba wax primarily for cosmetics, food, and niche industrial uses. It shows long-term potential through improved distribution access, industrial investment, and sustainability-driven procurement strategies.
Key Player Analysis:
- Foncepi Comercial Exportadora Ltda (Brazil)
- Carnauba do Brasil Ltda (Brazil)
- Brasil Ceras (Brazil)
- Tropical Ceras Do Brasil Ltda. (Brazil)
- Pontes Industria de Cera Ltda. (Brazil)
- Strahl & Pitsch, Inc. (USA)
- Kahl GmbH & Co. KG (Germany)
- Norevo GmbH (Germany)
- Koster Keunen (Netherlands)
- The International Group, Inc. (Canada)
Competitive Analysis:
The carnauba wax market features a moderately consolidated competitive landscape, with a few key producers based in Brazil dominating global supply. Companies such as Foncepi, Carnauba do Brasil, Pontes Indústria de Cera, and Brasil Ceras lead the market through strong control over raw material sourcing and processing capabilities. These firms maintain strategic export relationships and offer product grades tailored to automotive, food, pharmaceutical, and cosmetic applications. International distributors and specialty chemical companies act as intermediaries in major consumer markets, focusing on regulatory compliance and application-specific formulations. The carnauba wax market rewards players that ensure consistent quality, ethical sourcing, and scalable logistics. Competitive differentiation often depends on traceability, product purity, and alignment with sustainability certifications. Manufacturers that invest in refining processes, diversify their product lines, and maintain long-term partnerships with end-use industries secure greater market presence and customer loyalty.
Recent Developments:
- In December 2024, Brasil Ceras announced significant progress in improving the carnauba supply chain, with a focus on traceability, worker safety, human rights, and sustainability. The company reaffirmed its commitment to building a more ethical and transparent industry, and looks forward to further strengthening partnerships and driving positive change in 2025.
- In 2024, Tropical Ceras Do Brasil Ltda. continued to expand its export operations and supply chain partnerships, focusing on meeting the rising demand for natural and sustainable carnauba wax in the cosmetics and food industries. The company also invested in new refining technologies to improve wax purity and application efficiency.
- In 2025, Strahl & Pitsch, Inc. reinforced its commitment to sustainability and innovation by expanding its range of natural and specialty wax blends. The company has been actively developing new formulations to address industry trends and performance requirements, particularly for the cosmetics and pharmaceutical sectors. Strahl & Pitsch’s efforts to foster positive partnerships and provide customized solutions have been central to its recent activities.
- In March 2025, Koster Keunen launched a new product, Kester Wax K-70P, at the in-cosmetics Global show in Amsterdam. This innovative plasticizer, derived from rice wax, offers new texture options for clean cosmetics and aligns with the trend toward sustainable and natural ingredients. The company also showcased its latest ingredient innovations and example formulations for personal care brands at the event
Market Concentration & Characteristics:
The carnauba wax market is moderately concentrated, with production heavily reliant on Brazil, which supplies over 90% of the global output. A small number of vertically integrated Brazilian companies control harvesting, processing, and export, giving them strong influence over pricing and availability. The market features a broad base of end users across cosmetics, food, automotive, and pharmaceuticals, each requiring specific product grades and regulatory compliance. It prioritizes natural origin, biodegradability, and multifunctional performance, which align with global trends toward sustainability. Market dynamics are shaped by seasonal harvests, ethical sourcing standards, and increasing demand for traceability. The carnauba wax market remains supply-sensitive but benefits from stable demand across developed and emerging economies.
Report Coverage:
The research report offers an in-depth analysis based on By Product Type, By Form, By Application/End-Use Industry and By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Global demand for natural waxes will continue to rise, supporting consistent growth in carnauba wax consumption.
- Cosmetic and personal care industries will expand usage driven by clean-label and vegan product trends.
- Food manufacturers will increase adoption for edible coatings amid growing preference for plant-based ingredients.
- Automotive care products will retain carnauba wax for its premium finish and protective qualities.
- Pharmaceutical and nutraceutical sectors will boost demand through use in controlled-release and allergen-free formulations.
- Emerging markets in Asia-Pacific and Latin America will offer strong growth potential across all application segments.
- Innovation in wax blends and functional coatings will open new opportunities in packaging and industrial uses.
- Sustainability certifications and traceable sourcing will become key factors in supplier selection.
- Volatility in raw material supply may lead to investment in value-added processing and supply chain diversification.
- Strategic partnerships between producers and end-use industries will strengthen global distribution and product development.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Carnauba wax market?
What factors are driving the growth of the Carnauba wax market?
What are some challenges faced by the Carnauba wax market?
Who are the major players in the Carnauba wax market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Carnauba Wax Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Carnauba Wax Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 292 million → 2032: USD 368 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Carnauba Wax Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Carnauba Wax Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Carnauba Wax Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Carnauba Wax Market Drivers
- 3.3 Carnauba Wax Market Restraints & Challenges
- 3.4 Carnauba Wax Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Carnauba Wax Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Carnauba Wax Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Carnauba Wax category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Carnauba Wax Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Carnauba Wax Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Carnauba Wax market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Carnauba Wax Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Carnauba Wax Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Carnauba Wax Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Carnauba Wax (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Carnauba Wax Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Carnauba Wax Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Carnauba Wax Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Carnauba Wax Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Carnauba Wax Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Carnauba Wax Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Carnauba Wax Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Carnauba Wax Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Carnauba Wax Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
