
Market Overview:
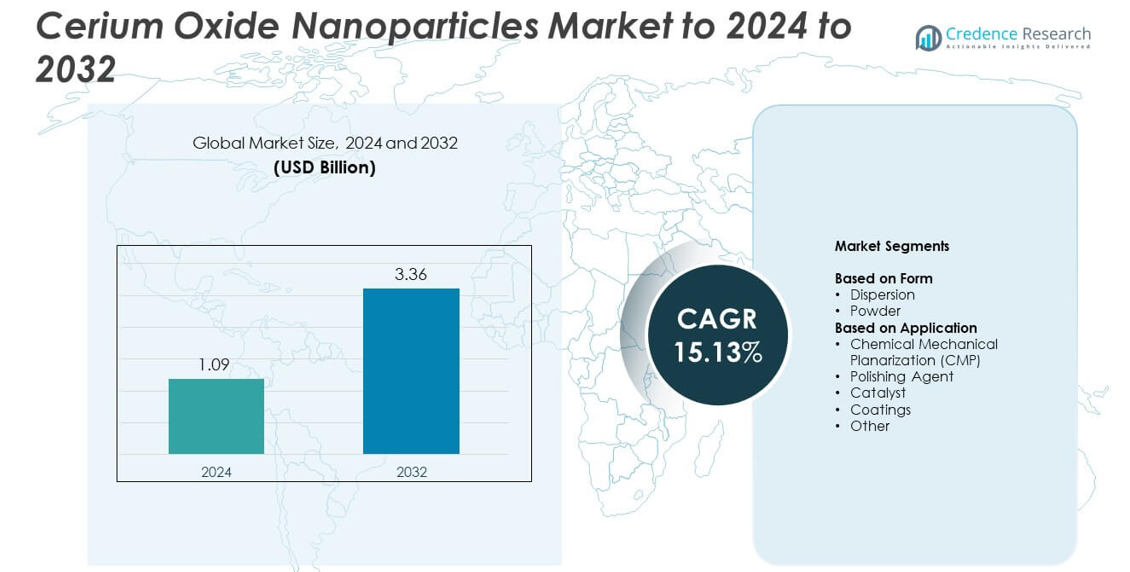
Cerium Oxide Nanoparticles Market size was valued at USD 1.09 billion in 2024 and is anticipated to reach USD 3.36 billion by 2032, at a CAGR of 15.13% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Cerium Oxide Nanoparticles Market Size 2024 | USD 1.09 billion |
| Cerium Oxide Nanoparticles Market, CAGR | 15.13% |
| Cerium Oxide Nanoparticles Market Size 2032 | USD 3.36 billion |
Nanoshel, Platonic Nanotec, Skyspring Nanomaterials, Nanoe, Stem Chemicals, Inframat, Plasmachem, Nanografi Nano Technology, Meliorum Technologies, Nanophase Technologies, American Elements, and Cerion Nanoparticles are key participants in the cerium oxide nanoparticles market. North America holds the leading regional share at approximately 34.6% of the global market. Asia‑Pacific follows closely with roughly 30% share, thanks to rapid electronics and semiconductor growth. Europe occupies about 25% share, driven by stringent emission regulations and advanced industrial applications.
Market Insights
- The global cerium oxide nanoparticles market was valued at USD 1.09 billion in 2024 and is expected to reach USD 3.36 billion by 2032, growing at a CAGR of 15.13% during the forecast period.
- Key drivers include increasing demand from semiconductor, automotive, and healthcare sectors, along with stricter emission regulations and the growing need for high-performance polishing and catalyst applications.
- Market trends show a growing focus on R&D for high-purity nanoceria, tailored nanoparticle sizes, and expanding applications in energy storage and environmental systems.
- Competitive analysis reveals significant investments in scaling up production capabilities and expanding application portfolios, with firms vying for market share in coatings, optics, and biomedicine.
- North America leads the market with approximately 34.6% share, followed by Asia-Pacific at 30% and Europe at 25%, driven by rapid industrial growth and regulatory frameworks across regions.
Market Segmentation Analysis:
By Form
Dispersion leads this segment with more than 65 % share in 2023. Its dominance comes from strong use in coatings, biomedical fluids and electronic materials where uniform particle distribution is essential. Growth continues as manufacturers adopt dispersion formats for better stability, easy blending and high performance in functional films and surface-engineering tasks. Powder remains important for large-volume industries such as polishing, glass processing and catalysis. Demand for the powder form grows because it is easy to transport, store and use in high-temperature or bulk-processing environments.
- For instance, American Elements' catalog includes more than 35,000 products, making it a very large, globally recognized manufacturer and supplier of advanced materials, chemicals, and metals.
By Application
Chemical Mechanical Planarization holds the leading position with over 38 % share due to its critical role in semiconductor wafer finishing. Growth rises as chip production expands and device geometries shrink, increasing demand for high-precision nanoceria slurries. Polishing agents also form a major share as nanoceria offers smooth finishing for glass, ceramics and optical parts. Catalyst and coating uses continue to increase with tighter emission norms, stronger surface-protection needs and the rising adoption of high-performance engineered materials.
- For instance, CMC Materials, now part of Entegris, expanded its manufacturing and R&D facilities in Singapore to better serve Asian foundries' demand for planarization consumables as early as fiscal year 2011, with the expansion involving an additional 30,000 square feet of manufacturing space and a total capital investment of approximately $30 million at that time.
Key Growth Drivers
Rising Demand in Semiconductor Manufacturing
Growth accelerates as cerium oxide nanoparticles play a vital role in Chemical Mechanical Planarization. The semiconductor sector needs high-precision polishing materials for wafers, which increases adoption of nanoceria-based CMP slurries. Expansion of fabrication plants and growth in advanced chip architectures strengthen demand. Rising investment in miniaturized electronics further boosts consumption. This driver remains the most influential because semiconductor output strongly determines long-term volume requirements in this market.
- For instance, Taiwan Semiconductor Manufacturing Company (TSMC) processed 12.0 million 12-inch equivalent wafers in 2023 (a decrease from 15.3 million in 2022), with each wafer requiring multiple planarization steps and high-volume planarization consumables.
Expansion of High-Performance Polishing Applications
Growth increases as industries rely on cerium oxide nanoparticles for precision polishing of glass, ceramics and optical components. Their ability to deliver scratch-free surfaces supports demand from automotive glazing, display panels and optical devices. The shift toward premium finishing standards in consumer electronics drives higher usage. Rapid adoption of advanced optics, electric vehicle displays and high-clarity lenses reinforces this driver across several industrial sectors.
- For instance, Corning's Specialty Materials segment (which produces Gorilla Glass) delivered approximately flat core sales year over year in 2022, totaling $2.002 billion, despite a dynamic market environment characterized by overall industry declines in the second half of the year. The product has been designed into more than 8 billion devices globally and is used by over 45 major global OEMs (Original Equipment Manufacturers).
Rising Use in Catalysts and Emission Control Systems
Growth strengthens as cerium oxide nanoparticles gain deeper integration in automotive, industrial and environmental catalysts. Their oxygen-storage and redox properties improve reaction efficiency and help meet strict emission norms. Demand rises with expanding vehicle production and tightening global air-quality regulations. Industries also adopt nanoceria for green chemical processes and cleaner industrial operations. This driver gains momentum as sustainability-focused initiatives intensify.
Key Trends and Opportunities
Shift Toward Advanced Coating Applications
A major trend emerges as cerium oxide nanoparticles are adopted in coatings requiring UV resistance, thermal stability and abrasion protection. Automotive and aerospace industries seek coatings that extend component life and reduce maintenance needs. Opportunities grow in high-performance architectural coatings and protective films. Adoption expands as manufacturers move toward durable, eco-aligned coating formulations that improve long-term surface performance.
- For instance, AkzoNobel N.V. reported approximately €10.67 billion in total revenue for 2023, and described its overall volume development for the year as having stabilized despite continuing volatility in some markets.
Growth in Biomedical and Environmental Research
An important trend develops as research institutions explore cerium oxide nanoparticles in drug delivery, antioxidant therapies and environmental remediation. Their redox behaviour supports applications in oxidative stress control and pollutant breakdown. Opportunities expand as healthcare technologies evolve and environmental cleanup projects adopt nanomaterials. This trend gains interest from interdisciplinary research programs and next-generation medical materials developers.
- For instance, the National Institutes of Health (NIH) actively funds a wide variety of nanomedicine research projects, including those focused on cancer, infection, and drug delivery, with 100s of nanomedicines currently in various stages of the clinical process.
Increasing Investment in Nanotechnology Innovation
A strong opportunity rises as global R&D centres push new formulations, improved dispersion stability and high-purity nanoceria. Investments support scalable synthesis methods and more efficient particle engineering. Emerging applications in energy storage, hydrogen production and electronic films open new revenue channels. Market players benefit from a growing shift toward multifunctional nanomaterials with broad industrial usage.
Key Challenges
Stringent Manufacturing and Quality-Control Requirements
A major challenge arises from the need for consistent particle size, purity and dispersion quality. Variations in synthesis processes can affect product performance, limiting adoption in high-precision sectors like semiconductors and optics. Manufacturers face high technical barriers and tight specification demands from end users. Meeting these standards increases production cost and requires advanced process controls.
Environmental and Health Safety Concerns
Another challenge emerges due to uncertainties surrounding long-term environmental impact and workforce exposure. Handling and disposal regulations continue to evolve, pushing companies to adopt safer production and transport practices. Compliance adds operational burdens for producers. Concerns over nanoparticle toxicity in biological and ecological systems create cautious adoption in some sectors and slow regulatory approvals.
Regional Analysis
North America
North America holds a significant share of approximately 34.6% in the global cerium oxide nanoparticles market as of 2024. The region benefits from strong demand across industries such as automotive, semiconductor manufacturing, and healthcare. Key drivers include stringent emission control standards favoring cerium oxide use in catalytic converters and industrial applications. Additionally, high levels of R&D investment in nanotechnology and advanced materials fuel market growth. The U.S. remains a dominant player, with expanding applications in energy storage systems, microelectronics, and nanomedicine, offering a positive long-term outlook for the region.
Europe
Europe represents around 25% of the global cerium oxide nanoparticles market in 2024, driven by a focus on environmental regulations and high-tech industries. Strict emission control policies and the automotive sector’s reliance on cerium oxide for catalytic converters significantly contribute to market share. Expanding applications in semiconductors, optics, and medical fields further boost growth. Germany, France, and the UK are key contributors with their advanced R&D capabilities in nanomaterials. However, regulatory complexities and economic slowdowns may pose challenges to further growth potential in some sectors.
Asia Pacific
Asia Pacific holds the largest share of approximately 30% in the cerium oxide nanoparticles market as of 2024, and is expected to see the fastest growth. The region benefits from rapid industrialization, particularly in China, India, Japan, and South Korea, which are key markets for semiconductor production, electronics manufacturing, and automotive sectors. Government initiatives supporting nanotechnology, sustainable manufacturing, and renewable energy technologies contribute to strong demand. With its vast manufacturing base, Asia Pacific continues to be a crucial market for cerium oxide nanoparticles.
Latin America
Latin America holds a smaller market share of around 5-10% in 2024 but presents emerging growth opportunities. Key countries like Brazil and Mexico are expanding their automotive and electronics sectors, creating demand for cerium oxide nanoparticles, especially in catalytic converters and coatings. Regulatory pressures for cleaner technologies also stimulate demand. While the market potential is increasing, challenges such as limited local manufacturing capabilities and reliance on imports restrain rapid growth. However, regional investments in infrastructure and technology innovation provide a promising outlook for cerium oxide nanoparticles in the medium term.
Middle East & Africa
The Middle East & Africa region holds less than 5% of the global cerium oxide nanoparticles market in 2024. Growth is gradual, driven by a focus on energy-related applications such as energy storage and catalysts in oil refining. GCC countries, particularly Saudi Arabia and the UAE, are increasing investments in advanced materials, spurring demand for cerium oxide. Despite challenges such as economic volatility, limited industrial infrastructure, and lower manufacturing activity compared to other regions, the region presents potential for niche applications, especially in energy and coatings.
Market Segmentations:
By Form
- Dispersion
- Powder
By Application
- Chemical Mechanical Planarization (CMP)
- Polishing Agent
- Catalyst
- Coatings
- Other
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Nanoshel, Platonic Nanotec, Skyspring Nanomaterials, Nanoe, Stem Chemicals, Inframat, Plasmachem, Nanografi Nano Technology, Meliorum Technologies, Nanophase Technologies, American Elements and Cerion Nanoparticles operate in a competitive landscape shaped by product quality, nanoparticle purity and application-specific performance. Companies focus on improving controlled particle size distribution, higher dispersion stability and advanced surface modifications to meet semiconductor, catalyst and polishing requirements. Many producers invest in scaling synthesis methods to strengthen supply reliability for high-volume industrial users. Competition also intensifies as firms expand application portfolios across coatings, optics and environmental systems. Strategic moves include forming partnerships with research institutions, enhancing customer-specific formulations and developing next-generation nanoceria grades that support performance-driven markets. Regional expansion and deeper integration with end-use sectors further influence competitive positioning.
Key Player Analysis
- Nanoshel
- Platonic Nanotec
- Skyspring Nanomaterials
- Nanoe
- Stem Chemicals
- Inframat
- Plasmachem
- Nanografi Nano Technology
- Meliorum Technologies
- Nanophase Technologies
- American Elements
- Cerion Nanoparticles
Recent Developments
- In 2025, Nanografi Nano Technology (as of July 2025) offers high-purity cerium oxide nanoparticles with sizes ranging from 8 to 28 nm and purity of 99.975%.
- In 2025, Nanophase Technologies rebranded as Solésence, Inc. and continued to leverage its patented technology for surface modification of nanomaterials.
- In 2023, Nanoe, a French company specializing in high-purity ceramic powders, focused on scaling up the production of its Zetamix line to cater to diverse industrial applications.
Report Coverage
The research report offers an in-depth analysis based on Form, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Market demand will expand as semiconductor wafer dimensions shrink and CMP processes intensify.
- Nanoceria adoption will rise in advanced polishing applications for glass, optics, and ceramic surfaces.
- Environmental regulations will drive increased use of cerium oxide nanoparticles in emission‑control catalysts.
- Coating formulations incorporating nanoceria will grow as industries seek durable, high‑performance surfaces.
- Asia‑Pacific will lead growth due to expanding electronics, automotive and renewable‑energy manufacturing.
- R&D investments will accelerate new nanoceria-based materials for biomedicine and environmental remediation.
- Production costs will decline with improved synthesis and scale‑up, boosting wider commercial use.
- Challenges around safety and regulations will promote standardized handling and certification of nanoparticle products.
- Strategic partnerships and collaborations will become more common between materials producers and end‑use equipment manufacturers.
- Market differentiation will increase as manufacturers focus on tailored nanoparticle sizes, shapes and surface treatments.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand in Semiconductor Manufacturing
Cerium oxide nanoparticles are essential for Chemical Mechanical Planarization (CMP) in semiconductor wafer production, where their high-precision polishing capabilities are critical as device geometries shrink. The expansion of fabrication plants and advanced chip architectures is driving increased adoption of nanoceria-based CMP slurries.
Expansion of High-Performance Polishing Applications
Industries such as automotive, optics, and electronics increasingly rely on cerium oxide nanoparticles for precision polishing of glass, ceramics, and optical components. Their ability to deliver scratch-free, high-clarity surfaces supports demand in premium consumer electronics and advanced optical devices.
Rising Use in Catalysts and Emission Control Systems
Cerium oxide nanoparticles are being integrated into automotive and industrial catalysts due to their oxygen-storage and redox properties, which enhance reaction efficiency and help meet stringent emission regulations. This is particularly important as global air-quality standards tighten and vehicle production expands.
Shift Toward Advanced Coating Applications
The adoption of cerium oxide nanoparticles in coatings is growing, especially in automotive and aerospace sectors, due to their UV resistance, thermal stability, and abrasion protection. This trend is driven by the need for durable, high-performance surfaces and eco-friendly formulations.
Growth in Biomedical and Environmental Research
Research institutions are exploring cerium oxide nanoparticles for drug delivery, antioxidant therapies, and environmental remediation, leveraging their redox behavior for oxidative stress control and pollutant breakdown. This opens new opportunities in healthcare technologies and environmental cleanup projects.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Cerium Oxide Nanoparticle Market?
At what Compound Annual Growth Rate is the Cerium Oxide Nanoparticles Market projected to grow between 2025 and 2032?
What factors are driving the growth of the Cerium Oxide Nanoparticle Market?
What are the key segments within the Cerium Oxide Nanoparticle Market?
What are some challenges faced by the Cerium Oxide Nanoparticle Market?
Who are the major players in the Cerium Oxide Nanoparticle Market?
Which region commanded the largest share of the Cerium Oxide Nanoparticles Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Form
- 1.2.1 Dispersion
- 1.2.2 Powder
- 1.3 By Application
- 1.3.1 Chemical Mechanical Planarization (CMP)
- 1.3.2 Polishing Agent
- 1.3.3 Catalyst
- 1.3.4 Coatings
- 1.3.5 Other
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1.09 billion → 2032: USD 3.36 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Cerium Oxide Nanoparticle Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Cerium Oxide Nanoparticle Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Cerium Oxide Nanoparticle Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Cerium Oxide Nanoparticle Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Cerium Oxide Nanoparticle Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Cerium Oxide Nanoparticle Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Cerium Oxide Nanoparticle Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Cerium Oxide Nanoparticle Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1.09 billion → 2032: USD 3.36 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Cerium Oxide Nanoparticle Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Form - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Dispersion
- 12.3.7.2 Powder
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Chemical Mechanical Planarization (CMP)
- 12.4.7.2 Polishing Agent
- 12.4.7.3 Catalyst
- 12.4.7.4 Coatings
- 12.4.7.5 Other
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Cerium Oxide Nanoparticle End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Cerium Oxide Nanoparticle Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Cerium Oxide Nanoparticle Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Cerium Oxide Nanoparticle Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Nanoshel
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Platonic Nanotec
- 18.4 Skyspring Nanomaterials
- 18.5 Nanoe
- 18.6 Stem Chemicals
- 18.7 Inframat
- 18.8 Plasmachem
- 18.9 Nanografi Nano Technology
- 18.10 Meliorum Technologies
- 18.11 American Elements
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

