
Market Overview:
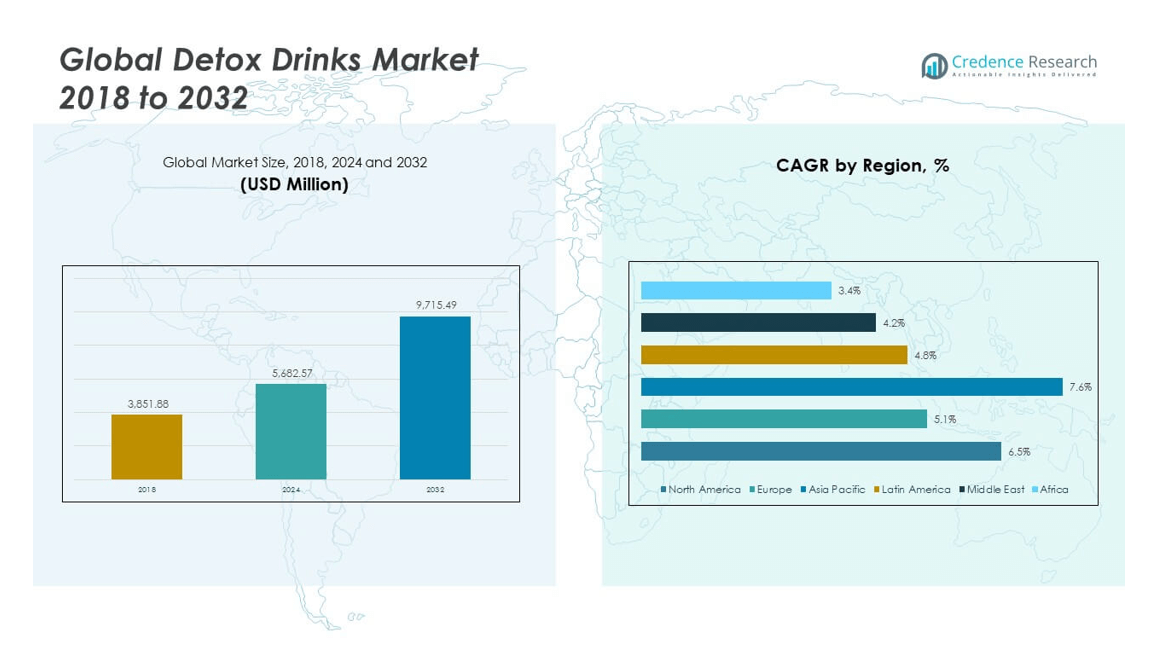
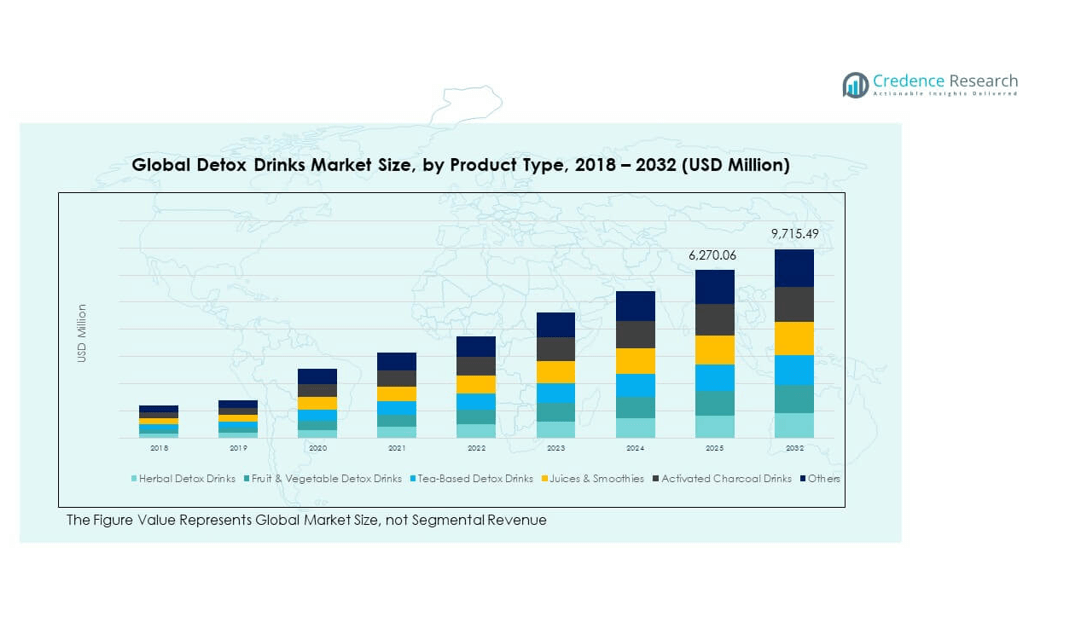
The Global Detox Drinks Market size was valued at USD 3,851.88 million in 2018, reached USD 5,682.57 million in 2024, and is anticipated to hit USD 9,715.49 million by 2032, at a CAGR of 6.46% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Detox Drinks Market Size 2024 | USD 5,682.57 million |
| Detox Drinks Market, CAGR | 6.46% |
| Detox Drinks Market Size 2032 | USD 9,715.49 million |
Consumer awareness of health and wellness continues to drive strong demand. People are choosing detox drinks for benefits like body cleansing, digestive health, and energy boosting. Increasing cases of obesity, lifestyle-related diseases, and urban stress also push more consumers toward these beverages. Celebrity endorsements, fitness trends, and social media campaigns further fuel market penetration across both developed and emerging economies.
North America and Europe dominate due to higher adoption of functional beverages and established health trends. Asia Pacific is emerging as a fast-growing region, driven by rising disposable incomes, urbanization, and health awareness in countries like India and China. Latin America and the Middle East show growing interest, supported by changing lifestyles and retail expansion. Africa remains a nascent market but holds promise with increasing urban middle-class populations.
Market Insights:
- The Global Detox Drinks Market was valued at USD 3,851.88 million in 2018, reached USD 5,682.57 million in 2024, and is projected to hit USD 9,715.49 million by 2032, expanding at a CAGR of 6.46%.
- North America (43.3%), Asia Pacific (30.7%), and Europe (17.1%) held the largest regional shares in 2024, supported by strong wellness culture, higher purchasing power, and established retail ecosystems.
- Asia Pacific is the fastest-growing region, holding 30.7% share in 2024, with growth fueled by urbanization, disposable income rise, and cultural acceptance of herbal remedies.
- Fruit & vegetable detox drinks and herbal detox drinks together accounted for over 50% of the market share in 2024, reflecting high demand for natural and nutrient-rich beverages.
- Tea-based detox drinks and juices & smoothies jointly represented about 35% share, driven by traditional tea consumption in Asia and the rising preference for convenient, flavorful, functional beverages worldwide.
Market Drivers:
Rising Consumer Awareness of Preventive Health and Wellness:
The Global Detox Drinks Market benefits from the rising focus on preventive health. Consumers prefer natural remedies that support liver cleansing, metabolism, and immunity. Growing lifestyle-related illnesses push more buyers toward detoxification beverages. Influencers and health professionals promote daily detox practices, creating stronger market appeal. Social media has accelerated the awareness cycle, bringing wellness closer to younger demographics. It is helping brands capture attention with clean-label promises. Innovative campaigns tie detoxification to energy, skin glow, and holistic wellness. This heightened awareness sustains consistent demand across product categories.
- For example, Karviva is a U.S.-based wellness beverage company known for plant-based functional drinks. The brand focuses on blends inspired by traditional healing practices and modern nutrition science.
Expanding Fitness and Weight Management Culture Across Regions:
Fitness culture is fueling higher sales of detox drinks worldwide. Gym-goers, yoga practitioners, and athletes use these beverages to support endurance and recovery. Weight-loss programs integrate detox products to boost metabolism and appetite control. The shift from carbonated drinks toward functional beverages strengthens adoption rates. Social trends link detox drinks with slim, active lifestyles, enhancing their aspirational value. It creates growth momentum in urban and semi-urban clusters. Companies tailor detox formulations for weight-conscious consumers seeking convenience. This alignment with fitness culture ensures long-term traction.
Innovation in Product Formulation and Clean-Label Branding:
Innovation drives the appeal of detox drinks by offering diverse flavors and nutritional benefits. Brands invest in herbal infusions, fruit blends, and plant-based enhancements. Demand for non-GMO, organic, and preservative-free labels fuels clean branding. It enhances consumer trust and supports premium pricing strategies. Functional add-ons like probiotics, adaptogens, and vitamins increase product differentiation. Beverage manufacturers highlight transparency in ingredient sourcing to appeal to health-focused buyers. New product launches are frequent, aiming at taste variety and efficacy. This innovation cycle sustains competitive advantage across retail and online platforms.
- For example, Hain Celestial’s Blueprint brand is recognized for its organic, non-GMO detox beverages. The company has also introduced blends featuring plant-based probiotics to cater to health-conscious consumers in the U.S. market.
Expanding Distribution Channels and E-commerce Penetration:
Distribution networks have broadened, strengthening market access for detox products. Supermarkets, hypermarkets, and specialty health stores drive visibility in urban markets. E-commerce accelerates sales with doorstep delivery and subscription models. It provides exposure for niche brands entering competitive landscapes. Digital marketing boosts consumer engagement through personalized offers and trial packs. Direct-to-consumer brands leverage social platforms for awareness and retention. Cross-border e-commerce introduces detox drinks to international buyers. This multi-channel strategy expands reach and supports steady revenue growth.
Market Trends:
Growing Demand for Functional Beverages with Added Nutritional Value
The Global Detox Drinks Market is witnessing a trend toward functional beverages enriched with nutrients. Manufacturers now add probiotics, vitamins, and antioxidants to expand consumer benefits. Buyers prefer drinks that not only detoxify but also improve digestion and immunity. Natural sweeteners replace artificial sugars, aligning with clean-label commitments. This trend broadens the market’s appeal across millennials and health-conscious professionals. It creates differentiation for brands in a competitive industry. Innovative packaging highlights nutritional claims clearly to attract attention. This trend sustains premiumization and repeat consumption.
- For example, Turveda offers three functional Prebiotic Super Soda flavors Wellness, Chill, and Immunity crafted with prebiotics and botanicals to support gut and immune health. Live it Up Super Greens delivers 5 billion CFUs of probiotics along with superfoods and enzymes to aid digestion and immunity.
Shift Toward Plant-Based and Herbal Detox Formulations
Plant-based lifestyles are reshaping beverage consumption habits. Detox drinks featuring herbal infusions, green tea, and Ayurvedic blends are gaining traction. Consumers perceive plant-based ingredients as safer and more effective. Brands highlight herbal traditions combined with modern science to appeal to global audiences. Vegan-friendly labeling strengthens trust in product portfolios. Herbal detox products see strong demand in regions valuing natural remedies. It enables brands to expand into dietary supplement categories. This plant-driven trend reinforces sustainability and clean-living narratives.
Premiumization and Rise of Lifestyle-Oriented Marketing
Premium product positioning is a strong trend in the detox drink space. Buyers are ready to pay more for high-quality, organic, and exotic ingredient-based drinks. Marketing campaigns link detox beverages to luxury wellness experiences. Fitness studios, spas, and boutique cafes partner with brands to promote exclusivity. Attractive glass bottles and eco-friendly designs enhance lifestyle appeal. It resonates with younger urban populations seeking premium wellness solutions. Companies highlight artisanal production and sustainable sourcing to justify pricing. This premiumization strengthens margins and market positioning.
Increasing Role of Technology and Personalization in Sales
Technology is transforming how consumers engage with detox brands. Personalized subscription models tailor product mixes to individual health goals. AI-driven apps recommend detox routines, supporting higher product relevance. Online platforms enable data-driven targeting and promotional campaigns. QR codes on packaging offer ingredient details and wellness tips. Virtual fitness platforms often collaborate with detox drink makers for bundled offerings. Smart packaging and sustainability tracking appeal to eco-conscious consumers. It ensures digital-first buyers remain loyal to health beverage categories. This tech-led personalization enhances engagement and repeat sales.
- For example, Hint Inc., a U.S.-based beverage brand, is recognized for its unsweetened flavored water and strong direct-to-consumer subscription model. The company uses digital engagement strategies, including online sales and subscription services, to reach health-conscious consumers.
Market Challenges Analysis:
High Price Sensitivity and Consumer Skepticism Toward Claims
The Global Detox Drinks Market faces challenges from price-sensitive buyers. Premium pricing strategies limit penetration in developing economies. Many consumers remain skeptical about detoxification claims, fearing overstated benefits. Competition from natural juices and homemade remedies also affects adoption. Regulatory scrutiny of health claims adds another barrier for new entrants. It forces brands to invest heavily in clinical validation and compliance. Smaller firms struggle to match marketing budgets of established companies. Overcoming skepticism requires transparency and consistent product efficacy.
Supply Chain Complexities and Dependence on Seasonal Ingredients
Supply chain issues affect the availability of raw ingredients used in detox drinks. Seasonal fruits, herbs, and organic inputs create fluctuations in supply. Rising input costs due to inflation increase production challenges. Manufacturers face difficulties in ensuring consistent taste and nutritional value. Global disruptions, including logistics delays, limit timely product distribution. Dependence on imported superfoods further complicates supply security. It pressures companies to explore local sourcing and vertical integration. Managing these supply hurdles is critical to sustainable growth.
Market Opportunities:
Rising Demand in Emerging Economies with Health-Focused Populations
Emerging markets present strong growth opportunities for detox beverage companies. Rising disposable incomes enable consumers to adopt functional drinks more frequently. Rapid urbanization increases exposure to health trends via digital media. Younger demographics in Asia and Latin America embrace wellness lifestyles quickly. It supports higher acceptance of herbal and fruit-based detox beverages. Growing retail penetration enhances accessibility across metro and semi-urban regions. Brands expanding to these economies gain long-term competitive advantage. This shift creates fertile ground for future expansion.
Development of Innovative Flavors and Cross-Category Collaborations
Flavor innovation opens new opportunities in the Global Detox Drinks Market. Exotic blends, regional fruit infusions, and superfood combinations attract experimental buyers. Collaborations with fitness centers, wellness apps, and restaurants extend product exposure. It diversifies usage occasions beyond health routines to social gatherings. Limited-edition launches and seasonal flavors boost trial rates among consumers. Beverage makers invest in R&D to test flavor acceptance globally. Such collaborations enhance lifestyle integration and create sustainable revenue streams. Innovation-driven appeal ensures steady future growth.
Market Segmentation Analysis:
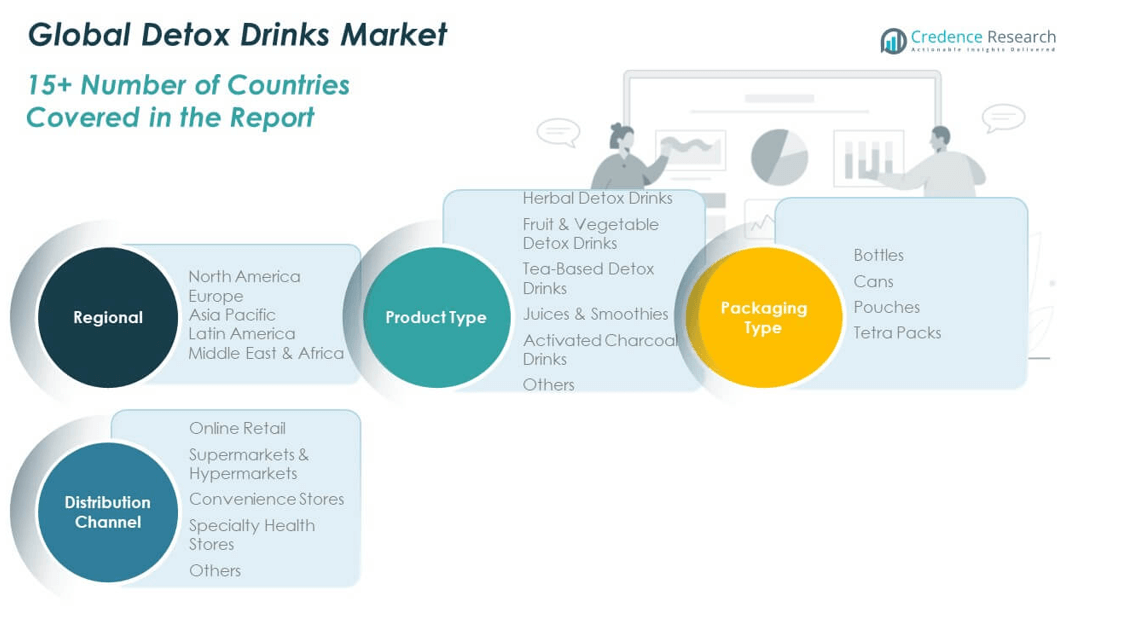
By Product Type, the Global Detox Drinks Market demonstrates strong product diversity, with herbal detox drinks leading due to their association with natural healing and cleansing. Consumers favor herbal formulations for perceived safety and effectiveness, driving large-scale adoption. Fruit and vegetable detox drinks are rapidly expanding, particularly among young and urban populations seeking fresh, flavorful, and nutrient-dense beverages. Tea-based detox drinks remain popular in Europe and Asia, where tea consumption is culturally rooted. Juices and smoothies capture a wide consumer base with convenience and taste variety. Activated charcoal drinks serve niche health-conscious buyers seeking advanced detoxification, though adoption remains limited. Other emerging blends experiment with superfoods and adaptogens, creating innovation-driven opportunities.
- For instance, PepsiCo has diversified its beverage portfolio with functional beverages like prebiotic sodas and other wellness-focused drinks, leveraging its extensive global distribution network to boost market presence and accelerate consumer adoption in urban clusters worldwide.
By Packaging Type, bottles dominate packaging preferences, offering portability, transparency in product display, and premium appeal. They align well with on-the-go lifestyles, making them the top choice across regions. Cans cater to younger demographics seeking affordable, ready-to-drink options, while tetra packs remain strong in mass-market distribution due to affordability and longer shelf life. Pouches are gaining traction among eco-conscious consumers and brands focusing on sustainable packaging solutions. Packaging innovation highlights functionality, sustainability, and brand image, enabling companies to differentiate in competitive markets.
- For instance, Hain Celestial has implemented sustainable packaging initiatives across its beverage lines, such as removing plastic overwrap from Celestial Seasonings tea boxes to eliminate waste.
By Distribution Channel, distribution is a critical growth driver, with supermarkets and hypermarkets leading in visibility and accessibility for mainstream buyers. Specialty health stores attract premium consumers who prioritize organic, herbal, and niche wellness brands. Online retail is the fastest-growing channel, supported by digital marketing, subscription models, and cross-border e-commerce opportunities. Convenience stores play a strong role in impulse purchases, especially for smaller pack sizes and affordable variants. Multi-channel distribution strategies are becoming essential for brands to capture broad consumer bases and ensure long-term market presence.
Segmentation:
By Product Type
- Herbal Detox Drinks
- Fruit & Vegetable Detox Drinks
- Tea-Based Detox Drinks
- Juices & Smoothies
- Activated Charcoal Drinks
- Others
By Packaging Type
- Bottles
- Cans
- Pouches
- Tetra Packs
By Distribution Channel
- Online Retail
- Supermarkets & Hypermarkets
- Convenience Stores
- Specialty Health Stores
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
The North America Global Detox Drinks Market size was valued at USD 1,684.60 million in 2018 to USD 2,459.47 million in 2024 and is anticipated to reach USD 4,216.62 million by 2032, at a CAGR of 6.5% during the forecast period. North America accounted for 43.3% of the global market share in 2024. The Global Detox Drinks Market in North America thrives on high consumer health awareness and strong preference for clean-label products. The U.S. leads adoption, supported by fitness culture, influencer marketing, and premiumization trends. Canada contributes steadily, driven by organic and vegan lifestyles, while Mexico shows growth through younger demographics seeking affordable alternatives. Widespread retail penetration across supermarkets, hypermarkets, and specialty stores enhances accessibility. E-commerce platforms offer direct-to-consumer opportunities and subscription models. Regulatory oversight ensures product safety and transparency, boosting consumer trust. Innovation in herbal and functional blends further strengthens market momentum in this region.
Europe
The Europe Global Detox Drinks Market size was valued at USD 698.50 million in 2018 to USD 972.36 million in 2024 and is anticipated to reach USD 1,507.00 million by 2032, at a CAGR of 5.1% during the forecast period. Europe accounted for 17.1% of the global market share in 2024. The Global Detox Drinks Market in Europe is shaped by a mature wellness culture and strict food standards. The UK, Germany, and France dominate consumption with strong demand for herbal and tea-based formulations. Southern countries like Spain and Italy favor fruit and vegetable-based detox drinks, benefiting from abundant local produce. Retail distribution is robust, supported by health-focused specialty stores and organized supermarket networks. Consumers prioritize transparency, sustainability, and eco-friendly packaging. Clean-label certification plays a key role in shaping purchasing behavior. Premium pricing strategies find acceptance among affluent urban consumers. Market growth is reinforced by evolving vegan and plant-based lifestyles across the region.
Asia Pacific
The Asia Pacific Global Detox Drinks Market size was valued at USD 1,121.80 million in 2018 to USD 1,746.65 million in 2024 and is anticipated to reach USD 3,254.78 million by 2032, at a CAGR of 7.6% during the forecast period. Asia Pacific accounted for 30.7% of the global market share in 2024. The Global Detox Drinks Market in Asia Pacific shows the fastest growth rate due to rising disposable incomes and urbanization. China and India drive adoption with large populations and growing awareness of preventive health. Japan and South Korea remain mature markets, particularly for tea-based and herbal detox drinks. Southeast Asia is witnessing rapid uptake through digital channels and rising fitness culture. Younger demographics across the region are highly receptive to clean-label and plant-based beverages. E-commerce penetration accelerates product availability and trial. Companies actively launch innovative flavors tailored to regional tastes. The region’s cultural acceptance of herbal remedies enhances long-term growth potential.
Latin America
The Latin America Global Detox Drinks Market size was valued at USD 178.09 million in 2018 to USD 259.39 million in 2024 and is anticipated to reach USD 391.41 million by 2032, at a CAGR of 4.8% during the forecast period. Latin America accounted for 4.6% of the global market share in 2024. The Global Detox Drinks Market in Latin America grows steadily with the expansion of fitness culture and wellness awareness. Brazil leads demand, supported by a strong market for fruit-based beverages. Argentina and Mexico contribute through rising urbanization and increased retail access. Health campaigns highlighting preventive nutrition further push adoption. Younger demographics show willingness to try innovative and affordable detox products. E-commerce supports niche brand visibility and direct engagement. Partnerships with gyms and wellness clubs expand product reach. The market benefits from a growing middle class embracing healthier beverage alternatives.
Middle East
The Middle East Global Detox Drinks Market size was valued at USD 109.18 million in 2018 to USD 147.40 million in 2024 and is anticipated to reach USD 213.14 million by 2032, at a CAGR of 4.2% during the forecast period. The Middle East accounted for 2.6% of the global market share in 2024. The Global Detox Drinks Market in the Middle East is driven by rising disposable incomes and demand for premium wellness beverages. GCC countries, led by Saudi Arabia and the UAE, dominate consumption due to higher purchasing power. Consumers prefer herbal, juice-based, and organic detox options aligned with preventive health goals. Retail expansion through supermarkets and specialty stores strengthens accessibility. Seasonal fasting and fitness events create spikes in demand. Israel and Turkey show rising uptake, particularly among younger populations. Imported premium brands gain traction in urban hubs. The market reflects strong margins but remains limited in overall scale.
Africa
The Africa Global Detox Drinks Market size was valued at USD 59.71 million in 2018 to USD 97.30 million in 2024 and is anticipated to reach USD 132.55 million by 2032, at a CAGR of 3.4% during the forecast period. Africa accounted for 1.7% of the global market share in 2024. The Global Detox Drinks Market in Africa is still at an early growth stage, with potential tied to urbanization. South Africa leads the region with a growing urban middle class and retail presence. Egypt shows increasing awareness through social media and wellness campaigns. Affordability remains a challenge, limiting adoption in rural and low-income areas. Companies test smaller pack sizes to expand accessibility. E-commerce platforms and urban retail improve product reach. Herbal-based detox drinks align well with local traditions, helping adoption. International players are gradually expanding footprints in key metro markets. Africa offers long-term promise as lifestyles shift toward modern health solutions.
Key Player Analysis:
- Suja Life LLC
- Schulze's
- Naked Juice
- Organifi
- Kara Pure
- Pukka Herbs Limited
- Raw Generation Inc.
- Juice Generation Inc.
- Yogi Juice Bar
- Purearth Evolution Ltd.
- PUR Brands LLC
Competitive Analysis:
The Global Detox Drinks Market is highly competitive with both established players and emerging brands. Companies focus on clean-label, organic, and plant-based offerings to build trust. Innovation in flavors and functional blends strengthens differentiation. Marketing strategies rely on digital campaigns, influencer partnerships, and premium positioning. Distribution networks expand across supermarkets, specialty stores, and online platforms. Firms emphasize sustainable packaging and transparent sourcing to attract eco-conscious buyers. Competitive intensity increases with regional startups entering wellness beverage categories. The market continues to evolve with high investment in R&D and strong branding strategies.
Recent Developments:
- In January 2025, this refresh is part of Pukka's ongoing commitment to combine traditional herbal wisdom with modern nutritional science.
- In May 2024, Suja Life LLC announced its acquisition of the cult classic soda brand Slice. The company plans to relaunch Slice in 2025 with a fresh look and revamped formula focused on better-for-you benefits like gut health, low sugar, and clean ingredients. This acquisition expands Suja Life's wellness beverage portfolio under CEO Maria Stipp's guidance.
Report Coverage:
The research report offers an in-depth analysis based on product type, packaging type, and distribution channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising health consciousness will continue to fuel demand for detox drinks as consumers prioritize wellness and functional beverages in their daily routines.
- Herbal and plant-based products are expected to dominate new launches, with brands leveraging natural ingredients to appeal to health-focused buyers.
- E-commerce will remain the strongest distribution channel, supported by digital convenience, subscription models, and direct-to-consumer strategies.
- Asia Pacific will emerge as the fastest-growing regional market, driven by expanding middle-class populations and increasing awareness of holistic health.
- Premiumization will play a key role in strengthening brand positioning, as consumers seek higher-quality products with added benefits.
- Strategic partnerships with fitness and wellness centers are likely to rise, enhancing product visibility and credibility within targeted communities.
- Flavor innovation will be central to attracting younger demographics, who value variety, novelty, and personalization in beverage choices.
- Clean-label demands and ingredient transparency will intensify, shaping product development and marketing approaches.
- Regulatory compliance will remain a critical challenge, requiring brands to ensure safety and meet evolving global standards.
- Sustainable packaging solutions will strongly influence purchasing preferences, reflecting growing environmental awareness among consumers worldwide.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Consumer Awareness of Preventive Health and Wellness
Growing awareness of preventive health and wellness is driving consumers to seek out detox drinks for benefits such as body cleansing, digestive health, and immunity support. Social media, influencer marketing, and health professionals are amplifying the appeal of detox beverages, especially among younger demographics.
Expanding Fitness and Weight Management Culture
The global rise in fitness culture and weight management trends is fueling demand for detox drinks as consumers integrate these beverages into their routines for metabolism support, endurance, and recovery. Detox drinks are increasingly associated with active, healthy lifestyles and are promoted in gyms, yoga studios, and wellness programs.
Innovation in Product Formulation and Clean-Label Branding
Brands are investing in innovative formulations, including herbal infusions, fruit blends, and functional add-ons like probiotics and adaptogens, to differentiate their products. The demand for non-GMO, organic, and preservative-free detox drinks supports premiumization and builds consumer trust through clean-label branding.
Expanding Distribution Channels and E-commerce Penetration
Broader distribution networks, including supermarkets, specialty health stores, and especially e-commerce platforms, are making detox drinks more accessible. Online retail and subscription models are accelerating market penetration, allowing brands to reach a wider audience and offer personalized purchasing experiences.
Premiumization and Lifestyle-Oriented Marketing
Consumers are increasingly willing to pay premium prices for high-quality, organic, and exotic detox drinks that are marketed as part of a luxury wellness lifestyle. Strategic partnerships with fitness centers, spas, and boutique cafes, along with attractive packaging and sustainability initiatives, are enhancing brand positioning and driving market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Detox Drinks Market, and what is its projected size in 2032?
Which Global Detox Drinks Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Detox Drinks Market?
Who are the leading companies in the Global Detox Drinks Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Herbal Detox Drinks
- 1.2.2 Fruit & Vegetable Detox Drinks
- 1.2.3 Tea-Based Detox Drinks
- 1.2.4 Juices & Smoothies
- 1.2.5 Activated Charcoal Drinks
- 1.2.6 Others
- 1.3 By Packaging Type
- 1.3.1 Bottles
- 1.3.2 Cans
- 1.3.3 Pouches
- 1.3.4 Tetra Packs
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,682.57 million → 2032: USD 9,715.49 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Detox Drinks Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Detox Drinks Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Detox Drinks Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Detox Drinks Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Detox Drinks Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Detox Drinks Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Detox Drinks Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Detox Drinks Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,682.57 million → 2032: USD 9,715.49 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Detox Drinks Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Herbal Detox Drinks
- 12.3.7.2 Fruit & Vegetable Detox Drinks
- 12.3.7.3 Tea-Based Detox Drinks
- 12.3.7.4 Juices & Smoothies
- 12.3.7.5 Activated Charcoal Drinks
- 12.3.7.6 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Packaging Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Bottles
- 12.4.7.2 Cans
- 12.4.7.3 Pouches
- 12.4.7.4 Tetra Packs
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Detox Drinks Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Detox Drinks Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Detox Drinks Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Suja Life LLC
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Naked Juice
- 17.4 Organifi
- 17.5 Pukka Herbs Limited
- 17.6 Raw Generation Inc.
- 17.7 Juice Generation Inc.
- 17.8 Purearth Evolution Ltd.
- 17.9 PUR Brands LLC
- 17.10 Hain Celestial (Blueprint)
- 17.11 PepsiCo
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

