
Dilated Cardiomyopathy Therapeutic Market
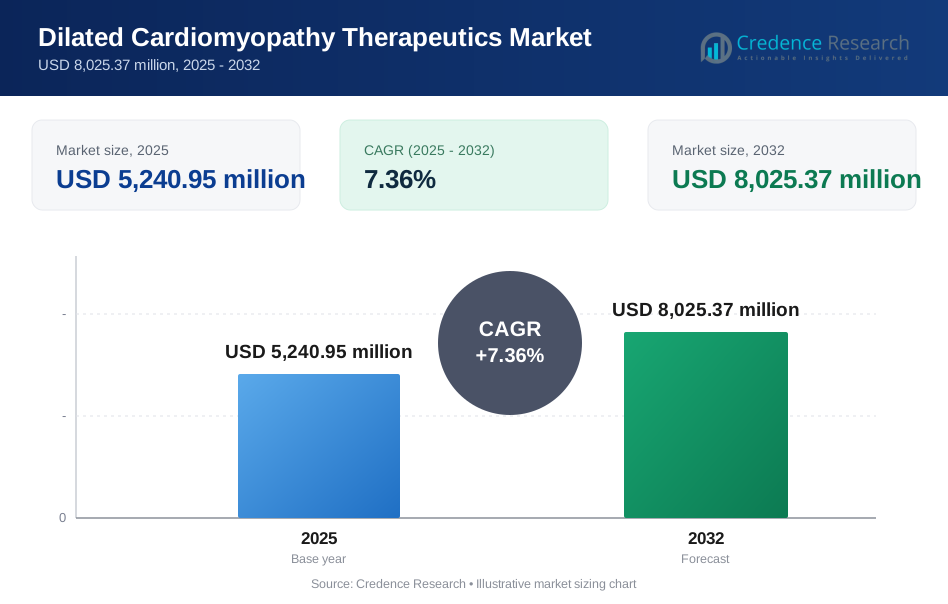
The Dilated Cardiomyopathy Therapeutic Market size was estimated at USD 5,240.95 million in 2025 and is expected to reach USD 8,025.37 million by 2032, growing at a CAGR of 7.36% from 2025 to 2032. Growth is primarily driven by expanding heart-failure care pathways that improve diagnosis, accelerate treatment initiation, and increase long-duration use of guideline-directed regimens across broader patient cohorts. Technology-enabled monitoring and specialized cardiac networks are also supporting more consistent therapy optimization and timely escalation to advanced interventions where clinically appropriate.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2021-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Dilated Cardiomyopathy Therapeutic Market Size 2025 | USD 5,240.95 million |
| Dilated Cardiomyopathy Therapeutic Market, CAGR | 7.36% |
| Dilated Cardiomyopathy Therapeutic Market Size 2032 | USD 8,025.37 million |
Key Market Trends & Insights
- The Dilated Cardiomyopathy Therapeutic Market is forecast to expand at 7.36% CAGR (2025–2032), reflecting steady therapy optimization and broader access to structured heart-failure care.
- The Dilated Cardiomyopathy Therapeutic Market is projected to reach USD 8,025.37 million by 2032, supported by sustained utilization of multi-class drug regimens and advanced care pathways.
- North America accounted for 41.6% in 2025, underpinned by higher diagnosis rates, mature reimbursement for chronic therapy, and deeper specialist capacity across hospital systems.
- ACE inhibitors held 33.2% in 2025 within the drug-class mix, supported by entrenched clinical familiarity and frequent use as part of foundational heart-failure regimens.
- Hospitals represented 58.4% in 2025 by end user, reflecting concentration of diagnosis, initiation of complex regimens, and access to device and procedural capabilities.

Segment Analysis
Dilated Cardiomyopathy Therapeutic Market demand is anchored in long-term medical management, where multi-drug regimens are used to slow remodeling, reduce hospitalization risk, and stabilize functional status. Treatment pathways commonly progress from foundational pharmacological regimens to advanced device and procedural options for eligible patients based on arrhythmic risk, dyssynchrony, and hemodynamic stability. Earlier identification and better longitudinal follow-up extend therapy duration per patient and increase titration activity, which supports recurring prescription volumes and monitoring services.
Care delivery is shaped by provider capability and referral pathways, with hospitals and specialized cardiac centers leading diagnostic confirmation, acute stabilization, and complex escalation decisions. Homecare relevance grows as chronic monitoring expands and adherence programs become more structured, especially for stable patients managed over long horizons. Purchasing behavior typically favors solutions that demonstrate consistent outcomes in real-world settings and integrate smoothly into clinical workflows, including imaging, electrophysiology evaluation, and follow-up programs.
By Therapy Type Insights
Pharmacological Therapy remains the dominant foundation for most treated populations because guideline-directed regimens are initiated early and maintained across long time horizons. Broad eligibility and established prescribing pathways support high utilization across disease stages, including early management and advanced optimization. Device-based pathways expand in clinically eligible patients to manage arrhythmic risk and improve synchronization, particularly where specialist capacity and referral networks are strong. Surgical and advanced interventions concentrate in advanced and end-stage populations where escalation is clinically necessary and center capability supports complex care.
By Drug Class Insights
ACE Inhibitors accounted for the largest share of 33.2% in 2025. ACE inhibitors lead due to long-standing clinical use patterns, broad prescriber familiarity, and frequent placement within foundational heart-failure regimens used across dilated cardiomyopathy care pathways. Treatment protocols often layer additional classes alongside ACE inhibitors to support symptom control and reduce hospitalization risk, which sustains multi-drug utilization. Uptake also benefits from established access pathways and routine incorporation into titration programs managed in hospital and specialist settings.
By Device Type Insights
ICDs and CRT devices are central options for eligible patients where arrhythmic risk mitigation and synchronization improvements are clinically indicated, especially in advanced systolic dysfunction settings. Adoption is influenced by referral patterns, center expertise, and follow-up infrastructure that supports implantation, programming, and monitoring. Ventricular assist devices remain concentrated in advanced and end-stage populations, where specialized centers manage selection, implantation, and long-term surveillance. Device selection is shaped by evidence alignment, safety performance, service capability, and integration into multidisciplinary heart-failure programs.
By Disease Stage Insights
Early-stage DCM volumes grow as diagnosis improves and providers intervene sooner with structured pharmacological optimization and risk-factor management. Advanced DCM drives escalation toward devices and more intensive monitoring because symptom burden and arrhythmic risk become more prominent. End-stage heart failure concentrates high-acuity interventions, including mechanical circulatory support and advanced procedures within specialized centers. Disease-stage dynamics are shaped by referral efficiency, patient adherence, comorbidity burden, and access to specialized diagnostic and procedural capacity.
By End User Insights
Hospitals accounted for the largest share of 58.4% in 2025. Hospitals lead because hospitals concentrate diagnostic confirmation, acute stabilization, and initiation of complex multi-class regimens that require close monitoring and titration. Hospitals also serve as key access points for advanced imaging, electrophysiology assessment, and device-linked pathways in eligible patients. Care coordination and multidisciplinary heart-failure programs are more consistently available within hospital systems, which supports adherence, follow-up intensity, and timely escalation decisions.
Dilated Cardiomyopathy Therapeutic Market Drivers
Expansion of guideline-directed therapy pathways
Dilated Cardiomyopathy Therapeutic Market growth is supported by broader adoption of guideline-directed care models that standardize initiation and titration of multi-class regimens. Provider teams increasingly follow structured protocols that reduce treatment variation and improve continuity of care across settings. Earlier diagnostic confirmation expands the treated pool and increases therapy duration per patient. Clinical decision support and monitoring practices improve titration speed and follow-up adherence. These factors support recurring utilization across drug and device pathways.
- For instance, Novartis reported from the 8,442-patient PARADIGM-HF study that Entresto reduced cardiovascular death by 20%, heart failure hospitalizations by 21%, and all-cause mortality by 16% versus enalapril, underscoring how standardized multi-class heart-failure treatment pathways can translate into measurable clinical gains.
Earlier diagnosis and improved care access
Dilated Cardiomyopathy Therapeutic Market demand rises as imaging and diagnostic pathways improve identification of systolic dysfunction and cardiomyopathy phenotypes. Earlier detection shifts treatment initiation forward in the care journey and increases cumulative therapy exposure over time. Referral networks that connect primary care, cardiology, and specialty centers improve treatment continuity and timely escalation. Expanded access to specialized services increases utilization of advanced therapies in eligible cohorts. Higher follow-up intensity also strengthens adherence and persistence.
- For instance, Ultromics stated that its EchoGo Heart Failure platform detected 88% of patients with HFpEF and correctly excluded 82% of patients without the condition, while also correctly assigning a diagnosis in 74% of patients who had non-diagnostic HFA-PEFF or H2FPEF scores, highlighting how AI-enabled imaging can accelerate earlier and more confident pathway entry.
Growth of specialized cardiac programs
Dilated Cardiomyopathy Therapeutic Market expansion is reinforced by the growth of multidisciplinary heart-failure programs that coordinate medication optimization, device evaluation, and longitudinal monitoring. These programs improve care standardization and create predictable pathways for therapy escalation based on clinical criteria. Specialist-led clinics increase patient engagement, medication titration cadence, and follow-up reliability. Integration of electrophysiology and imaging services supports better risk stratification and device decision-making. The resulting care intensity supports sustained demand.
Technology-enabled monitoring and workflow integration
Dilated Cardiomyopathy Therapeutic Market growth benefits from wider use of remote monitoring and digital follow-up that support adherence, early decompensation detection, and therapy optimization. Monitoring tools improve clinician confidence in titration and facilitate timely intervention for high-risk patients. Integration into clinical workflows reduces administrative friction and strengthens continuity across care settings. Technology-supported programs also expand the addressable population for home-based management. These capabilities raise the value of comprehensive care pathways.
Dilated Cardiomyopathy Therapeutic Market Challenges
Dilated Cardiomyopathy Therapeutic Market adoption is constrained by variability in diagnosis timing, specialist capacity, and access to advanced interventions across health systems. Many patients remain underdiagnosed or receive delayed referrals, limiting early optimization and appropriate escalation. Cost sensitivity and reimbursement differences can restrict uptake of newer therapies and advanced devices in some settings. Complex comorbidities can reduce tolerability and complicate titration, increasing discontinuation risk. Fragmented follow-up can weaken adherence and long-term outcomes.
- For instance, Medtronic reported pooled evidence from five randomized CRT trials involving 3,872 patients, showing a 26% relative reduction in 30-day readmissions after a heart-failure hospitalization among patients treated with cardiac resynchronization therapy, which demonstrates the measurable benefit of advanced device-based intervention when eligible patients are identified and referred on time.
Dilated Cardiomyopathy Therapeutic Market execution also faces operational barriers related to long-term monitoring, care coordination, and patient persistence. Treatment pathways often require frequent dose adjustments and multi-class therapy layering, which increases clinical workload. Device-linked care depends on procedural capacity, trained staff, and post-implant monitoring infrastructure that is unevenly distributed. Patient adherence can be affected by side effects, regimen complexity, and socioeconomic barriers. These constraints can slow conversion from diagnosis to optimized therapy.
Dilated Cardiomyopathy Therapeutic Market Trends and Opportunities
Dilated Cardiomyopathy Therapeutic Market opportunities are expanding through broader use of integrated heart-failure clinics that combine medication optimization, imaging, electrophysiology assessment, and remote follow-up. Providers increasingly prioritize pathways that reduce readmissions and improve functional outcomes through consistent longitudinal care. Growth is supported by care models that improve adherence, streamline titration, and formalize escalation criteria for devices and advanced interventions. This structure creates opportunities for solutions that integrate with clinical workflows and support measurable outcomes.
- For instance, Abbott’s CardioMEMS HF System showed a 44% reduction in heart-failure hospitalizations and a 7-point improvement in patient-reported quality of life in the MONITOR-HF randomized trial of 348 patients conducted across 25 sites in the Netherlands, highlighting how integrated follow-up technologies can support measurable outcomes within structured care pathways.
Dilated Cardiomyopathy Therapeutic Market momentum is also supported by innovation in device pathways, monitoring, and population health programs that identify high-risk patients earlier. Remote monitoring and structured follow-up can expand home-based management and reduce care fragmentation. Specialty centers continue to influence adoption through protocol development and referral network leadership. As health systems focus on efficiency and outcome consistency, opportunities increase for therapies and technologies that support standardized care across multi-site networks.
Regional Insights
North America
Dilated Cardiomyopathy Therapeutic Market leadership in North America, holding 41.6% share in 2025, reflects strong diagnosis rates, mature reimbursement pathways, and deeper specialist capacity across hospitals and cardiac programs. Adoption benefits from structured titration practices, higher penetration of advanced imaging, and consistent follow-up models that support chronic therapy persistence. Device pathways are supported by procedural capacity and established post-implant monitoring infrastructure. Market activity is reinforced by health-system focus on reducing readmissions and improving outcomes through standardized care pathways.
Europe
Dilated Cardiomyopathy Therapeutic Market conditions in Europe, accounting for 29.1% share in 2025, reflect structured health systems and strong clinical guideline alignment, with adoption shaped by country-specific reimbursement and procurement models. Specialist centers and hospital networks support standardized treatment protocols and longitudinal care coordination. Device adoption is meaningful in eligible patients, but utilization levels vary by local access and budget priorities. Care delivery benefits from regional referral networks that concentrate advanced interventions in high-capability centers.
Asia Pacific
Dilated Cardiomyopathy Therapeutic Market expansion in Asia Pacific, representing 21.8% share in 2025, is supported by growing cardiovascular disease management capacity, improving diagnosis rates in urban centers, and increasing access to guideline-driven therapy pathways. Growth is moderated by uneven reimbursement, variable specialist availability, and differing device penetration across markets. Large tertiary hospitals and private cardiology networks drive adoption, particularly where follow-up infrastructure supports titration and monitoring. Market development is strengthened by investments in hospital modernization and chronic care programs.
Latin America
Dilated Cardiomyopathy Therapeutic Market adoption in Latin America, with 4.7% share in 2025, is shaped by variability in reimbursement, limited specialist density in some areas, and concentration of advanced care in major metropolitan centers. Demand is supported by hospital and private network capacity where guideline adoption is strong and follow-up programs are available. Device utilization is influenced by affordability, procurement cycles, and procedural infrastructure. Opportunities increase where structured heart-failure programs expand and referral pathways improve.
Middle East & Africa
Dilated Cardiomyopathy Therapeutic Market growth in the Middle East & Africa, holding 2.8% share in 2025, is supported by select high-capability health systems that invest in specialist programs, advanced diagnostics, and procedural infrastructure. Broader adoption is constrained by uneven access to cardiology services, affordability barriers, and limited longitudinal follow-up in some settings. Demand concentrates in private systems and higher-income markets where chronic care programs are more established. Expansion improves where referral networks and monitoring practices scale across health systems.
Competitive Landscape
Dilated Cardiomyopathy Therapeutic Market competition spans established cardiovascular drug portfolios, incremental regimen optimization, and differentiated device pathways that address arrhythmic risk and advanced heart-failure needs. Companies compete on clinical evidence depth, breadth of portfolio coverage across care stages, and ability to support adoption through education and care pathway alignment. Device-focused players emphasize procedural reliability, monitoring capabilities, and service support for hospital and specialty-center deployments. Commercial differentiation often depends on access strategy, payer alignment, and integration with multidisciplinary heart-failure programs.
Novartis maintains a strong cardiovascular focus with emphasis on evidence generation, lifecycle management, and alignment with guideline-driven care pathways. Novartis strategy typically prioritizes broad clinical utility, consistent outcomes reporting, and engagement with provider networks that influence treatment standards. Novartis also benefits from established market access capabilities that support scale across major health systems. Competitive positioning is strengthened when real-world evidence and long-term outcome consistency reinforce prescriber confidence across diverse patient cohorts.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Novartis
- AstraZeneca
- Pfizer
- Bayer
- Boehringer Ingelheim
- Medtronic
- Abbott
- Boston Scientific
- Bristol Myers Squibb
- Merck & Co.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In June 2025, Rocket Pharmaceuticals announced that the U.S. FDA cleared its Investigational New Drug application for RP-A701, a first-in-class gene therapy for BAG3-associated dilated cardiomyopathy. The company said Phase 1 trial start-up activities were underway and that it was working toward treating the first patient.
- In March 2025, Kardigan acquired Prolaio, a clinical intelligence company focused on cardiovascular research and real-world patient data, expanding Kardigan’s broader heart-health capabilities. Kardigan later said its late-stage pipeline includes programs targeting specific types of dilated cardiomyopathy, linking the acquisition to its DCM-focused development strategy.
- In October 2024, Bayer entered an exclusive licensing agreement with Dewpoint Therapeutics for a disease-modifying dilated cardiomyopathy program aimed at patients with specific mutations. Bayer said the deal gives it global rights to develop and commercialize the program, while Dewpoint remains involved through the broader cardiovascular and renal collaboration.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 5,240.95 million |
| Revenue forecast in 2032 | USD 8,025.37 million |
| Growth rate (CAGR) | 7.36% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026–2032 |
| Quantitative units | USD million |
| Segments covered | By Therapy Type Outlook: Pharmacological Therapy, Device-based Therapy, Surgical Interventions, Others; By Drug Class Outlook: ACE Inhibitors, Beta Blockers, ARBs, Aldosterone Antagonists, Others; By Device Type Outlook: ICDs, CRT Devices, Ventricular Assist Devices, Others; By Disease Stage Outlook: Early-stage DCM, Advanced DCM, End-stage Heart Failure, Others; By End User Outlook: Hospitals, Cardiac Specialty Centers, Homecare, Others |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Novartis; AstraZeneca; Pfizer; Bayer; Boehringer Ingelheim; Medtronic; Abbott; Boston Scientific; Bristol Myers Squibb; Merck & Co. |
| No. of Pages | 334 |
Segmentation
By Therapy Type
- Pharmacological Therapy
- Device-based Therapy
- Surgical Interventions
- Others
By Drug Class
- ACE Inhibitors
- Beta Blockers
- ARBs
- Aldosterone Antagonists
- Others
By Device Type
- ICDs
- CRT Devices
- Ventricular Assist Devices
- Others
By Disease Stage
- Early-stage DCM
- Advanced DCM
- End-stage Heart Failure
- Others
By End User
- Hospitals
- Cardiac Specialty Centers
- Homecare
- Others
By Region
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of guideline-directed therapy pathways
Broader adoption of standardized care models ensures earlier initiation and consistent titration of multi-class regimens, increasing therapy duration and recurring utilization across both drug and device pathways.
Earlier diagnosis and improved care access
Advances in imaging and diagnostic protocols enable earlier identification of dilated cardiomyopathy, expanding the treated patient pool and supporting longer-term therapy exposure and follow-up adherence.
Growth of specialized cardiac programs
The proliferation of multidisciplinary heart-failure clinics and specialist-led care improves medication optimization, device evaluation, and longitudinal monitoring, driving higher engagement and therapy persistence.
Technology-enabled monitoring and workflow integration
Remote monitoring and digital follow-up tools facilitate adherence, early detection of decompensation, and therapy optimization, expanding the addressable population for home-based management and supporting comprehensive care pathways.
Innovation in device and advanced intervention pathways
Development and adoption of advanced devices such as ICDs, CRTs, and gene therapies for specific DCM subtypes provide new treatment options for high-risk and advanced-stage patients, supporting market growth through differentiated clinical outcomes.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Dilated Cardiomyopathy Therapeutic Market in 2025 and 2032?
What is the CAGR for the Dilated Cardiomyopathy Therapeutic Market during 2025–2032?
What is the largest segment in the Dilated Cardiomyopathy Therapeutic Market?
What factors are driving growth in the Dilated Cardiomyopathy Therapeutic Market?
Which companies are covered in the Dilated Cardiomyopathy Therapeutic Market competitive analysis?
Which region leads the Dilated Cardiomyopathy Therapeutic Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Hospitals
- 1.2.2 Cardiac Specialty Centers
- 1.2.3 Homecare
- 1.2.4 Others
- 1.3 By Drug Class
- 1.3.1 ACE Inhibitors
- 1.3.2 Beta Blockers
- 1.3.3 ARBs
- 1.3.4 Aldosterone Antagonists
- 1.3.5 Others
- 1.4 By Device Type
- 1.4.1 ICDs
- 1.4.2 CRT Devices
- 1.4.3 Ventricular Assist Devices
- 1.4.4 Others
- 1.5 By Therapy Type
- 1.5.1 Pharmacological Therapy
- 1.5.2 Device-based Therapy
- 1.5.3 Surgical Interventions
- 1.5.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 5,240.95 million → 2032: USD 8,025.37 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Dilated Cardiomyopathy Therapeutics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Dilated Cardiomyopathy Therapeutics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Dilated Cardiomyopathy Therapeutics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Dilated Cardiomyopathy Therapeutics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Dilated Cardiomyopathy Therapeutics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Dilated Cardiomyopathy Therapeutics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Dilated Cardiomyopathy Therapeutics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Dilated Cardiomyopathy Therapeutics Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 5,240.95 million → 2032: USD 8,025.37 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Dilated Cardiomyopathy Therapeutics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2025-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2025-2032
- 12.3.4 Volume Forecast, 2025-2032
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Cardiac Specialty Centers
- 12.3.7.3 Homecare
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Drug Class - Market Size and Forecast, 2025-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2025-2032
- 12.4.4 Volume Forecast, 2025-2032
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 ACE Inhibitors
- 12.4.7.2 Beta Blockers
- 12.4.7.3 ARBs
- 12.4.7.4 Aldosterone Antagonists
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Device Type - Market Size and Forecast, 2025-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2025-2032
- 12.5.4 Volume Forecast, 2025-2032
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 ICDs
- 12.5.7.2 CRT Devices
- 12.5.7.3 Ventricular Assist Devices
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Therapy Type - Market Size and Forecast, 2025-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2025-2032
- 12.6.4 Volume Forecast, 2025-2032
- 12.6.5 Base-Year Market Share, 2025
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Pharmacological Therapy
- 12.6.7.2 Device-based Therapy
- 12.6.7.3 Surgical Interventions
- 12.6.7.4 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Dilated Cardiomyopathy Therapeutics End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Dilated Cardiomyopathy Therapeutics Geographic Market Outlook, 2025-2032
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Dilated Cardiomyopathy Therapeutics Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Dilated Cardiomyopathy Therapeutics Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Novartis
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 AstraZeneca
- 18.4 Pfizer
- 18.5 Bayer
- 18.6 Boehringer Ingelheim
- 18.7 Medtronic
- 18.8 Abbott
- 18.9 Boston Scientific
- 18.10 Bristol Myers Squibb
- 18.11 Merck & Co.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

