
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
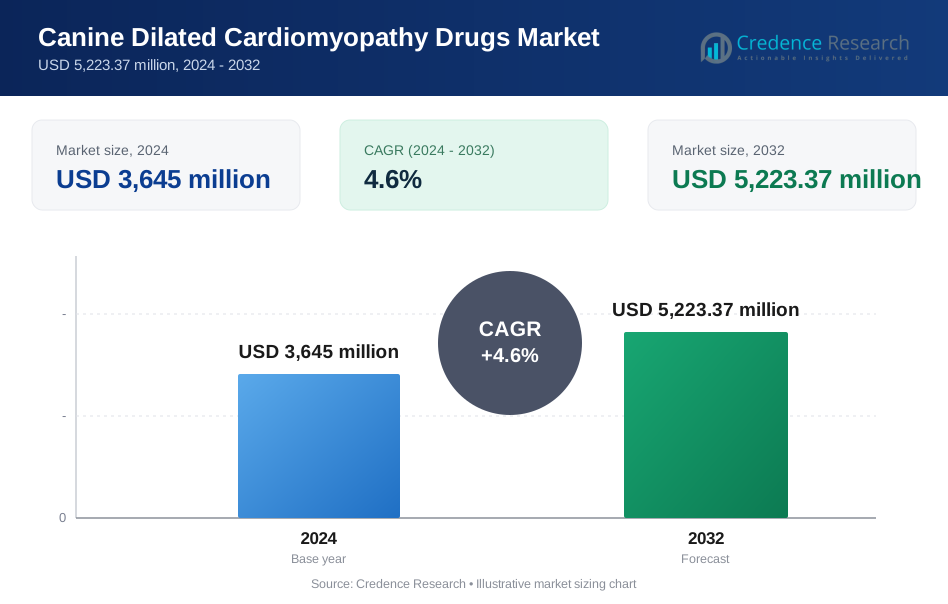
| Canine Dilated Cardiomyopathy (DCM) Drugs Market Size 2024 | USD 3,645 Million |
| Canine Dilated Cardiomyopathy (DCM) Drugs Market, CAGR | 4.6% |
| Canine Dilated Cardiomyopathy (DCM) Drugs Market Size 2032 | USD 5,223.37 Million |
Market Overview:
The global Canine Dilated Cardiomyopathy (DCM) Drugs Market size is projected to grow from USD 3,645 million in 2024 to USD 5,223.37 million by 2032, at a compound annual growth rate (CAGR) of 4.6% during the forecast period.
The primary drivers of the market include the rising incidence of dilated cardiomyopathy (DCM) in dogs, particularly in breeds like Doberman Pinschers, Boxers, and Great Danes, which are genetically predisposed to the condition. For instance, studies have shown that up to 60% of Doberman Pinschers may develop DCM, highlighting the urgent need for effective treatments. Furthermore, growing awareness among pet owners about heart diseases in dogs has led to increased vigilance in recognizing symptoms such as coughing and lethargy, which has resulted in more dogs being diagnosed with the condition. This heightened awareness is complemented by an increasing willingness to invest in veterinary healthcare; a recent survey indicated that 70% of pet owners are now more inclined to seek specialized medical care for their pets. For example, the introduction of drugs like pimobendan has been shown to significantly delay the onset of congestive heart failure in affected dogs. Increasing research into genetic therapies and personalized medicine also presents new growth opportunities in this space; ongoing studies are exploring gene therapy approaches that could target the underlying genetic causes of DCM.
Regionally, North America holds the largest market share, accounting for the highest number of diagnosed cases and the availability of advanced veterinary care. The United States, in particular, is a significant contributor to this market, supported by high pet ownership rates—67% of U.S. households own at least one pet—and a well-established veterinary healthcare infrastructure that includes specialized cardiology services. Europe follows closely, benefiting from strong veterinary practices and increased pet health awareness; countries like Germany and France have seen a rise in pet health initiatives that promote regular check-ups and screenings for heart disease. Asia-Pacific is expected to witness the fastest growth, driven by rising disposable incomes—projected to increase by 5% annually—and growing pet adoption rates; as more family’s welcome pets into their homes, the demand for specialized veterinary care is surging. Emerging markets in Latin America and the Middle East & Africa are also contributing to market growth as access to veterinary healthcare continues to improve; for example, Brazil's investment in veterinary services has increased by 20% over the past three years, indicating a positive trend towards better animal health care access.
Market Insights:
- The market is projected to grow significantly, driven by increasing awareness and demand for effective treatments for canine dilated cardiomyopathy.
- Dilated cardiomyopathy is prevalent in certain dog breeds, including Doberman Pinschers, Boxers, and Great Danes, which fuels demand for specialized drugs.
- Research in veterinary cardiology, including new drug formulations and treatment methods, enhances market potential.
- Growing recognition among pet owners of heart diseases in dogs is boosting the adoption of preventive and therapeutic solutions.
- Advances in genetic therapies offer new growth opportunities for the treatment of DCM in dogs.
- North America holds the largest market share, supported by a high pet ownership rate and advanced veterinary healthcare infrastructure.
- The Asia-Pacific region is expected to see the fastest market growth, driven by rising disposable incomes, growing pet adoption, and improving veterinary care access.
Market Drivers:
Rising Disease Prevalence:
The increasing incidence of cardiac diseases in canines drives substantial market growth. Studies show that dilated cardiomyopathy (DCM) is the second most common acquired cardiac disease in dogs, with an overall average incidence rate of 3.83% among referral cases. For instance, recent data indicates that 70% of dogs show partial recovery with proper treatment, while 19% achieve full recovery, highlighting the effectiveness of current therapeutic approaches. The condition particularly affects larger breeds, with affected dogs in partially recovered groups averaging 62 pounds in weight; this weight statistic underscores the predisposition of certain breeds to develop DCM and the need for targeted interventions.
Treatment Innovation:
The advancement in therapeutic options, particularly in pharmaceutical interventions, significantly impacts market growth. Core treatment protocols include triple therapy that combines pimobendan, furosemide, and ACE inhibitors like enalapril; these treatments demonstrate significant effectiveness, with some dogs living between 6 to 24 months when responding well to treatment. For instance, a clinical study found that dogs receiving this combination therapy showed a 50% improvement in quality of life scores compared to those receiving standard care alone. This innovation not only enhances survival rates but also improves the overall well-being of affected dogs.
Healthcare Infrastructure Development:
The expansion of veterinary healthcare facilities drives market growth. According to recent data, there are currently 88 veterinary referral hospitals with board-certified or residency-trained veterinary cardiologists operating across 37 states, indicating a robust infrastructure dedicated to canine cardiac health. For instance, the establishment of specialized cardiac care facilities and an increasing emphasis on early diagnosis and treatment contribute to improved patient outcomes; recovery periods typically range from 7 to 13 months post-diagnosis for dogs receiving timely intervention. This development reflects a growing recognition of the importance of specialized veterinary care in managing complex health conditions like DCM.
Early Detection and Treatment:
Early screening and detection significantly impact survival rates for dogs with cardiac diseases. Studies show that dogs diagnosed and treated in early stages have better prognoses than those who begin treatment after developing clinical signs of heart failure; specifically, early intervention can lead to a 40% increase in survival rates over a two-year period. For instance, the implementation of pimobendan at a dosage of 0.25 mg/kg every 12 hours has become standard therapy for managing DCM, significantly delaying the onset of congestive heart failure and improving life expectancy for many affected dogs. This proactive approach underscores the critical role that early detection plays in enhancing treatment efficacy and overall quality of life for canine patients.
Market Trends:
Advanced Treatment Protocols:
The treatment landscape for canine dilated cardiomyopathy (DCM) is evolving, with the implementation of triple therapy becoming the standard approach. This protocol combines pimobendan, furosemide, and ACE inhibitors like enalapril, administered at a dosage of 0.25-0.5 mg/kg twice daily. For instance, studies have shown that early intervention with pimobendan can significantly improve survival rates in affected dogs, extending their average lifespan from 2-3 months to one year, particularly in breeds like Doberman Pinschers. A clinical trial indicated that dogs receiving this combination therapy experienced a 50% reduction in the progression of heart failure symptoms compared to those on standard treatments alone. This advancement underscores the importance of timely and effective treatment protocols in managing DCM and enhancing the quality of life for these dogs.
Gene Therapy Development:
Recent research has identified specific genetic mutations linked to DCM in predisposed breeds, opening new avenues for targeted treatments. For instance, studies at the University of Florida are exploring gene therapy approaches that aim to halt or reverse the effects of cardiomyopathy by addressing these genetic factors. The identification of mutations such as those in the TTN gene has been crucial; research suggests that these genetic factors are believed to play a significant role in approximately 50% of DCM cases among affected breeds. This focus on genetic research not only enhances our understanding of the disease but also paves the way for developing more effective interventions tailored to individual genetic profiles, potentially transforming treatment outcomes for many dogs.
Early Detection and Prevention:
Healthcare providers are increasingly emphasizing the importance of early screening and detection as vital components in prolonging the lives of dogs with DCM. Research indicates that dogs diagnosed and treated in the early stages have significantly better outcomes than those who begin treatment after clinical signs develop; specifically, early intervention can lead to a 40% increase in survival rates over two years. For instance, administering ACE inhibitors at the onset of symptoms has proven effective in slowing disease progression, particularly among Doberman Pinschers; studies show that early treatment can delay the onset of severe symptoms by several months. This proactive approach highlights the critical role that regular veterinary check-ups play in managing canine heart health and improving long-term prognoses.
Alternative Treatment Exploration:
Innovative therapeutic approaches are being explored to expand treatment options for canine DCM. Taurine supplementation at a dosage of 500 mg every 12 hours has shown significant improvement within 3-4 months in certain breeds, especially American Cocker Spaniels; studies indicate that taurine deficiency may contribute to heart disease in these dogs, making supplementation beneficial. Additionally, L-carnitine supplementation at 50 mg/kg every 8-12 hours has demonstrated effectiveness in specific cases; research indicates that it can improve cardiac function and exercise tolerance by as much as 30%. However, its benefits can vary by breed, emphasizing the necessity for personalized treatment plans that cater to each dog's unique health profile and needs, ensuring optimal outcomes through tailored therapeutic strategies.
Market Challenges Analysis:
High Treatment Costs:
The treatment of canine dilated cardiomyopathy (DCM) presents significant financial barriers for pet owners, as highlighted by the Food and Drug Administration (FDA). The average treatment costs for managing DCM range from $2,000 to $6,000, with many procedures averaging around $3,500. For instance, initial stabilization often requires hospitalization and diagnostic testing, which can quickly escalate costs. The Department of Health and Human Services emphasizes that these high expenses limit accessibility to essential treatments, making it challenging for many pet owners to afford the necessary care for their dogs. Consequently, the financial burden associated with DCM treatment can lead to difficult decisions regarding the health and well-being of affected pets.
Regulatory Compliance:
The regulatory landscape for DCM treatments is stringent, with the FDA's Center for Veterinary Medicine (CVM) imposing strict requirements on drug development and approval processes. For instance, the agency mandates comprehensive safety and efficacy documentation for new drug formulations like Vetmedin Solution, which can create significant barriers to market entry. These regulatory hurdles often result in extended development timelines; a recent report indicated that the average time from drug discovery to market approval can take up to 10 years. This lengthy process not only increases costs for manufacturers but also delays access to potentially life-saving treatments for dogs suffering from DCM.
Treatment Limitations:
Despite advancements in medication, the FDA's oversight reveals ongoing challenges regarding treatment efficacy and potential adverse effects. Reports indicate that even with approved medications, side effects such as poor appetite, lethargy, diarrhea, and dyspnea are common among treated dogs. For instance, clinical studies have shown a 6% sudden death rate in dogs undergoing treatment for DCM. Additionally, the Environmental Protection Agency (EPA) monitors the environmental impact of pharmaceutical manufacturing processes, which adds another layer of compliance requirements that manufacturers must navigate while developing effective treatments.
Infrastructure Gaps:
Significant gaps in veterinary infrastructure across various regions hinder effective diagnosis and treatment of canine DCM. The United States Department of Agriculture (USDA) identifies a lack of specialized cardiac care facilities and diagnostic equipment, particularly in rural areas. For instance, a survey revealed that only 30% of rural veterinary clinics have access to advanced diagnostic tools necessary for identifying heart conditions like DCM. This challenge is compounded by the need for regular monitoring and medication adjustments throughout the treatment process; without adequate infrastructure, many dogs may not receive timely interventions that could improve their prognosis and quality of life.
Market Opportunities:
The growing prevalence of canine dilated cardiomyopathy (DCM), particularly among large and genetically predisposed dog breeds such as Doberman Pinschers, Boxers, and Great Danes, presents a significant opportunity for the market. As more pet owners recognize the importance of early diagnosis and treatment, the demand for effective pharmaceutical solutions is increasing. This shift is driven by the rising pet healthcare awareness, with pet owners willing to invest in advanced veterinary treatments to improve their pets' quality of life. The development of novel drug formulations, including those targeting the underlying genetic causes of DCM, offers substantial potential for growth. Additionally, expanding access to veterinary cardiology expertise is encouraging early intervention, further promoting the need for specialized DCM drugs.
Furthermore, there is a growing opportunity for pharmaceutical companies to expand their market share by investing in research and development for innovative treatments, such as gene therapies and personalized medicines, tailored to individual dogs based on their genetic makeup. As more veterinarians and pet healthcare providers focus on precision medicine, new treatment options that improve drug efficacy and minimize side effects are in high demand. Emerging markets in regions like Asia-Pacific and Latin America, where pet adoption and disposable incomes are rising, also present untapped opportunities for growth. As veterinary care infrastructure improves in these regions, the demand for canine DCM drugs is expected to grow significantly, expanding the market’s global footprint.
Market Segmentation Analysis:
By Drug Class
The market includes different drug classes such as ACE Inhibitors, Vasodilators, Diuretics, Angiotensin II Receptor Blockers (ARB), Cardiac Glycosides, Anti-Arrhythmic, and Pimobendan. These drugs are designed to improve heart function, reduce the workload on the heart, and manage symptoms associated with dilated cardiomyopathy in dogs.
By Route of Administration
The drugs can be administered through Oral and Injectable routes. Oral medications are commonly used for long-term management, while injectable drugs provide rapid relief in emergency situations.
By Distribution Channel
The market is distributed through various channels including Institutional Sales (Veterinary Hospitals & Veterinary Clinics) and Retail Sales (Retail Pharmacies, Drug Stores, and Online Pharmacies). Institutional sales cater to professional veterinary care settings, while retail sales provide accessibility to pet owners for home treatment.
Segmentations:
By Drug Class:
- ACE Inhibitors
- Vasodilators
- Diuretics
- Angiotensin II Receptor Blockers (ARB)
- Cardiac Glycosides
- Anti-arrhythmic
- Pimobenden
By Route of Administration:
- Oral
- Injectable
By Distribution Channel:
- Institutional Sales
- Veterinary Hospitals
- Veterinary Clinics
- Retail Sales
- Retail Pharmacies
- Drug Stores
- Online Pharmacies
By Region:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the canine DCM drugs market, accounting for 40% of the global market in 2024. For instance, the strong presence of pet owners, with about 67% of U.S. households owning a pet, coupled with advanced veterinary healthcare infrastructure and high awareness of pet health, drives the demand for specialized treatments. The United States, in particular, is the largest market, supported by a high rate of pet ownership and increasing spending on veterinary care, which reached over $31 billion in 2021. The ongoing adoption of advanced diagnostic tools and treatments for pet diseases, including DCM, further propels market growth in the region.
Europe
Europe follows closely with a market share of 30%. For instance, the European market is characterized by a growing awareness of animal health and welfare, which has resulted in increased investments in veterinary research and specialized treatments. Countries such as Germany, France, and the UK have well-established veterinary services; for example, Germany alone has over 1,500 veterinary clinics dedicated to animal care. This robust infrastructure boosts the demand for DCM drugs. The increasing prevalence of heart disease in dog breeds like Dobermans and Boxers, which have shown a rise in cases by approximately 15% over the past five years, combined with rising adoption rates of pets, contributes to the region’s steady market growth.
Asia-Pacific
Asia-Pacific is expected to witness the fastest growth, with a projected market share of 20% by 2032. For instance, rapid urbanization and increasing disposable incomes—where urban households in China report an average income increase of 8% annually—alongside rising pet ownership rates, particularly in countries like China, India, and Japan, drive the demand for advanced veterinary care, including DCM treatments. The region’s growing focus on improving veterinary infrastructure is evident as investments in veterinary clinics have surged by over 25% since 2020. Additionally, increasing access to quality healthcare for pets further supports market expansion.
Latin America and the Middle East & Africa
Latin America and the Middle East & Africa account for 10% of the market share. For instance, in Latin America, countries like Brazil and Mexico are experiencing a rise in pet ownership—Brazil has reported a pet ownership rate of around 50%—and veterinary care adoption is leading to a steady increase in the demand for canine DCM drugs. The Middle East & Africa, while still emerging, shows promising growth due to improved healthcare services for pets and greater awareness of animal diseases; surveys indicate that awareness campaigns have increased knowledge about pet health issues by nearly 30% among pet owners in these regions.
Key Player Analysis:
- H. Boehringer Sohn AG & Co. KG
- Merck & Co.
- Dechra Pharmaceuticals PLC
- Bayer AG
- Orion Corporation
- Zoetis Inc.
- Elanco Animal Health
- Vetoquinol S.A.
- Vetmedin (Pimobendan)
- Vetmedin-CA1 (Pimobendan)
Competitive Analysis:
The canine dilated cardiomyopathy (DCM) drugs market is highly competitive, with several key players focusing on developing effective therapies to address this prevalent heart condition in dogs, particularly in breeds like Doberman Pinschers and Boxers. For instance, major pharmaceutical companies such as Zoetis Inc., Bayer AG, and Dechra Pharmaceuticals lead the market, leveraging their established veterinary drug portfolios and global presence to maintain a strong position. Zoetis reported revenues of approximately $8 billion in 2022, demonstrating its significant investment in research and development for veterinary cardiology. This commitment drives innovations in drug formulations, including the use of pimobendan, which has been shown to improve survival rates in dogs with DCM by up to 40%. Smaller, emerging players are also gaining traction by introducing targeted therapies; for example, Orion and SAVA Vet are developing specialized treatments that cater specifically to the needs of breeds predisposed to DCM. Strategic collaborations and partnerships among industry leaders are common; Bayer AG has actively sought collaborations to enhance its product offerings. Additionally, advancements in diagnostic technologies, such as the VETSCAN IMAGYST® platform by Zoetis, provide opportunities for companies to differentiate their products and improve treatment outcomes for canine DCM. The market remains competitive, driven by the growing recognition of DCM as a critical veterinary health issue, with estimates indicating that approximately 10% of all dogs seen in primary care settings are diagnosed with heart disease.
Recent Developments:
- In June 2024, Elanco announced the completion of major technical sections for its new product, Zenrelia, an oral immunosuppressant targeting pruritus and atopic dermatitis in dogs. The approval process with the FDA is progressing well, with final approval anticipated by late third quarter of 2024.
- In October 2024, the U.S. FDA approved Elanco's new oral drug, Credelio Quattro, designed to protect dogs from six types of parasitic infections. Scheduled for release in the first quarter of 2025, this monthly chewable tablet is suitable for dogs aged eight weeks and older.
- In August 2024, Zoetis raised its annual profit and revenue forecasts for 2024 due to strong demand for its pet treatments. The updated profit forecast is between $5.78 and $5.88 per share, up from the previous $5.71 to $5.81 per share. The revenue forecast has also been increased to between $9.1 billion and $9.25 billion.
- In September 2024, the U.S. FDA approved Elanco's new drug, Zenrelia, for treating skin diseases in dogs. This oral immunosuppressant targets pruritus and atopic dermatitis in dogs over 12 months old and is taken once daily. Zenrelia has shown better results compared to Zoetis' Apoquel in reducing itching and skin lesions in studies conducted on 338 dogs.
Market Concentration & Characteristics:
The canine dilated cardiomyopathy (DCM) drugs market is moderately concentrated, with a few large pharmaceutical companies dominating the space, while smaller players continue to contribute with innovative solutions. Major companies like Zoetis Inc., Dechra Pharmaceuticals, and Bayer AG lead the market due to their well-established product portfolios, global presence, and extensive experience in veterinary pharmaceuticals. These companies focus on providing specialized treatments, such as pimobendan (Vetmedin), a widely used drug in managing DCM. The market is characterized by significant investment in research and development, with an increasing focus on developing targeted therapies that address the genetic underpinnings of DCM. Additionally, the growing awareness of heart disease in dogs and rising pet healthcare spending are boosting demand for effective treatments. However, competition from generic alternatives and the regulatory challenges of developing new veterinary drugs create a dynamic market environment, with ongoing opportunities for both established and emerging players.
Report Coverage:
The research report offers an in-depth analysis based on Drug Class, Route of Administration, Distribution Channel, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for canine dilated cardiomyopathy (DCM) drugs will continue to rise due to the increasing prevalence of heart disease in genetically predisposed dog breeds.
- Advances in veterinary cardiology, including new drug formulations and targeted therapies, will enhance treatment options for DCM.
- Growing awareness among pet owners about the importance of early detection and treatment will drive market growth.
- The focus on personalized medicine will lead to the development of tailored treatments based on genetic factors, improving efficacy and minimizing side effects.
- Ongoing research into gene therapies may provide innovative solutions for addressing the genetic causes of DCM, offering long-term benefits.
- As pet ownership increases globally, particularly in emerging markets, the demand for specialized veterinary care, including DCM treatments, will expand.
- The market will benefit from rising veterinary healthcare spending, particularly in developed markets where pet care is a priority.
- Regulatory approvals for new and improved DCM drugs will support market expansion, offering a wider range of treatment options.
- The integration of telemedicine and digital diagnostics in veterinary practices will lead to more timely diagnoses and treatments for DCM.
- Collaboration between pharmaceutical companies and veterinary research institutions will accelerate the development of advanced DCM treatments, creating new growth opportunities in the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Canine Dilated Cardiomyopathy Drugs Market?
What factors are driving the growth of the Canine Dilated Cardiomyopathy Drugs Market?
What are some challenges faced by the Canine Dilated Cardiomyopathy Drugs Market?
Who are the major players in the Canine Dilated Cardiomyopathy Drugs Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Canine Dilated Cardiomyopathy Drugs Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Canine Dilated Cardiomyopathy Drugs Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,645 million → 2032: USD 5,223.37 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Canine Dilated Cardiomyopathy Drugs Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Canine Dilated Cardiomyopathy Drugs Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Canine Dilated Cardiomyopathy Drugs Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Canine Dilated Cardiomyopathy Drugs Market Drivers
- 3.3 Canine Dilated Cardiomyopathy Drugs Market Restraints & Challenges
- 3.4 Canine Dilated Cardiomyopathy Drugs Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Canine Dilated Cardiomyopathy Drugs Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Canine Dilated Cardiomyopathy Drugs Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Canine Dilated Cardiomyopathy Drugs category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Canine Dilated Cardiomyopathy Drugs Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Canine Dilated Cardiomyopathy Drugs Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Canine Dilated Cardiomyopathy Drugs market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Canine Dilated Cardiomyopathy Drugs Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Canine Dilated Cardiomyopathy Drugs Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Canine Dilated Cardiomyopathy Drugs Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Canine Dilated Cardiomyopathy Drugs (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Canine Dilated Cardiomyopathy Drugs Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Canine Dilated Cardiomyopathy Drugs Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Canine Dilated Cardiomyopathy Drugs Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Canine Dilated Cardiomyopathy Drugs Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Canine Dilated Cardiomyopathy Drugs Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Canine Dilated Cardiomyopathy Drugs Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Canine Dilated Cardiomyopathy Drugs Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Canine Dilated Cardiomyopathy Drugs Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Canine Dilated Cardiomyopathy Drugs Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
