
Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Overview:
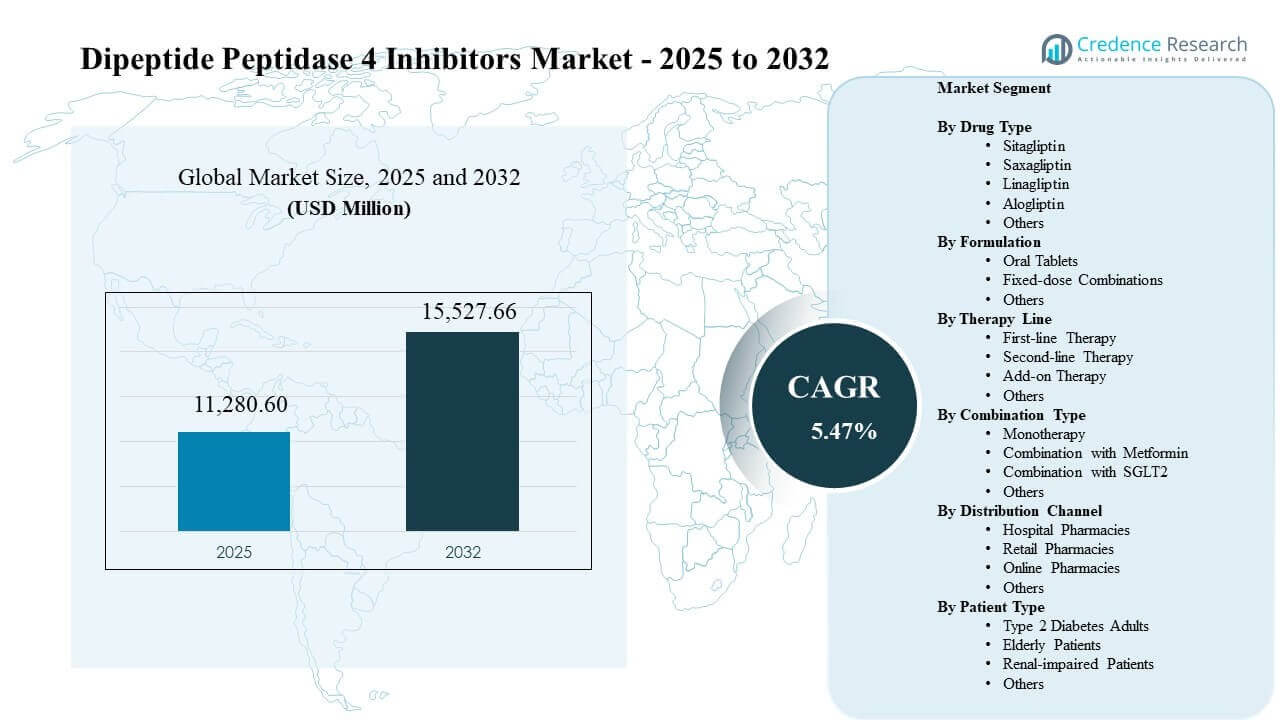
The Dipeptide Peptidase 4 (DPP-4) Inhibitors Market size was estimated at USD 11,280.60 million in 2025 and is expected to reach USD 15,527.66 million by 2032, growing at a CAGR of 5.47% from 2025 to 2032. Demand momentum is supported by sustained type 2 diabetes prevalence and the continued clinical role of oral glucose-lowering therapies for patients who need weight-neutral options with low hypoglycemia risk. Dipeptide Peptidase 4 (DPP-4) Inhibitors Market activity remains strongest in mature reimbursement settings, while volume growth is increasingly shaped by generics, fixed-dose combinations, and channel expansion in emerging economies.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2021-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Size 2025 | USD 11,280.60 million |
| Dipeptide Peptidase 4 (DPP-4) Inhibitors Market, CAGR | 5.47% |
| Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Size 2032 | USD 15,527.66million |
Key Market Trends & Insights
- Dipeptide Peptidase 4 (DPP-4) Inhibitors Market revenue totaled USD 11,280.60 million in 2025 and is projected to reach USD 15,527.66 million by 2032.
- The Dipeptide Peptidase 4 (DPP-4) Inhibitors Market is forecast to expand at a 5.47% CAGR during 2025–2032, reflecting steady chronic-therapy demand.
- Sitagliptin led By Drug Type with a 36.9% share in 2025, supported by deep prescribing familiarity and broad availability.
- Retail Pharmacies led By Distribution Channel with a 44.8% share in 2025, reflecting repeat-refill behavior for long-term oral regimens.
- North America accounted for 37.8% of Dipeptide Peptidase 4 (DPP-4) Inhibitors Market revenue in 2025, reinforcing the role of reimbursement depth and diagnosis rates.
Segment Analysis
Dipeptide Peptidase 4 (DPP-4) Inhibitors Market segmentation is shaped by molecule selection, regimen design, and the point of dispensing that best supports chronic adherence. Oral-first behavior keeps demand anchored in outpatient settings where routine monitoring and refill cycles can be maintained. Prescriber selection commonly prioritizes tolerability and low hypoglycemia risk for patients who require incremental control without complex titration. Competitive intensity increases as legacy brands face broader generic participation and as therapy decisions incorporate payer rules.
Demand patterns also reflect where Dipeptide Peptidase 4 (DPP-4) Inhibitors Market usage sits within treatment sequencing. Utilization has expanded over time as oral antidiabetic options broadened, with increased adult use. Channel dynamics increasingly favor retail access for stable patients, while hospitals remain relevant for initiation in comorbid cases and for regimen optimization during admissions. Fixed-dose combinations remain strategically important because lower pill burden can support persistence.
By Drug Type Insights
Sitagliptin accounted for the largest share of 36.9% in 2025. Dipeptide Peptidase 4 (DPP-4) Inhibitors Market leadership for sitagliptin is reinforced by long-standing physician familiarity in primary care diabetes management and broad availability across markets. Formularies often retain sitagliptin options due to established clinical comfort and predictable tolerability. Generic participation and wide dispensing access support continued volume even as competition increases across newer classes.
By Formulation Insights
Dipeptide Peptidase 4 (DPP-4) Inhibitors Market demand remains centered on oral formulations because daily dosing aligns with chronic therapy behavior and supports routine adherence. Fixed-dose combinations gain traction where payer pathways favor simplified regimens and where clinicians target reduced pill burden. Formulation selection is strongly influenced by affordability, availability of combinations, and local reimbursement rules. Pharmacy substitution practices can further steer volume toward commonly stocked oral presentations.
By Therapy Line Insights
Dipeptide Peptidase 4 (DPP-4) Inhibitors Market use varies by guideline positioning and payer sequencing, with many health systems using the class as a step-up option when baseline regimens do not achieve targets. Second-line and add-on use is supported by tolerability priorities in patients who need incremental glucose control. Provider decision-making often weighs comorbidities, risk of hypoglycemia, and patient preference for oral therapy. Therapy-line mix can shift as coverage expands for competing classes and as generics reshape affordability.
By Combination Type Insights
Dipeptide Peptidase 4 (DPP-4) Inhibitors Market combination demand is influenced by stepwise intensification patterns and the need to balance efficacy with tolerability. Combination with metformin remains common where complementary mechanisms and guideline pathways support escalation from first-line therapy. Combination approaches can be favored when clinicians seek improved control without adding injection complexity. Availability of fixed-dose products and payer rules often determine which combination types scale fastest.
By Distribution Channel Insights
Retail Pharmacies accounted for the largest share of 44.8% in 2025. Dipeptide Peptidase 4 (DPP-4) Inhibitors Market concentration in retail channels reflects stable outpatient management, frequent refills, and broad neighborhood access that supports adherence. Retail dispensing also benefits from substitution dynamics as generics expand and payers encourage lower-cost options. Prescription renewal workflows and chronic disease monitoring programs can further reinforce retail volume concentration.
By Patient Type Insights
Dipeptide Peptidase 4 (DPP-4) Inhibitors Market demand is anchored in adults with type 2 diabetes because long-term oral management creates steady refill-driven utilization. Elderly patient demand is supported by tolerability preferences and treatment goals that prioritize safety and simple dosing. Renal impairment considerations can influence molecule selection and dosing decisions, shaping physician choice within the class. Patient-type mix is also shaped by diagnosis rates, access to routine monitoring, and payer coverage differences.
Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Drivers
Expanding Type 2 Diabetes Burden and Chronic Therapy Demand
Rising type 2 diabetes prevalence supports sustained prescribing for oral glucose-lowering therapies across primary care and specialty clinics. Dipeptide Peptidase 4 (DPP-4) Inhibitors Market demand benefits from the chronic nature of treatment, which creates recurring prescription cycles and consistent pharmacy throughput. Clinical decision-making often prioritizes tolerability and safety for long-duration use, supporting continued role for DPP-4 inhibitors in selected patients. Health system screening and diagnosis improvements also expand the treated pool.
- For instance, Merck’s TECOS study of sitagliptin enrolled 14,724 participants across 38 countries, followed patients for a median of about three years, and met its primary cardiovascular non-inferiority endpoint with no increase in hospitalization for heart failure versus placebo, reinforcing the class’s role in long-duration therapy selection.
Preference for Oral, Low-Complexity Regimens
Patient preference for oral administration strengthens adoption and persistence in long-term diabetes care pathways. Dipeptide Peptidase 4 (DPP-4) Inhibitors Market utilization is supported where clinicians and patients favor weight-neutral profiles and low hypoglycemia risk relative to some alternatives. Oral dosing reduces training needs and can ease integration into daily routines, improving adherence for patients managing multiple comorbidities. Formulary access to affordable oral options further accelerates uptake in cost-sensitive markets.
- For instance, Boehringer Ingelheim and Eli Lilly’s Trajenta (linagliptin) is administered at 5 mg once daily, and EMA data show a 0.64% HbA1c reduction versus placebo at 24 weeks as add-on to metformin, while the CAROLINA study reported moderate or severe hypoglycemia in 6.5% of linagliptin-treated patients versus 30.9% with glimepiride and severe hypoglycemia in 0.3% versus 2.2%
Generics, Substitution, and Access Expansion
Loss of exclusivity and increasing generic availability broadens affordability and expands access in both mature and emerging markets. Dipeptide Peptidase 4 (DPP-4) Inhibitors Market volumes can rise even when branded revenue pressure increases, particularly where payer policies encourage substitution. Wider supplier bases improve continuity of supply and support broader retail availability. Lower-cost access also enables earlier treatment intensification for eligible patients in systems with tight cost-containment priorities.
Retail Channel Reach and Refill Infrastructure
Retail pharmacy networks support recurring access for chronic therapy, reinforcing refill-driven demand patterns. Dipeptide Peptidase 4 (DPP-4) Inhibitors Market distribution benefits from established prescription processing, insurance adjudication, and patient reminder workflows that reduce missed refills. High geographic coverage improves convenience, particularly in urban and peri-urban settings. As e-pharmacy and home delivery expand, refill reliability can improve further, supporting persistence and stable therapy continuation.
Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Challenges
Dipeptide Peptidase 4 (DPP-4) Inhibitors Market growth faces competitive pressure from alternative diabetes drug classes that can offer stronger weight-loss benefits or broader cardiometabolic positioning in selected populations. Payer policies increasingly steer patients toward preferred therapies based on outcomes expectations and total cost-of-care considerations. As generic penetration rises, revenue per prescription can decline, intensifying pricing pressure across brands and channel partners. Portfolio differentiation becomes harder when molecule-level clinical differences are modest for many patients.
- For instance, Eli Lilly reported in the 40-week SURPASS-2 study that tirzepatide 15 mg reduced HbA1c by 2.46% and body weight by 11.2 kg, and 60% of patients on that dose reached HbA1c at or below 6.5% with at least 10% weight loss without clinically significant hypoglycemia, highlighting the performance gap DPP-4 inhibitors face against newer incretin-based therapies.
Dipeptide Peptidase 4 (DPP-4) Inhibitors Market demand can be constrained by variable reimbursement and uneven diagnostic access across lower-income regions. Treatment sequencing rules and prior authorization requirements may delay initiation or limit switching flexibility. Supply reliability and quality compliance expectations can create barriers for smaller manufacturers and can influence tender outcomes. Provider inertia and switching costs also slow regimen changes in stable patients, which can limit rapid share gains for newer combinations or entrants.
Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Trends and Opportunities
Dipeptide Peptidase 4 (DPP-4) Inhibitors Market opportunities are increasing around fixed-dose combinations and regimen simplification strategies that can improve persistence. Combination design can reduce pill burden and align with stepwise intensification pathways, supporting broader use in outpatient settings. Retail and digital dispensing models expand access through delivery and subscription-like refill programs. As payers seek adherence improvements, programs tied to refill consistency and monitoring can strengthen utilization stability.
- For instance, Merck’s JANUMET combined sitagliptin and metformin in a single tablet dosed twice daily, and in a 24-week study involving 701 patients it delivered an additional 0.7 percentage-point A1C reduction beyond metformin alone, while 47% of patients reached A1C below 7% versus 18% on metformin alone.
Dipeptide Peptidase 4 (DPP-4) Inhibitors Market trends also include broader generic launches and portfolio optimization by manufacturers to defend volume through competitive pricing and channel partnerships. Geographic expansion into emerging markets supports growth where diagnosis rates and access to oral therapies continue to rise. Manufacturers increasingly invest in lifecycle approaches such as combination formats and differentiated packaging sizes for chronic use. Partnerships with distributors and pharmacy chains can strengthen shelf presence and substitution capture.
Regional Insights
North America
North America accounted for 37.8% of Dipeptide Peptidase 4 (DPP-4) Inhibitors Market revenue in 2025. Strong reimbursement infrastructure, higher diagnosis rates, and established chronic disease management programs support stable prescribing for oral glucose-lowering therapies. Retail dispensing and insurance-driven refill systems reinforce adherence and repeat utilization. Competitive dynamics are shaped by payer formularies and substitution behavior as generics expand.
Europe
Europe represented 26.1% of Dipeptide Peptidase 4 (DPP-4) Inhibitors Market revenue in 2025. National reimbursement structures support access, but cost-containment policies and reference pricing can accelerate generic adoption and limit branded pricing power. Prescribing patterns vary by country guidelines and local sequencing rules. Stable outpatient care models support ongoing demand for oral therapies in long-term diabetes management.
Asia Pacific
Asia Pacific held 23.4% of Dipeptide Peptidase 4 (DPP-4) Inhibitors Market revenue in 2025. Large patient populations and expanding access drive volume, while pricing constraints and uneven reimbursement can moderate revenue contribution relative to treatment load. Urban retail pharmacy growth and improving diagnosis rates support therapy initiation and continuation. Market expansion is supported by generics, wider distribution coverage, and patient preference for oral regimens.
Latin America
Latin America contributed 7.9% of Dipeptide Peptidase 4 (DPP-4) Inhibitors Market revenue in 2025. Demand is concentrated in major economies where retail pharmacy access and private-sector coverage support chronic therapy continuity. Public procurement and affordability constraints can limit branded penetration and can prioritize generics where available. Distribution partnerships and pharmacy chain coverage are important for improving continuity of supply and refill adherence.
Middle East & Africa
Middle East & Africa accounted for 4.8% of Dipeptide Peptidase 4 (DPP-4) Inhibitors Market revenue in 2025. Growth is strongest in markets with structured reimbursement and modern retail pharmacy networks, while access gaps persist in lower-income settings. Treatment affordability and diagnosis rates remain critical constraints for broad scaling. Expansion opportunities are tied to urban healthcare investment, distributor reach, and generic availability.
Competitive Landscape
Dipeptide Peptidase 4 (DPP-4) Inhibitors Market competition reflects a transition from brand-led growth to access-led volume strategies as generics expand. Manufacturers compete on formulary positioning, channel coverage, combination availability, supply reliability, and pricing discipline. Pharmacy substitution, payer preference rules, and tender outcomes shape share trajectories across markets. Differentiation increasingly comes from lifecycle management, partnership-based distribution strength, and the ability to sustain volume under price erosion.
Merck & Co. remains central to category dynamics due to long-standing brand presence and broad prescriber familiarity in DPP-4 inhibitor therapy. Merck & Co. strategy increasingly emphasizes managing lifecycle transition as generic competition expands and payer substitution accelerates. Merck & Co. commercial focus typically prioritizes maintaining access where formulary placement remains strong and supporting continuity across key outpatient channels. Merck & Co. portfolio management approach influences how quickly category pricing resets in major markets.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Merck & Co.
- AstraZeneca
- Boehringer Ingelheim
- Takeda Pharmaceutical
- Novartis
- Pfizer
- Sanofi
- Lupin
- Sun Pharmaceutical
- Dr. Reddy’s Laboratories
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In June 2025, Abbott and MSD Pharmaceuticals announced a strategic partnership in India under which Abbott will distribute MSD’s oral anti-diabetic medicines including sitagliptin, sitagliptin/metformin, and the extended-release version, expanding access to key DPP-4 inhibitor therapies in the country.
- In January 2025, CSPC Pharmaceutical Group received approval from China’s National Medical Products Administration for Shanzeping (prusogliptin tablets), a novel oral DPP-4 inhibitor for adult patients with type 2 diabetes, marking a new product approval in this market.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 11,280.60 million |
| Revenue forecast in 2032 | USD 15,527.66 million |
| Growth rate (CAGR) | 5.47% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026-2032 |
| Quantitative units | USD million |
| Segments covered | By Drug Type; By Formulation; By Therapy Line; By Combination Type; By Distribution Channel; By Patient Type |
| Regional scope | North America; Europe; Asia Pacific; Latin America; Middle East & Africa |
| Key companies profiled | Merck & Co.; AstraZeneca; Boehringer Ingelheim; Takeda Pharmaceutical; Novartis; Pfizer; Sanofi; Lupin; Sun Pharmaceutical; Dr. Reddy’s Laboratories |
| No. of Pages | 334 |
Segmentation
By Drug Type
- Sitagliptin
- Saxagliptin
- Linagliptin
- Alogliptin
- Others
By Formulation
- Oral Tablets
- Fixed-dose Combinations
- Others
By Therapy Line
- First-line Therapy
- Second-line Therapy
- Add-on Therapy
- Others
By Combination Type
- Monotherapy
- Combination with Metformin
- Combination with SGLT2
- Others
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Others
By Patient Type
- Type 2 Diabetes Adults
- Elderly Patients
- Renal-impaired Patients
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of Dipeptide Peptidase 4 (DPP-4) Inhibitors Market in 2025 and the forecast for 2032?
What is the CAGR for Dipeptide Peptidase 4 (DPP-4) Inhibitors Market during 2025–2032?
What is the largest segment in Dipeptide Peptidase 4 (DPP-4) Inhibitors Market?
What factors are driving growth in Dipeptide Peptidase 4 (DPP-4) Inhibitors Market?
Which companies are leading in Dipeptide Peptidase 4 (DPP-4) Inhibitors Market?
Which region leads the Dipeptide Peptidase 4 (DPP-4) Inhibitors Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 11,280.60 million → 2032: USD 15,527.66 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Dipeptide Peptidase 4 (DPP-4) Inhibitors Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 11,280.60 million → 2032: USD 15,527.66 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Dipeptide Peptidase 4 (DPP-4) Inhibitors Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Dipeptide Peptidase 4 (DPP-4) Inhibitors Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Dipeptide Peptidase 4 (DPP-4) Inhibitors Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

