
Market Overview
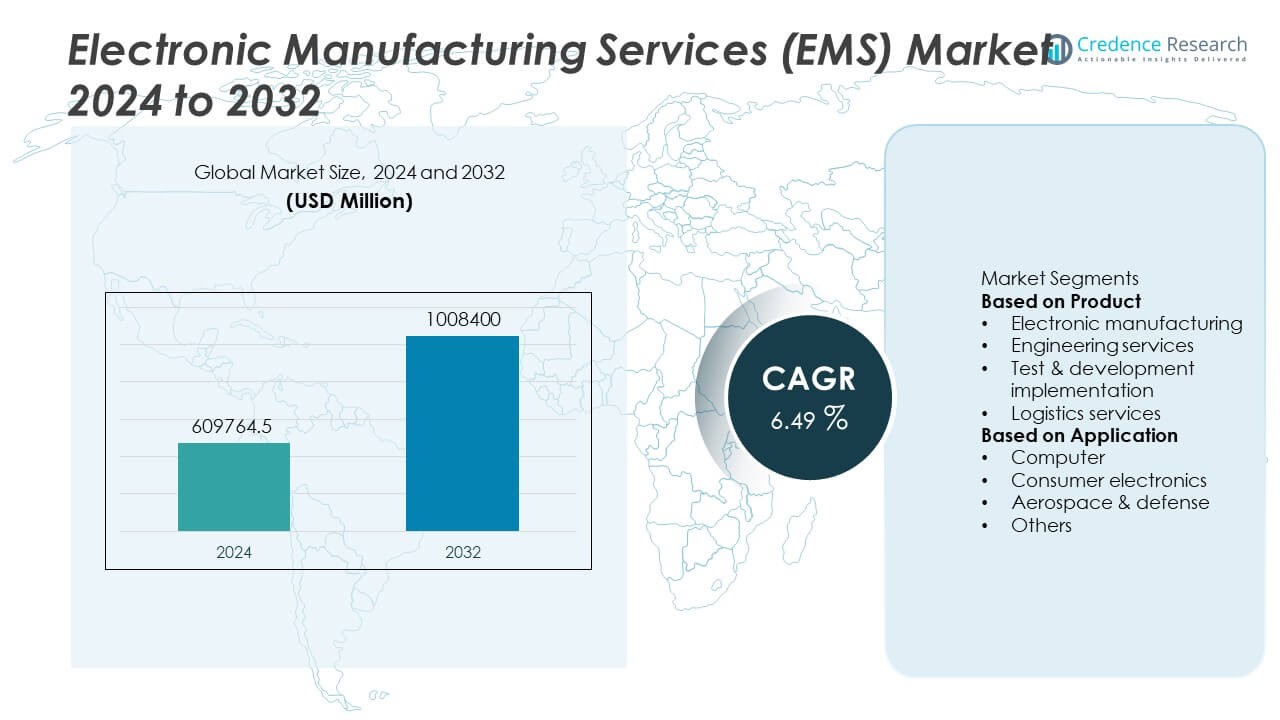
The Electronic Manufacturing Services (EMS) market size was valued at USD 697,645 million in 2024 and is projected to reach USD 1,008,400 million by 2032, growing at a CAGR of 6.49% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Electronic Manufacturing Services (EMS)Market Size 2024 | USD 697,645 Million |
| Electronic Manufacturing Services (EMS) Market, CAGR | 6.49% |
| Electronic Manufacturing Services (EMS)Market Size 2032 | USD 1,008,400 Million |
The electronic manufacturing services (EMS) market is led by top players such as Foxconn (Hon Hai Precision Industry Co., Ltd.), Wistron Corporation, Compal Electronics, Inc., Flex Ltd., Quanta Computer Inc., Jabil Inc., Pegatron Corporation, Celestica Inc., Sanmina Corporation, and Benchmark Electronics, Inc. These companies dominate with large-scale production, advanced engineering, and global supply chain capabilities, serving industries from consumer electronics to automotive and aerospace. Regionally, Asia Pacific led the EMS market in 2024 with 46% share, driven by strong manufacturing bases in China, Taiwan, and India. North America followed with 27% share, supported by advanced design services and high-value electronics demand, while Europe accounted for 20%, Latin America 4%, and the Middle East & Africa together held 3%, reflecting growing but smaller contributions.
Market Insights
- The electronic manufacturing services (EMS) market was valued at USD 69764.5 million in 2024 and is projected to reach USD 1008400 million by 2032, expanding at a CAGR of 6.49%.
- Rising demand for consumer electronics and computing devices drives EMS adoption, with consumer electronics holding 40% share in 2024 due to mass production needs.
- Trends such as miniaturization, IoT-enabled devices, and automation in testing and development strengthen growth opportunities across diverse industries including automotive and aerospace.
- Key players including Foxconn, Flex, Quanta, Wistron, and Jabil dominate competition through large-scale manufacturing, design services, and global supply chains, ensuring wide market reach.
- Regionally, Asia Pacific led with 46% share in 2024 due to strong manufacturing hubs in China and Taiwan, followed by North America at 27%, Europe at 20%, Latin America at 4%, and the Middle East & Africa holding 3%, reflecting widespread but uneven global adoption.
Market Segmentation Analysis:
By Product
The electronic manufacturing segment dominated the EMS market in 2024, holding 52% of the total share. Its leadership is driven by rising demand for outsourced manufacturing across consumer electronics, automotive, and telecom industries. Companies increasingly rely on EMS providers for cost efficiency, scalability, and advanced production capabilities, reducing in-house complexities. Engineering services accounted for 18% share, supporting product design and prototyping, while test and development implementation captured 16% share, ensuring quality and compliance. Logistics services held 14% share, playing a critical role in supply chain optimization and timely product delivery.
- For instance, Jabil Inc. operates over 100 manufacturing sites worldwide, acquired Intel's silicon photonics optical modules business in late 2023, and announced a multi-year $500 million investment in 2025 to expand its U.S. manufacturing footprint for cloud and AI infrastructure.
By Application
Consumer electronics led the EMS market in 2024, contributing 38% of the application share, supported by mass production of smartphones, wearables, and smart home devices. The segment benefits from shorter product life cycles and high global demand for connected devices. Computers followed with 25% share, fueled by the need for laptops, servers, and data storage systems. Aerospace and defense accounted for 20% share, emphasizing precision manufacturing and compliance standards, while the “others” segment, including automotive and healthcare electronics, represented 17% share, reflecting growing adoption of EMS in diverse industries.
- For instance, Sanmina Corporation delivered mission-critical defense electronics across 20+ certified U.S. facilities, enabling aerospace customers to meet MIL-STD compliance with high precision systems integration.
Key Growth Drivers
Rising Demand for Consumer Electronics
The EMS market is driven by the growing demand for smartphones, tablets, wearables, and smart home devices. With shorter product lifecycles and frequent technology upgrades, OEMs increasingly outsource manufacturing to EMS providers for speed and efficiency. Consumer electronics accounted for 38% share in 2024, highlighting its dominance. EMS companies provide cost optimization, scalability, and advanced assembly capabilities that meet high-volume requirements. The global appetite for connected and IoT-enabled devices ensures sustained demand, making consumer electronics a critical driver for EMS market growth.
- For instance, Foxconn's Zhengzhou iPhone City employs up to 200,000 workers during peak production season and assembles a large portion of the world's iPhones annually, significantly supporting Apple's global smartphone demand.
Expansion of Automotive Electronics
Automotive electrification and the rise of advanced driver-assistance systems (ADAS) are fueling EMS adoption. Automakers depend on EMS providers for electronic control units, battery management systems, and infotainment solutions. EMS providers offer quality assurance, miniaturization, and global supply chain expertise, reducing costs for OEMs. The integration of EV-specific components and autonomous driving technologies further drives this trend. As automotive electronics become more complex, EMS companies play a pivotal role in scaling production while ensuring compliance, reliability, and innovation across the industry.
- For instance, Flex Ltd. is an established automotive supplier that offers advanced product design and manufacturing solutions for global carmakers, with its products featured on hundreds of vehicle platforms worldwide. The company provides manufacturing-ready platforms that support ADAS and other advanced mobility solutions.
Focus on Cost Efficiency and Outsourcing
OEMs across industries outsource to EMS providers to optimize costs, reduce capital investment, and streamline operations. EMS partners deliver economies of scale, access to global supply chains, and advanced facilities that minimize time-to-market. With labor costs rising in developed countries, outsourcing to EMS providers in Asia-Pacific has become a standard practice. This model allows OEMs to focus on R&D and branding while delegating high-volume, precision manufacturing to EMS specialists. The emphasis on lean operations and efficiency makes outsourcing a central driver of market expansion.
Key Trends and Opportunities
Adoption of Industry 4.0 in EMS
Industry 4.0 technologies such as IoT, robotics, and automation are reshaping EMS operations. Smart factories with predictive analytics and AI-driven monitoring improve efficiency, reduce downtime, and enhance quality. EMS providers integrating advanced technologies offer faster, more reliable, and scalable solutions for OEMs. The demand for intelligent manufacturing also aligns with sustainability goals, as automation reduces waste and energy use. As more enterprises adopt digital transformation, Industry 4.0 integration creates significant growth opportunities for EMS providers to deliver value-added, technology-driven services.
- For instance, Wistron integrated Industrial Internet of Things (IIoT) under Industry 4.0 in plants such as its Kunshan facility, enabling AI-powered insights, flexible automation, and real-time monitoring of operations. In doing so, it enhanced productivity and reduced costs.
Growing Role in Aerospace and Defense
The aerospace and defense sector accounted for 20% share in 2024, providing EMS providers with long-term growth potential. These industries demand precision manufacturing, regulatory compliance, and advanced testing capabilities. EMS companies play a vital role in delivering high-reliability components, avionics, and defense electronics. With rising global defense budgets and increasing demand for aircraft, EMS providers offering design support, secure supply chains, and strict quality assurance will gain competitive advantage. The trend highlights opportunities for EMS providers to expand beyond consumer markets into mission-critical applications.
- For instance, Celestica provides high-reliability defense electronics to more than 25 global aerospace customers, including production of secure communication modules and satellite payload components with precise testing capabilities.
Key Challenges
Supply Chain Disruptions
Global EMS operations are highly vulnerable to supply chain disruptions caused by geopolitical tensions, component shortages, and logistical bottlenecks. Events such as semiconductor shortages have already delayed production timelines and increased costs for OEMs. As EMS providers rely heavily on just-in-time inventory models, disruptions can severely affect margins and delivery schedules. Ensuring resilience through diversification, nearshoring, and digital supply chain visibility remains a pressing challenge for the industry. Without robust strategies, disruptions may hinder the ability of EMS providers to meet growing demand.
Intense Market Competition
The EMS market faces strong competition with multiple global and regional players offering similar services at competitive prices. Price pressures often reduce profit margins, forcing providers to differentiate through innovation, scale, or vertical specialization. Smaller EMS providers struggle to compete with larger players that benefit from economies of scale and global reach. Additionally, OEMs often switch between EMS partners based on pricing and capacity, making long-term contracts harder to secure. Sustaining competitiveness in such an environment requires continuous investment in technology, efficiency, and customer-centric solutions.
Regional Analysis
North America
North America held 32% share of the EMS market in 2024, driven by strong demand from aerospace, defense, and healthcare industries. The region benefits from advanced manufacturing infrastructure, high R&D investments, and strong presence of global OEMs. The U.S. leads with increasing adoption of EMS for consumer electronics and automotive applications, supported by the rise of electric vehicles. Regulatory compliance and quality standards also boost outsourcing to EMS providers. The emphasis on reshoring and supply chain resilience creates further opportunities, making North America a mature but steadily growing EMS market.
Europe
Europe accounted for 28% share of the EMS market in 2024, supported by its advanced automotive and industrial electronics sectors. Countries like Germany, France, and the United Kingdom drive demand with strong manufacturing bases and growing investment in electric mobility. EMS adoption is also fueled by strict quality standards and regulatory compliance across industries such as healthcare and aerospace. The region’s emphasis on sustainability and green manufacturing is shaping EMS operations with energy-efficient practices. Continued demand for high-value, precision electronics ensures that Europe remains a key hub for EMS growth.
Asia Pacific
Asia Pacific dominated the EMS market with 34% share in 2024, making it the largest regional contributor. China, India, Japan, and South Korea drive this dominance through large-scale consumer electronics production, cost-effective labor, and advanced supply chain networks. The region is also the global hub for semiconductor and PCB manufacturing, which supports EMS providers across industries. Rising adoption of electric vehicles and 5G technology further accelerates demand. With growing investments in smart manufacturing and digital technologies, Asia Pacific continues to lead the EMS market, offering scale, innovation, and affordability for global OEMs.
Latin America
Latin America represented 4% share of the EMS market in 2024, with Brazil and Mexico as the primary contributors. The region is gaining importance due to increasing electronics production and proximity to North American markets. Growth is supported by rising demand for consumer electronics, automotive components, and industrial electronics. EMS providers are expanding operations in Mexico due to favorable trade agreements and cost advantages. However, challenges such as economic instability and limited infrastructure affect large-scale adoption. Despite these hurdles, Latin America shows steady growth potential in EMS with increasing foreign investments.
Middle East and Africa
The Middle East and Africa together accounted for 2% share of the EMS market in 2024, reflecting early-stage adoption but growing opportunities. The United Arab Emirates and Saudi Arabia lead demand, driven by diversification efforts in aerospace, defense, and industrial electronics. In Africa, South Africa contributes to growth with increasing adoption in telecommunications and automotive sectors. Limited manufacturing infrastructure remains a challenge, but government-led digitalization programs and investments in industrial development are supporting EMS expansion. As enterprises modernize operations, the region is expected to register steady growth in the EMS market over the forecast period.
Market Segmentations:
By Product
- Electronic manufacturing
- Engineering services
- Test & development implementation
- Logistics services
By Application
- Computer
- Consumer electronics
- Aerospace & defense
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape of the electronic manufacturing services (EMS) market is shaped by leading players including Wistron Corporation, Compal Electronics, Inc., Foxconn (Hon Hai Precision Industry Co., Ltd.), Flex Ltd., Quanta Computer Inc., Jabil Inc., Celestica Inc., Sanmina Corporation, Pegatron Corporation, and Benchmark Electronics, Inc. These companies dominate the market by offering large-scale production capabilities, advanced engineering expertise, and global supply chain management. Foxconn and Quanta lead in consumer electronics and computer assembly, while Flex and Jabil focus on diversified sectors including healthcare, automotive, and industrial electronics. Celestica, Pegatron, and Sanmina emphasize precision manufacturing, logistics, and system integration to support high-demand industries. Increasing demand for outsourcing, rapid innovation cycles, and cost efficiency continue to drive competition. Key players invest in automation, robotics, and digital manufacturing platforms to enhance productivity and reduce turnaround times. Their strategies revolve around expanding global footprints, maintaining scalability, and delivering end-to-end solutions to meet evolving OEM requirements.
Key Player Analysis
- Wistron Corporation
- Compal Electronics, Inc.
- Foxconn (Hon Hai Precision Industry Co., Ltd.)
- Flex Ltd.
- Quanta Computer Inc.
- Jabil Inc.
- Celestica Inc.
- Sanmina Corporation
- Pegatron Corporation
- Benchmark Electronics, Inc.
Recent Developments
- In August 2025, Foxconn (Hon Hai) adopted NVIDIA RTX PRO servers to accelerate GenAI and smart manufacturing systems.
- In July 2025, Foxconn and TECO formed a strategic alliance targeting AI data center capabilities and modular architectures.
- In February 2025, Flex Ltd. expanded its U.S. manufacturing footprint via a new 400,000 sq ft facility in Dallas to support power-product demand.
- In January 2024, Tata Electronics Private Limited acquired Wistron Infocomm Manufacturing (India) by acquiring 100% stake of the company marking a momentous milestone in the Indian electronics manufacturing.
Report Coverage
The research report offers an in-depth analysis based on Product, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The EMS market will expand with rising demand for consumer electronics and connected devices.
- Asia Pacific will maintain dominance as global manufacturing hubs continue scaling production capacity.
- Adoption of automation and robotics will enhance efficiency and reduce production errors.
- Demand from automotive electronics and EV components will significantly boost EMS growth.
- Cloud integration and IoT-enabled devices will increase the need for advanced EMS solutions.
- Large players will expand through vertical integration and global supply chain optimization.
- Miniaturization of electronic components will create new opportunities in high-tech assembly.
- Aerospace and defense demand will grow with rising investments in advanced electronics.
- Sustainability practices and green manufacturing will gain importance across EMS providers.
- Strategic partnerships and acquisitions will reshape competition and expand global presence.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Consumer Electronics Proliferation
The rapid growth in demand for smartphones, wearables, and smart home devices is driving OEMs to outsource manufacturing to EMS providers for scalability and cost efficiency. This segment accounted for 38% of the EMS market in 2024, highlighting its central role in market expansion.
Automotive Electronics and Electrification
The shift toward electric vehicles and advanced driver-assistance systems (ADAS) is increasing the need for complex electronic components, which automakers are increasingly outsourcing to EMS providers for quality, miniaturization, and supply chain expertise.
Adoption of Industry 4.0 and Automation
EMS providers are integrating IoT, robotics, and AI-driven analytics into their operations, enabling smart manufacturing that improves efficiency, reduces downtime, and enhances product quality, thus attracting more OEMs seeking advanced, reliable production partners.
Cost Optimization and Outsourcing Trends
OEMs across industries are turning to EMS providers to reduce capital investment, leverage economies of scale, and streamline operations, especially as labor costs rise in developed regions and global supply chains become more complex.
Expansion in Aerospace & Defense
The aerospace and defense sector, with its stringent quality and compliance requirements, is increasingly relying on EMS providers for precision manufacturing and advanced testing, offering long-term growth opportunities as global defense spending rises.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Electronic Manufacturing Services (EMS) market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Electronic Manufacturing Services (EMS) market projected to grow between 2025 and 2032?
Which Electronic Manufacturing Services (EMS) market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Electronic Manufacturing Services (EMS) market?
Who are the leading companies in the Electronic Manufacturing Services (EMS) market?
Which region commanded the largest share of the Electronic Manufacturing Services (EMS) market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Electronic manufacturing
- 1.2.2 Engineering services
- 1.2.3 Test & development implementation
- 1.2.4 Logistics services
- 1.3 By Application
- 1.3.1 Consumer electronics
- 1.3.2 Computer
- 1.3.3 Aerospace & defense
- 1.3.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 697,645 million → 2032: USD 1,008,400 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Electronic Manufacturing Services (EMS) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Electronic Manufacturing Services (EMS) Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Electronic Manufacturing Services (EMS) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Electronic Manufacturing Services (EMS) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Electronic Manufacturing Services (EMS) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Electronic Manufacturing Services (EMS) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Electronic Manufacturing Services (EMS) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Electronic Manufacturing Services (EMS) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 697,645 million → 2032: USD 1,008,400 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Electronic Manufacturing Services (EMS) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Electronic manufacturing
- 12.3.6.2 Engineering services
- 12.3.6.3 Test & development implementation
- 12.3.6.4 Logistics services
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Consumer electronics
- 12.4.6.2 Computer
- 12.4.6.3 Aerospace & defense
- 12.4.6.4 Others
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Electronic Manufacturing Services (EMS) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Electronic Manufacturing Services (EMS) Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Electronic Manufacturing Services (EMS) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Electronic Manufacturing Services (EMS) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Foxconn (Hon Hai Precision Industry Co., Ltd.)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Wistron Corporation
- 18.4 Compal Electronics, Inc.
- 18.5 Flex Ltd.
- 18.6 Quanta Computer Inc.
- 18.7 Jabil Inc.
- 18.8 Celestica Inc.
- 18.9 Sanmina Corporation
- 18.10 Pegatron Corporation
- 18.11 Benchmark Electronics, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

