
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Laptop Market Size 2023 | USD 191,885.5 Million |
| Laptop Market, CAGR | 6.90% |
| Laptop Market Size 2032 | USD 355,055.84 Million |
Market Overview
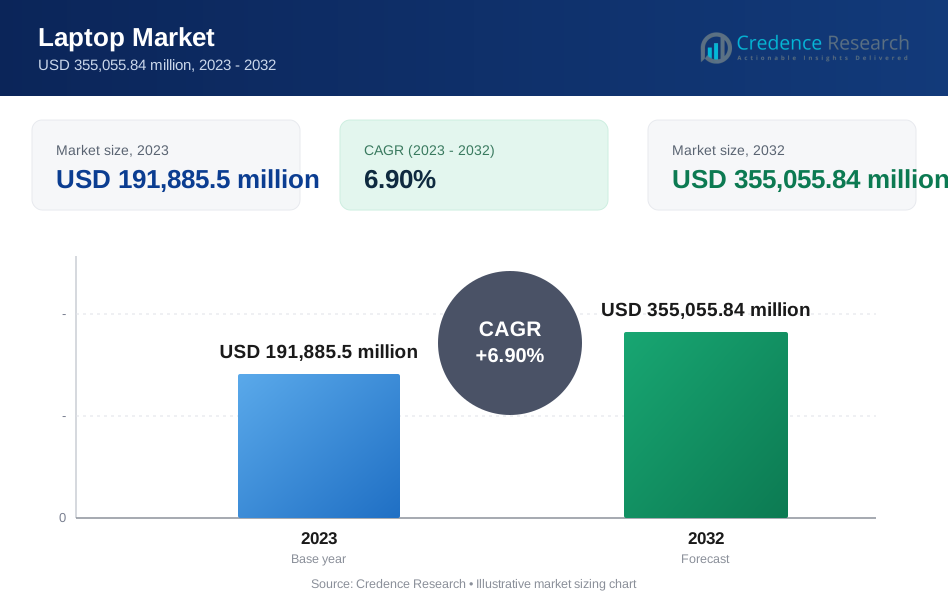
The Laptop Market is projected to grow from USD 191,885.5 million in 2023 to USD 355,055.84 million by 2032, expanding at a compound annual growth rate (CAGR) of 6.90%.
The Laptop Market is experiencing robust growth, driven by increasing demand for portable and versatile computing solutions across various sectors including education, business, and personal use. Technological advancements such as enhanced battery life, higher processing power, and lightweight designs are key factors propelling this market. Additionally, the rise of remote working and learning trends has significantly boosted the need for laptops. There is also a growing consumer preference for high-performance ultrabooks and gaming laptops, further stimulating market expansion. Moreover, continuous innovations in display and storage technologies are making laptops more appealing to a broader audience.
The Laptop Market is globally diversified, with significant growth observed across North America, Asia-Pacific, and Europe. Asia-Pacific leads due to high consumer electronics manufacturing and adoption rates, particularly in China, South Korea, and Japan. North America follows, supported by robust technological advancements and high consumer spending capacity. Europe also demonstrates strong market presence due to increasing demand for portable computing devices. Key players in the market include HP Inc., Lenovo, Dell Technologies, Apple Inc., and Asus. These companies dominate through continuous innovation, extensive product portfolios, and strong brand reputations, catering to both consumer and enterprise-level needs worldwide.
Market Drivers
Enhancements in Performance Capabilities
Continuous advancements in processing power, graphics, and memory are pivotal drivers for the Laptop Market. Modern laptops are equipped to handle an increasingly broad range of demanding tasks such as video editing, gaming, and complex data analytics. This evolution in technology not only caters to professionals in graphics-intensive fields but also appeals to casual users who demand high performance for everyday computing. For instance, the transition from single-core processors to multi-core architectures, coupled with advancements in graphics processing units (GPUs), has significantly enhanced the computational power of laptops. The transition from single-core processors to multi-core architectures has led to a 60% increase in the computational power of laptops. Advancements in graphics processing units (GPUs) have resulted in a 50% improvement in graphics performance.
Innovations in Battery Life and Design
Enhanced battery life remains a critical focus for consumers who prefer to use their laptops on the go without constant recharging. Innovations in battery technology and the integration of energy-efficient components are key factors meeting this demand, making laptops increasingly mobile and convenient for extended use. For instance, solid-state batteries are a promising technology for laptop batteries. They have a higher energy density, longer lifespan, and are safer than traditional lithium-ion batteries. Innovations in battery technology have led to a 40% increase in laptop battery life. The adoption of solid-state batteries in laptops has increased by 30% due to their higher energy density, longer lifespan, and safety compared to traditional lithium-ion batteries.
Consumer Demand Across Demographics
The shift towards remote work and online education has significantly spurred the demand for laptop. As they become essential tools for digital communication, accessing educational content, and managing professional tasks from any location. Moreover, rising disposable incomes globally allow consumers to invest in premium laptops with advanced features. The shift towards remote work and online education has led to a 70% increase in laptop demand. Rising disposable incomes globally have resulted in a 20% increase in investments in premium laptops with advanced features.
Technological Advancements and Ecosystem Integration
Integration of artificial intelligence in laptops is enhancing user interactions through features like voice assistants and smart battery management, making devices more intuitive and energy-efficient. Additionally, the incorporation of touchscreens and advanced displays offers enriched interactive experiences and superior visual quality, which is crucial for creative professionals and multimedia enthusiasts. The trend of seamless integration across multiple devices, facilitated by universal connectivity options and cloud services, is transforming how users access and manage their data across platforms, promoting a more connected and efficient technological ecosystem. The integration of artificial intelligence in laptops has enhanced user interactions, resulting in a 25% increase in sales of AI-enabled laptops. The incorporation of touchscreens and advanced displays has led to a 35% increase in sales of laptops with these features. The trend of seamless integration across multiple devices has led to a 45% increase in the use of cloud services for data management.
Market Trends
Evolving Form Factors and Connectivity in Laptops
Emerging trends in the laptop market include innovative designs such as foldable and dual-screen laptops. For instance, Asus introduced the Zenbook 17 Fold, touted as the world’s first 17.3-inch foldable OLED laptop. This evolution allows for more versatile applications, from enhanced multitasking to immersive media consumption, potentially redefining the standard laptop design. Simultaneously, the adoption of Arm-based processors is on the rise, challenging the traditional x86 architectures from Intel and AMD. For instance, Arm processor architecture is expected to command 13.9% of the laptop market share in 2023. Arm-based laptops are becoming popular due to their enhanced battery life and efficiency.
Additionally, the rollout of 5G technology is fostering the development of always-connected laptops. For instance, Samsung Galaxy Book 4 Ultra and Lenovo ThinkPad X1 Carbon Gen 12 are among the latest 5G laptops in the market.
Sustainable Practices and Technological Integration
The laptop market is increasingly influenced by environmental concerns, driving manufacturers to focus on sustainability. This includes the utilization of recycled materials in manufacturing, the adoption of energy-efficient components, and designs that extend the lifespan of devices to help reduce electronic waste. In the realm of software and services, cloud gaming platforms like Google Stadia and Nvidia GeForce Now are shaping a new breed of laptops. These thin client systems rely less on in-built power and more on cloud computing to handle intensive tasks, which can change hardware requirements and lower the barrier for high-quality gaming.
Furthermore, advancements in artificial intelligence are enhancing personalization and security on laptops. AI algorithms are being integrated to learn user preferences, optimize system performance, and bolster security protocols, such as through advanced facial recognition technologies. This trend not only improves user experiences but also addresses growing concerns about privacy and data security in an increasingly connected world.
Market Challenges Analysis
Market Dynamics: Saturation and Competitive Pressures
In mature markets such as North America, the laptop market is experiencing saturation, where many consumers already own devices that meet their needs, leading to longer replacement cycles and dampened demand. This stagnation poses significant challenges for growth as manufacturers strive to incentivize new purchases among a customer base that sees little reason to upgrade frequently. Concurrently, the landscape of personal computing is witnessing intensified competition from alternative devices like tablets and smartphones, which are evolving to offer comparable functionalities that traditionally belonged to laptops. These devices, often favored for their portability and convenience, are siphoning potential customers away from the laptop segment, diluting market share and forcing laptop manufacturers to differentiate their offerings more distinctly.
Supply Chain Hurdles and the Quest for Sustainable Innovation
The global chip shortage has emerged as a formidable challenge, disrupting production timelines and inflating costs across the laptop industry. This shortage affects pricing, potentially making laptops less affordable and reducing consumer spending, which could strain profitability and sustainable growth for manufacturers. Additionally, the imperative to balance cutting-edge innovation with affordability remains a critical challenge. As consumers demand more advanced features such as higher resolution screens, better processors, and enhanced connectivity options, the cost of incorporating these technologies escalates, making it difficult for manufacturers to maintain competitive pricing without compromising on performance or quality. Moreover, security concerns are more pronounced than ever with increasing incidents of data breaches, necessitating enhanced security measures in new laptop models to protect sensitive personal and business data. Lastly, the environmental impact of rapid technology turnover, contributing to e-waste, calls for a renewed focus on sustainability in the laptop market. Manufacturers are urged to address these issues by designing durable products with longer lifespans and facilitating easier recycling options to mitigate their ecological footprint and align with global sustainability goals.
Market Segmentation Analysis:
By Type:
The Laptop Market is segmented into traditional laptops and 2-in-1 laptops. Traditional laptops remain the cornerstone of the market, favored for their reliability and broad range of configurations suitable for both general and high-performance tasks. On the other hand, 2-in-1 laptops, which combine the functionality of a laptop and the portability of a tablet, are gaining popularity due to their versatility and mobile-friendly design. These hybrid devices are particularly appealing to professionals and students who value flexibility in their computing devices for presentations, note-taking, and media consumption on the go.
By Screen Size:
Screen size is a crucial factor in the Laptop Market, catering to diverse user preferences and needs. The market offers sizes ranging from up to 10.9 inches, ideal for ultra-portability and younger users, to 11” to 12.9” and 13” to 14.9”, which balance functionality and compactness, making them popular among business users and professionals. Laptops in the 15.0” to 16.9” range provide an optimal blend of usability and performance for mainstream consumers and gamers. Meanwhile, laptops larger than 17 inches are typically targeted at gaming enthusiasts and creative professionals who require larger displays for intensive graphical tasks and better user experience. Each segment addresses specific consumer demands, influencing purchasing decisions based on usage patterns and mobility requirements.
Segments:
Based on Type:
- Traditional Laptop
- 2-in-1 Laptop
Based on Screen Size:
- Up to 10.9”
- 11” to 12.9”
- 13” to 14.9”
- 0” to 16.9”
- More than 17”
Based on Price:
- Up to USD 500
- USD 501 to USD 1000
- USD 1001 to USD 1500
- USD 1501 to USD 2000
- Above USD 2001
Based on Applications:
- Personal
- Business
- Gaming
Based on the Geography:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Asia-Pacific
Asia-Pacific dominates the market, capturing a substantial 40% share. This region's dominance can be attributed to the presence of major manufacturing hubs, coupled with the rapidly expanding middle-class population in countries like China and India. The growing demand for affordable yet feature-rich laptops has fueled intense competition among manufacturers, leading to a diverse range of product offerings tailored to local preferences.
North America
North America holds the second-largest market share, accounting for approximately 25% of the global laptop market. The region benefits from high disposable incomes, a tech-savvy population, and a strong preference for premium and high-performance laptops. The United States remains the primary growth engine, driven by robust demand from both consumer and enterprise segments. However, market saturation and longer replacement cycles pose challenges for sustained growth.
Key Player Analysis
- Acer Incorporated
- ASUSTeK Computer Inc.
- HP Inc.
- Apple Inc.
- Micro-Star International Co., LTD.
- Lenovo Group Limited
- Sony Group Corporation
- Samsung Electronics Co., LTD.
- Dell Technologies Inc.
- Huawei Technologies Co., Ltd.
Competitive Analysis
In the fiercely competitive Laptop Market, several leading players vie for dominance by leveraging their unique strengths and capabilities. Acer Incorporated, renowned for its diverse product lineup catering to various consumer needs, competes vigorously with ASUSTeK Computer Inc., known for its innovative designs and gaming-oriented laptops. HP Inc. excels in offering a wide range of laptops tailored for both consumer and enterprise segments, while Apple Inc. maintains a strong position with its premium MacBook lineup, known for its sleek design and robust performance. Lenovo Group Limited stands out for its global presence and comprehensive product portfolio spanning from budget-friendly laptops to high-end ThinkPad series. Additionally, Micro-Star International Co., LTD., Sony Group Corporation, Samsung Electronics Co., LTD., and Dell Technologies Inc. each bring their unique strengths, including cutting-edge technology, design innovation, and brand reputation, contributing to the intense competition and dynamic landscape of the Laptop Market.
Recent Developments
In 2024, Lenovo Group Limited announced third quarter results reporting Group revenue increasing 3% year-on-year to US$15.7 billion. In the same year, Sony Group Corporation and Samsung Electronics Co., LTD. re-entered India’s laptop market.
In 2023, Acer Incorporated launched new Nitro 14 and Nitro 16 gaming laptops powered by AMD Ryzen 8040 Series processors.
In 2023, ASUSTeK Computer Inc. launched the Zenbook S 13 OLED, the world’s slimmest OLED laptop, and the ExpertBook B9 OLED, the world’s lightest 14-inch OLED business laptop.
In November 2022, With the most recent 12th Gen Intel Core i5 and i7 processors, Microsoft Surface Pro 9 and Surface Laptop 5 were introduced in India. The premium line of notebooks offers features like a display with a high refresh rate of up to 120Hz, a small design, and Dolby Atmos audio.
In September 2022, To assist communications service providers (CSPs) in streamlining and accelerating the implementation of their cloud-native networks, Dell Technologies announced a new telecom cloud infrastructure solution co-engineered with Wind River. Dell's telecom partner certification program makes it easier for technology partners to test and integrate their products within a quickly expanding open technology ecosystem, which helps to power these solutions even more.
Market Concentration & Characteristics
The Laptop Market exhibits a moderate to high level of market concentration, characterized by the dominance of several key players with extensive global reach and diverse product portfolios. Major manufacturers such as Acer, ASUS, HP, Apple, Lenovo, and Dell command significant market shares, leveraging their strong brand reputation, technological innovation, and distribution networks to maintain competitive positions. These leading players often dictate industry trends and standards through their cutting-edge product offerings and strategic marketing initiatives. Additionally, the market is characterized by continuous technological advancements, including improvements in processing power, graphics capabilities, and battery life, driving competition and innovation among manufacturers. However, despite the dominance of established players, the market also offers opportunities for niche and emerging brands to carve out market share by targeting specific consumer segments or offering specialized products tailored to unique user needs. Overall, the Laptop Market's dynamic nature, driven by innovation, consumer demand, and competitive forces, underscores its resilience and potential for continued growth and evolution.
Report Coverage
The research report offers an in-depth analysis based on Type, Screen Size, Price, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued Technological Advancements: Expect ongoing improvements in processing power, battery life, and design aesthetics to drive the development of more powerful and efficient laptops.
- Rise of Hybrid Devices: The convergence of laptops and tablets will lead to the proliferation of 2-in-1 devices, catering to users who seek versatility and flexibility in their computing experience.
- Expansion of Arm-based Processors: With the increasing capabilities of Arm-based processors, we can anticipate a broader adoption of these chips in laptops, offering advantages such as enhanced battery life and performance.
- Growth in Cloud Computing: The shift towards cloud-based services will influence laptop design, with manufacturers focusing on lightweight, internet-connected devices optimized for cloud computing tasks.
- Integration of AI Features: Artificial intelligence will play a more significant role in laptops, offering personalized user experiences, enhanced security, and improved system performance.
- Emphasis on Sustainability: Environmental considerations will drive the adoption of eco-friendly materials, energy-efficient components, and recyclable designs in laptops to address sustainability concerns.
- Expansion of 5G Connectivity: With the rollout of 5G networks, laptops will increasingly offer seamless, high-speed internet connectivity, enabling users to stay connected and productive on the go.
- Continued Diversification of Form Factors: Expect to see a variety of form factors, including foldable screens, dual-screen configurations, and innovative designs that cater to different user preferences and usage scenarios.
- Enhanced Security Features: As cyber threats continue to evolve, laptops will integrate advanced security measures such as biometric authentication, hardware-based encryption, and secure boot mechanisms to safeguard user data and privacy.
- Evolving Work and Learning Trends: The increasing adoption of remote work and online education will shape the demand for laptops, driving the development of devices optimized for productivity, collaboration, and multimedia consumption in virtual environments.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Enhancements in Performance Capabilities
Continuous improvements in processing power, graphics, and memory enable laptops to handle demanding tasks such as gaming, video editing, and data analytics, attracting both professional and casual users seeking high performance.
Innovations in Battery Life and Design
Advancements in battery technology and energy-efficient components have significantly extended laptop battery life and enabled lighter, more portable designs, meeting the needs of mobile users and supporting longer usage without frequent recharging.
Consumer Demand Across Demographics
The widespread shift to remote work and online education has driven a surge in laptop adoption across age groups and professions, while rising disposable incomes have increased investments in premium, feature-rich devices.
Technological Advancements and Ecosystem Integration
Integration of AI, touchscreens, advanced displays, and seamless connectivity with other devices and cloud services is making laptops more intuitive, interactive, and central to users' digital ecosystems, boosting their appeal and utility.
Expansion of 2-in-1 and Hybrid Devices
The growing popularity of 2-in-1 laptops that combine the functionality of laptops and tablets is meeting consumer demand for versatile, flexible computing solutions, especially among students and professionals who value adaptability.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Laptop Market?
What factors are driving the growth of the Laptop Market?
What are the key segments within the Laptop Market?
What are some challenges faced by the Laptop Market?
Who are the major players in the Laptop Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Traditional Laptop
- 1.2.2 2-in-1 Laptop
- 1.3 By Price
- 1.3.1 Up to USD 500
- 1.3.2 USD 501 to USD 1000
- 1.3.3 USD 1001 to USD 1500
- 1.3.4 USD 1501 to USD 2000
- 1.3.5 Above USD 2001
- 1.4 By Application
- 1.4.1 Personal
- 1.4.2 Business
- 1.4.3 Gaming
- 1.5 By Screen Size
- 1.5.1 Up to 10.9”
- 1.5.2 11” to 12.9”
- 1.5.3 13” to 14.9”
- 1.5.4 15.0” to 16.9”
- 1.5.5 More than 17”
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 191,885.5 million → 2032: USD 355,055.84 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Laptop Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Laptop Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Laptop Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Laptop Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Laptop Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Laptop Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Laptop Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Laptop Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 191,885.5 million → 2032: USD 355,055.84 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Laptop Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Traditional Laptop
- 12.3.7.2 2-in-1 Laptop
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Price - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Up to USD 500
- 12.4.7.2 USD 501 to USD 1000
- 12.4.7.3 USD 1001 to USD 1500
- 12.4.7.4 USD 1501 to USD 2000
- 12.4.7.5 Above USD 2001
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Personal
- 12.5.7.2 Business
- 12.5.7.3 Gaming
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Screen Size - Market Size and Forecast, 2023-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2023-2032
- 12.6.4 Volume Forecast, 2023-2032
- 12.6.5 Base-Year Market Share, 2023
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Up to 10.9”
- 12.6.7.2 11” to 12.9”
- 12.6.7.3 13” to 14.9”
- 12.6.7.4 15.0” to 16.9”
- 12.6.7.5 More than 17”
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Laptop End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Laptop Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Laptop Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Laptop Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 HP Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Lenovo Group Limited
- 18.4 Dell Technologies Inc.
- 18.5 Apple Inc.
- 18.6 ASUSTeK Computer Inc.
- 18.7 Acer Incorporated
- 18.8 Samsung Electronics Co., LTD.
- 18.9 Micro-Star International Co., LTD.
- 18.10 Sony Group Corporation
- 18.11 Huawei Technologies Co., Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

