
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Engineering Plastics Market Size 2024 | USD 122855 million |
| Engineering Plastics Market, CAGR | 7.1% |
| Engineering Plastics Market Size 2032 | USD 212671 million |
Market Overview:
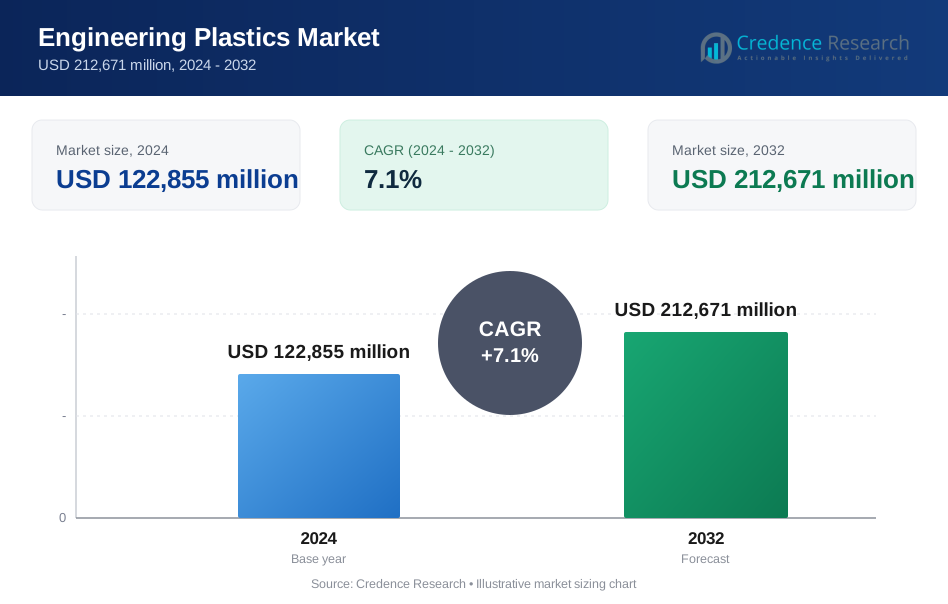
The Engineering Plastics Market is projected to grow from USD 122855 million in 2024 to an estimated USD 212671 million by 2032, with a compound annual growth rate (CAGR) of 7.1% from 2024 to 2032.
A primary driver in the engineering plastics market is the rising demand for lightweight, high-performance materials in the automotive and electronics sectors. As automakers face stringent regulations on emissions, they are increasingly turning to engineering plastics to reduce vehicle weight, improve fuel efficiency, and enhance overall performance. Similarly, the electronics industry leverages these materials for parts that require precise tolerance, heat resistance, and improved longevity. Growth in construction and infrastructure projects worldwide also contributes to market expansion, as these plastics provide an effective solution for materials that require high strength-to-weight ratios and durability. Moreover, the medical sector's adoption of engineering plastics in applications such as surgical instruments and medical devices aligns with ongoing trends in biocompatibility and sustainability, further driving market growth.
Regionally, Asia-Pacific dominates the engineering plastics market, attributed to its booming automotive, electronics, and construction industries. China, Japan, and South Korea are key players within this region, benefiting from large-scale manufacturing capacities and increasing demand from domestic and export markets. North America and Europe follow closely, driven by strong automotive and aerospace industries, as well as a focus on sustainable practices that emphasize the use of recyclable materials. In North America, the United States stands out due to its advanced manufacturing capabilities and research in polymer technologies. Europe, particularly Germany and France, is characterized by strict regulations that favor high-performance and environmentally friendly plastics. Meanwhile, developing regions such as Latin America and the Middle East & Africa are expected to witness moderate growth, spurred by infrastructure development and rising industrialization.
Market Drivers:
Automotive Industry Demand for Lightweight Materials:
One One of the major drivers in the engineering plastics market is the automotive industry’s increasing demand for lightweight, high-performance materials. Engineering plastics have proven to be excellent substitutes for metals, offering a reduction in vehicle weight that directly contributes to improved fuel efficiency and lower carbon emissions. With governments worldwide imposing strict emissions regulations, automotive manufacturers are under pressure to adopt materials that support compliance while maintaining safety and performance standards. For instance, BMW uses polycarbonate and polyamide in its vehicles, resulting in a weight reduction of up to 50 kilograms per vehicle. Engineering plastics, such as polycarbonate and polyamide, are used extensively in components like fuel systems, under-the-hood parts, and interior applications, delivering not only weight savings but also enhanced durability and thermal resistance.
Electronics Sector's Need for High-Performance Materials:
The The electronics industry relies heavily on engineering plastics for their precision, durability, and heat resistance, making these materials crucial in the production of electronic devices and components. As consumer demand for electronics grows, engineering plastics are used in products like connectors, switches, circuit boards, and enclosures where precision, weight, and insulation properties are vital. For instance, Samsung uses engineering plastics in its smartphones and other electronic devices, which helps in reducing the weight of each device by approximately 20 grams. Additionally, the rapid miniaturization of electronic devices necessitates materials that can withstand high temperatures and remain stable under pressure. Engineering plastics meet these needs by offering flexibility in design, resilience in extreme conditions, and compatibility with emerging technologies, fueling demand across both consumer electronics and industrial applications
Construction and Infrastructure Growth:
The construction industry’s expansion, particularly in emerging economies, has significantly impacted the demand for engineering plastics. With urbanization and infrastructure development accelerating worldwide, there is a growing requirement for materials that offer durability, weather resistance, and high strength-to-weight ratios. Engineering plastics serve as valuable alternatives to traditional materials in construction applications such as piping, windows, insulation, and structural components. Their resistance to corrosion, chemicals, and extreme weather conditions positions them as reliable options in infrastructure projects, including buildings, roads, and bridges. As sustainability takes center stage in the construction industry, engineering plastics are increasingly chosen for their recyclability and long lifespan, aligning with environmentally conscious building practices.
Medical Industry Adoption of Biocompatible Plastics:
The engineering plastics market is also benefiting from the medical sector's rising demand for biocompatible, high-quality materials. Engineering plastics such as polyether ether ketone (PEEK) and polycarbonate are being adopted in various medical applications, from surgical instruments to medical devices and implants. These materials are preferred for their strength, sterility, and ability to withstand high temperatures during sterilization processes. Furthermore, as the healthcare sector continues to innovate, engineering plastics are playing a critical role in producing devices that are not only safe for patients but also compatible with advancements in diagnostics and minimally invasive procedures. The shift toward personalized healthcare and the growing trend of home healthcare devices also support the demand for engineering plastics, as they offer design flexibility, lightweight characteristics, and chemical resistance, essential for modern medical applications.
Market Trends:
Growing Preference for Sustainable and Recyclable Plastics:
One of the prevailing trends in the engineering plastics market is the increasing emphasis on sustainable and recyclable materials. Environmental regulations worldwide are tightening, pushing manufacturers to innovate with eco-friendly options. Recyclable engineering plastics, such as polycarbonate and bio-based polyamide, have gained traction, especially in Europe and North America, where governments and consumers are advocating for greener products. Companies are investing in research to develop engineering plastics with lower environmental impact, including bio-based alternatives and plastics that can be recycled without compromising performance. This shift towards sustainability is expected to fuel the growth of engineering plastics in sectors like automotive and electronics, where materials need to meet both performance and environmental standards.
Advancements in High-Performance Plastics for Electronics:
The engineering plastics market is seeing rapid innovation to meet the demands of the electronics industry, particularly with the rise of miniaturized and high-performance devices. Engineering plastics are essential in manufacturing smaller, more efficient electronic components, as they offer insulation and heat resistance critical to device functionality. The demand for heat-resistant materials is particularly high, as devices need to manage rising power densities without sacrificing longevity or reliability. Plastics like polyphenylene sulfide (PPS) and liquid crystal polymer (LCP) are increasingly used in components such as connectors, sensors, and housings for their exceptional thermal stability. This trend aligns with the global growth of electronics manufacturing, especially in Asia-Pacific, where the adoption of advanced engineering plastics is helping producers meet the demands of a competitive market.
Increased Adoption in 3D Printing and Additive Manufacturing:
Engineering plastics are becoming integral to the fast-growing 3D printing and additive manufacturing industries, especially as demand for customized and on-demand production rises. Engineering-grade plastics, such as polyamide (nylon) and acrylonitrile butadiene styrene (ABS), are commonly used for 3D-printed prototypes and functional parts due to their strength, durability, and ease of processing. For instance, Stratasys uses ABS in its 3D printers to create durable and precise prototypes. As the technology advances, more industries are turning to 3D printing to produce complex parts cost-effectively, and the adoption of engineering plastics in this space is projected to grow significantly. The aerospace, medical, and automotive industries, in particular, are adopting 3D printing as a means of producing high-quality, intricate components, driving demand for specialized plastics that can withstand rigorous conditions. This trend is encouraging manufacturers to expand their offerings and develop plastic grades tailored specifically for additive manufacturing
Shift Toward Electric Vehicles (EVs) and High-Voltage Applications:
The engineering plastics market is also responding to the automotive industry’s transition towards electric vehicles (EVs) and high-voltage applications. EVs require materials that are not only lightweight but also provide high electrical insulation and thermal stability. Engineering plastics like polyamide 6,6 and polybutylene terephthalate (PBT) are widely adopted in battery components, connectors, and housings for their excellent dielectric properties and heat resistance. For instance, Lanxess provides polyamide 6,6 for EV battery components, which enhances thermal management and safety. The ongoing push toward EV adoption in North America, Europe, and China is expected to drive the demand for these high-performance plastics. Additionally, engineering plastics are being developed to meet specific requirements for battery thermal management and powertrain efficiency, as automakers prioritize safety and reliability in the evolving EV landscape
Market Restraints and Challenges:
High Production Costs and Raw Material Prices:
One of the primary restraints in the engineering plastics market is the high production costs associated with these materials. Engineering plastics require complex manufacturing processes and specialized equipment, which can increase overall costs. Additionally, the prices of raw materials, such as crude oil derivatives used in plastic production, are volatile and can fluctuate significantly. These high production costs make engineering plastics less affordable, particularly for smaller manufacturers or industries with tight budget constraints. This factor limits the widespread adoption of engineering plastics, especially in price-sensitive markets where alternative materials are more cost-effective.
Environmental and Regulatory Pressures:
The engineering plastics industry faces growing environmental and regulatory pressures as governments worldwide implement stricter policies regarding plastic waste and emissions. While there is an increasing push toward recyclable and bio-based plastics, achieving the same performance levels with sustainable alternatives remains challenging. Compliance with these regulations often requires companies to invest in new technologies or reformulate their products, which can be costly and time-consuming. For manufacturers, balancing performance with sustainability is a significant challenge, and the failure to meet regulatory standards could limit market access, especially in regions with stringent environmental laws.
Competition from Alternative Materials:
The availability of alternative materials poses another challenge to the engineering plastics market. Metals, composites, and cheaper plastics can sometimes provide similar functionality at a lower cost, making them attractive to industries that do not require the unique properties of engineering plastics. For example, in the automotive industry, advanced metal alloys and composite materials are often considered viable substitutes. This competition makes it difficult for engineering plastics to gain market share in sectors where performance requirements can be met with less expensive alternatives, thereby constraining market growth and adoption.
Market Segmentation Analysis:
The engineering plastics market is segmented by type and end-use industry, reflecting its broad application range and material diversity.
By type, Acrylonitrile Butadiene Styrene (ABS) holds a significant share due to its durability and versatility in automotive and consumer appliance applications. Polyamide (PA), valued for its strength and chemical resistance, finds extensive use in automotive and industrial applications. Polycarbonate (PC), known for its impact resistance and optical clarity, is widely adopted in the electronics, automotive, and construction sectors. Thermoplastic Polyester (e.g., PET and PBT) is favored in electronics and automotive for its dimensional stability and resistance to moisture. Polyacetal (POM) is commonly used in precision engineering applications, while Fluoropolymer finds niche uses in high-performance, chemically resistant environments. The "Others" category includes specialized materials like Polyether Ether Ketone (PEEK) for aerospace and medical applications.
By end-use industry, Automotive & Transportation is a key segment, driven by the demand for lightweight materials to enhance fuel efficiency and reduce emissions. Consumer Appliances utilize engineering plastics for durability and aesthetic appeal, while Electrical & Electronics rely on these materials for insulation, heat resistance, and precision. Industrial & Machinery applications benefit from engineering plastics' mechanical strength and wear resistance, making them suitable for gears, bearings, and housings. Packaging also represents a growing segment, especially in food and pharmaceutical applications that require high-strength, lightweight materials. The diversity in applications across these industries highlights the essential role of engineering plastics in modern manufacturing.
Segmentation:
By type,
- Acrylonitrile Butadiene Styrene
- Polyamide
- Polycarbonate
- Thermoplastic Polyester
- Polyacetal
- Fluoropolymer
- Others
By end-use industries,
- Automotive & Transportation
- Consumer Appliances
- Electrical & Electronics
- Industrial & Machinery
- Packaging
- Others
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The engineering plastics market is segmented geographically into Asia-Pacific, North America, Europe, Latin America, and the Middle East & Africa, each of which has distinct growth drivers and market dynamics.
Asia-Pacific holds the largest market share, accounting for approximately 45% of the global engineering plastics market. The region’s dominance is attributed to its robust manufacturing base, particularly in China, Japan, and South Korea, which are global leaders in the automotive, electronics, and construction industries. The increasing demand for lightweight and high-performance materials in these sectors drives the market. In addition, favorable government policies supporting industrial development and rising urbanization further bolster demand in the region. India is also emerging as a significant market for engineering plastics, driven by rapid infrastructure growth and an expanding automotive industry.
North America is the second-largest market, with an estimated 25% share. The U.S. and Canada are primary contributors, benefiting from a strong presence in automotive, aerospace, and electronics industries. North American manufacturers focus on developing sustainable and high-performance materials due to stringent regulations on emissions and waste. The growing adoption of electric vehicles (EVs) and advancements in medical devices also stimulate demand for engineering plastics in the region. Additionally, the high rate of technological innovation and research into advanced polymer technologies supports the North American market’s steady growth.
Europe follows closely, holding approximately 20% of the market share. The region’s demand is driven by its well-established automotive industry, particularly in Germany, where high-performance plastics are used extensively for lightweighting and improving fuel efficiency. European countries have strict environmental regulations that encourage the use of recyclable and sustainable engineering plastics, particularly in packaging and consumer goods. Moreover, the region’s focus on renewable energy and electric vehicle adoption increases the demand for engineering plastics in battery and power management components. The United Kingdom, France, and Italy also play vital roles in the European market’s expansion, especially in the aerospace, construction, and electronics sectors.
Latin America accounts for around 6% of the market share. Brazil and Mexico are the primary drivers, supported by growing automotive and construction industries. As infrastructure projects expand in the region, demand for durable and weather-resistant materials like engineering plastics is expected to rise. However, the market growth in Latin America is moderated by economic fluctuations and limited manufacturing capabilities compared to larger markets.
The Middle East & Africa holds approximately 4% of the global market share. The market in this region is driven by infrastructure development and increasing industrialization, particularly in countries like Saudi Arabia, the UAE, and South Africa. The demand for engineering plastics in construction and oil & gas applications is prominent, given the region's focus on heavy industry. While growth is steady, it is comparatively slower due to regional economic variability and lower levels of domestic manufacturing.
Key Player Analysis:
- Ascend Performance Materials
- Chevron Phillips Chemical Company LLC
- Daicel Corporation
- Eastman Chemical Company
- Evonik Industries AG
- Ginar Technology Co., Ltd.
- Grand Pacific Petrochemical Corporation
- Mitsubishi Engineering-Plastics Corporation
- Ngai Hong Kong Company Ltd.
- Nylon Corporation of America (NYCOA)
- Piper Plastics Corp.
- Polyplastics Co., Ltd.
- Ravago
- Teknor Apex
- Trinseo LLC
- Wittenburg Group
Competitive Analysis:
The engineering plastics market is highly competitive, with major players focusing on innovation, product development, and strategic partnerships to strengthen their market positions. Leading companies, such as BASF SE, SABIC, Dow Inc., Covestro AG, and DuPont, dominate the market through comprehensive portfolios that include high-performance materials and sustainable options. These firms leverage extensive R&D capabilities to develop advanced engineering plastics that meet the evolving needs of industries like automotive, electronics, and medical. Smaller and regional players also contribute significantly, often catering to niche applications and focusing on customized solutions for local industries. Competition is intensified by the growing demand for lightweight, durable, and environmentally friendly materials, which drives continuous improvement in product offerings. Additionally, increasing investments in bio-based plastics and recycling technologies are shaping the competitive landscape as companies strive to align with global sustainability goals and meet regulatory requirements.
Recent Developments:
- In April 2024, Nylon Corporation of America (NYCOA), a specialized manufacturer of engineered nylon resins, introduced NY-Clear, an amorphous 6I/6T nylon designed for packaging and precision-molded applications.
- In November 2023, Celanese Corp. announced the global launch of two new polyamide compounds, Frianyl PA W-Series and Celanyl PA B3 GF30 E, aimed at manufacturers of electric vehicle (EV) powertrain components and batteries.
- In May 2023, Borealis, a leader in advanced and circular plastic solutions and a European market frontrunner in base chemicals, fertilizers, and plastic recycling, launched Stelora, a sustainable engineering polymer.
- In March 2023, Victrex PLC unveiled a new type of implantable PEEK-OPTIMA polymer tailored for medical device manufacturing using additive methods such as fused deposition modeling (FDM) and fused filament fabrication (FFF).
- In February 2023, Victrex PLC revealed its expansion plans for its medical division, Invibio Biomaterial Solutions, including a new product development facility in Leeds, United Kingdom.
- In February 2023, Covestro AG introduced Makrolon 3638 polycarbonate, designed for healthcare and life sciences applications, including drug delivery devices, wearable technology, and single-use containers for biopharmaceutical manufacturing.
Market Concentration & Characteristics:
The engineering plastics market is moderately concentrated, with a few dominant players, such as BASF SE, SABIC, Dow Inc., Covestro AG, and DuPont, controlling a significant market share. These leading companies benefit from extensive R&D capabilities, global distribution networks, and strong relationships with key industries like automotive, electronics, and medical, allowing them to maintain a competitive edge. Market characteristics include high barriers to entry due to the capital-intensive nature of production and the need for specialized manufacturing processes. The market is characterized by continuous innovation, with companies investing in sustainable, high-performance materials to meet regulatory standards and industry demands for lightweight, durable, and environmentally friendly products. Additionally, the engineering plastics market is shaped by stringent regulatory requirements, particularly for applications in healthcare and automotive, pushing manufacturers to prioritize quality, safety, and compliance. This competitive environment fosters steady advancements in product performance and sustainability.
Report Coverage:
The research report offers an in-depth analysis based on By type and By end-use industries. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing demand for lightweight materials in automotive and aerospace sectors will drive growth in engineering plastics.
- The rise of electric vehicles (EVs) will expand the need for high-performance plastics in battery and powertrain applications.
- Advancements in 3D printing will promote the use of engineering plastics in customized and complex part manufacturing.
- Growing consumer electronics demand will boost engineering plastics usage for durable, heat-resistant components.
- Medical industry expansion will fuel demand for biocompatible and implantable engineering plastics.
- Stringent environmental regulations will encourage innovation in recyclable and bio-based engineering plastics.
- Rapid industrialization in emerging economies will increase demand for engineering plastics in infrastructure and machinery.
- Technological advancements in polymer science will enhance product capabilities, expanding applications across industries.
- The shift towards sustainable practices will drive investments in circular and recycled plastic solutions.
- Regional manufacturing hubs in Asia-Pacific and North America will strengthen supply chains and meet rising global demand.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the size of Engineering Plastics Market?
What drives the demand for engineering plastics?
Which region leads the engineering plastics market?
What challenges does the engineering plastics market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Engineering Plastics Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Engineering Plastics Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 122,855 million → 2032: USD 212,671 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Engineering Plastics Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Engineering Plastics Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Engineering Plastics Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Engineering Plastics Market Drivers
- 3.3 Engineering Plastics Market Restraints & Challenges
- 3.4 Engineering Plastics Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Engineering Plastics Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Engineering Plastics Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Engineering Plastics category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Engineering Plastics Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Engineering Plastics Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Engineering Plastics market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Engineering Plastics Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Engineering Plastics Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Engineering Plastics Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Engineering Plastics (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Engineering Plastics Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Engineering Plastics Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Engineering Plastics Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Engineering Plastics Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Engineering Plastics Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Engineering Plastics Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Engineering Plastics Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Engineering Plastics Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Engineering Plastics Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
