
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Enterprise Metadata Management Market Size 2024 | USD 2676.9 million |
| Enterprise Metadata Management Market, CAGR | 14.6% |
| Enterprise Metadata Management Market Size 2032 | USD 7963.59 million |
Market Overview:
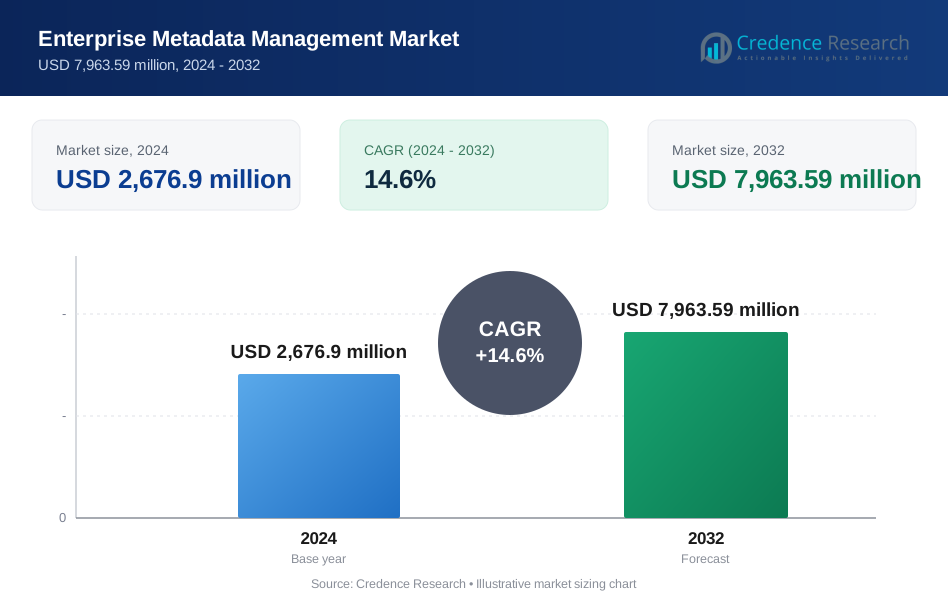
The Enterprise Metadata Management Market is projected to grow from USD 2676.9 million in 2024 to an estimated USD 7963.59 million by 2032, with a compound annual growth rate (CAGR) of 14.6% from 2024 to 2032.
The growth of the market is fueled by key drivers, including the rising adoption of big data and analytics solutions, which rely on accurate metadata for efficient operation. With the proliferation of digital transformation initiatives, enterprises are seeking metadata management tools to streamline data classification and ensure compliance with stringent regulatory requirements such as GDPR and HIPAA. Additionally, advancements in artificial intelligence (AI) and machine learning (ML) are enhancing metadata management capabilities, enabling automated tagging, improved search functionality, and data lineage tracking. These innovations are further bolstered by the growing need for real-time insights, which rely on metadata to ensure data accuracy and relevancy across enterprise systems.
Regionally, North America dominates the enterprise metadata management market, accounting for the largest share due to its advanced IT infrastructure, high adoption of data-driven technologies, and regulatory mandates. Europe follows closely, supported by robust compliance frameworks and increasing investments in metadata solutions. The Asia-Pacific region is emerging as the fastest-growing market, driven by rapid digital transformation, growing adoption of cloud-based platforms, and increasing awareness about data governance in countries like China and India. Meanwhile, Latin America and the Middle East & Africa are experiencing steady growth as enterprises in these regions embrace metadata management to improve operational efficiency and meet evolving regulatory requirements. This global spread underscores the critical role of enterprise metadata management in modern business operations.
Market Insights:
- The Enterprise Metadata Management market is projected to expand from USD 2,676.9 million in 2024 to an estimated USD 7,963.59 million by 2032, achieving a compound annual growth rate (CAGR) of 14.6%.
- The market growth is fueled by the increasing reliance on big data and analytics solutions, which utilize metadata for efficient operation. Additionally, advancements in AI and ML are enhancing metadata management capabilities, driving further adoption.
- Stringent regulations such as GDPR, HIPAA, and CCPA are propelling the demand for metadata management tools, enabling enterprises to track data usage, maintain transparency, and ensure compliance effectively.
- The proliferation of cloud-based and hybrid IT environments is a major trend. Metadata management solutions provide scalability and seamless integration, addressing the complexities of distributed systems.
- North America leads the market due to advanced IT infrastructure and high adoption of data-driven technologies. Europe follows, supported by strong compliance frameworks, while the Asia-Pacific region is the fastest-growing market.
- High implementation costs and integration challenges with legacy systems pose significant barriers, particularly for SMEs. Concerns over data security and the shortage of skilled professionals further hinder adoption.
- Despite challenges, the market is poised for substantial growth, driven by digital transformation, AI advancements, and the increasing importance of data governance in global operations.
Market Drivers:
Rising Adoption of Big Data and Analytics Solutions
The growing reliance on big data and analytics solutions across industries is a significant driver of the enterprise metadata management market. For instance, IBM's Watson Knowledge Catalog uses AI to automate data discovery, cataloging, and governance, enabling organizations to manage vast amounts of structured and unstructured data efficiently. Organizations are increasingly leveraging vast amounts of structured and unstructured data to gain actionable insights and maintain a competitive edge. Metadata management tools enable efficient organization, tagging, and integration of data, ensuring that analytics platforms deliver accurate and relevant insights. With the expanding use of predictive analytics, machine learning, and artificial intelligence, metadata management has become essential for enabling seamless data processing and improving operational efficiency.
Compliance with Stringent Data Governance Regulations
Stringent regulatory frameworks such as GDPR, HIPAA, and CCPA are compelling enterprises to adopt robust metadata management solutions. These tools play a critical role in ensuring data compliance by providing clear visibility into data lineage, usage, and access. For example, Informatica's Axon Data Governance provides comprehensive data lineage tracking and audit trails, helping organizations manage privacy requirements and maintain compliance. Metadata management systems enable organizations to track data changes, manage privacy requirements, and maintain audit trails, reducing the risk of non-compliance and associated penalties. As regulatory requirements evolve, the demand for solutions that enhance transparency and accountability in data handling continues to grow.
Advancements in Artificial Intelligence and Machine Learning
The integration of artificial intelligence (AI) and machine learning (ML) technologies is transforming the enterprise metadata management landscape. Advanced metadata tools now offer automated tagging, real-time classification, and improved search capabilities, significantly reducing manual efforts. For instance, Atlan's data catalog uses AI to automate metadata tagging and classification, enhancing data context and identifying relationships between disparate datasets. AI-powered solutions also enable predictive analytics by enhancing data context and identifying relationships between disparate datasets. These innovations not only improve operational efficiency but also enhance decision-making processes by providing timely and accurate insights, making AI-driven metadata management a critical asset for modern enterprises.
Proliferation of Cloud-Based and Hybrid Deployments
The rapid adoption of cloud computing and hybrid IT environments is driving the need for enterprise metadata management solutions. As organizations migrate workloads to cloud platforms, managing metadata across diverse and distributed systems becomes increasingly complex. Cloud-based metadata management tools offer scalability, flexibility, and seamless integration with existing infrastructure, making them a preferred choice for enterprises undergoing digital transformation. For example, Talend's cloud data integration platform supports real-time data synchronization and collaboration, ensuring that metadata remains consistent and accessible across global operations . Additionally, these solutions support real-time data synchronization and collaboration, ensuring that metadata remains consistent and accessible across global operations. This trend underscores the growing importance of metadata management in optimizing cloud-based and hybrid IT ecosystems.
Market Trends:
Adoption of Automation and AI-Driven Metadata Tools
The enterprise metadata management market is rapidly shifting towards automation, with organizations investing in AI-driven tools to streamline metadata processes. For example, Informatica's CLAIRE engine uses AI to automate metadata tagging, contextual analysis, and real-time updates, reducing manual workloads and improving data accuracy. These solutions offer features like automated tagging, contextual analysis, and real-time updates, reducing manual workloads and improving data accuracy. The incorporation of artificial intelligence and machine learning enhances metadata quality and accessibility, enabling organizations to optimize workflows and derive actionable insights efficiently.
Focus on Data Integration and Interoperability
As businesses adopt diverse systems and platforms, seamless data integration has become a top priority. Metadata management solutions are increasingly utilized to bridge data silos and create unified ecosystems, allowing smooth data flow between applications. For instance, Talend's Data Fabric platform supports comprehensive data integration and interoperability, enabling real-time data synchronization across various systems. This trend is especially significant in industries like finance, healthcare, and retail, where real-time data synchronization is critical for operations, compliance, and customer engagement. Metadata's role in enabling system interoperability is driving its adoption across multiple sectors.
Rise of Hybrid and Multi-Cloud Environments
The growing use of hybrid and multi-cloud infrastructures is shaping the metadata management landscape. Organizations are leveraging multiple cloud platforms to address specific needs, making metadata management across distributed environments more complex. Solutions that support centralized metadata control in hybrid deployments are in high demand, as they ensure data consistency and visibility across on-premise and cloud systems. For example, Google Cloud's Anthos provides a unified management platform for hybrid and multi-cloud environments, ensuring consistent metadata management and data visibility. This trend highlights the importance of metadata management in optimizing cloud strategies.
Empowerment Through Data Democratization
Organizations are increasingly adopting metadata management solutions to enable data democratization. By providing user-friendly interfaces and enhanced search capabilities, these tools empower non-technical employees to access and utilize data effectively. Alation's data catalog, for instance, offers intuitive search and discovery features, enabling users across various roles to contribute to analytics and insights. This democratized access fosters a culture of data-driven decision-making and innovation, as employees across various roles can contribute to analytics and insights. The emphasis on empowering all levels of the workforce underscores metadata management’s evolving role in driving enterprise-wide analytics adoption.
Market Challenges Analysis:
High Implementation Costs
One of the primary restraints in the enterprise metadata management market is the high cost associated with deploying these solutions. Implementing metadata management systems often requires significant investments in software, hardware, and skilled personnel. For small and medium-sized enterprises (SMEs), these upfront costs can be prohibitive, limiting adoption. Additionally, ongoing expenses for system upgrades, maintenance, and training further add to the financial burden, particularly for organizations with constrained budgets.
Complex Integration with Legacy Systems
The integration of metadata management tools with existing legacy systems poses a significant challenge. Many organizations rely on outdated or fragmented data infrastructures that are not readily compatible with modern metadata solutions. Achieving seamless interoperability requires time, expertise, and additional investments in custom development, which can delay implementation and reduce efficiency during the transition phase. This complexity often discourages businesses from adopting advanced metadata management solutions.
Data Security and Privacy Concerns
As metadata management involves handling sensitive organizational and customer data, concerns over data security and privacy remain critical. Organizations must ensure compliance with stringent regulations such as GDPR, HIPAA, and CCPA while safeguarding against cyber threats. The risk of breaches or non-compliance can lead to severe financial penalties and reputational damage. For businesses operating in highly regulated industries, addressing these security challenges requires robust encryption, access controls, and monitoring, which may strain resources.
Shortage of Skilled Professionals
The effective implementation and management of enterprise metadata systems require a specialized workforce with expertise in data management, analytics, and compliance. However, there is a global shortage of skilled professionals in these areas. This talent gap poses a significant barrier, particularly for organizations in emerging markets, where access to training and expertise is limited. The lack of skilled personnel can hinder the successful deployment and optimization of metadata management solutions.
Market Opportunities:
The enterprise metadata management market presents significant growth opportunities driven by the increasing reliance on data-driven decision-making and the proliferation of advanced technologies such as artificial intelligence (AI) and machine learning (ML). As organizations generate and manage vast volumes of structured and unstructured data, the demand for robust metadata management solutions is escalating. These solutions enable businesses to streamline data organization, improve searchability, and ensure compliance with stringent regulatory requirements. Moreover, the integration of AI and ML into metadata systems offers enhanced capabilities, including automated tagging, contextual data analysis, and predictive insights, creating new avenues for market expansion. Enterprises across industries such as BFSI, healthcare, and retail are increasingly adopting metadata solutions to enhance operational efficiency and gain a competitive edge.
Emerging markets, particularly in the Asia-Pacific region, offer lucrative opportunities for metadata management providers. Rapid digital transformation in countries like China, India, and Southeast Asian nations is driving the adoption of cloud-based and hybrid metadata solutions. Additionally, small and medium-sized enterprises (SMEs) are recognizing the value of metadata management in improving data accessibility and decision-making. With scalable and cost-effective offerings, vendors can tap into this growing segment. Furthermore, as industries like e-commerce and IT intensify their reliance on real-time data integration and governance, the need for advanced metadata systems is set to rise. These trends underline the vast potential for growth and innovation in the enterprise metadata management market.
Market Segmentation Analysis:
The Enterprise Metadata Management market is segmented by deployment type, end-user industry, and region, catering to diverse operational needs and market dynamics.
By Deployment Type, the market is divided into On-Premise and Software as a Service (SaaS). On-premise solutions offer greater control and customization, making them a preferred choice for organizations with strict regulatory requirements. In contrast, SaaS solutions are gaining popularity due to their scalability, cost-effectiveness, and ease of integration with cloud-based ecosystems.
By End-User Industry, the market spans multiple sectors, including BFSI, Healthcare & Medical, IT & Telecommunications, Media & Entertainment, Government, E-Commerce & Retail, Logistics, Pharmaceutical, and Manufacturing, along with Others. The BFSI sector leads adoption due to the need for stringent compliance and efficient data management. Healthcare and pharmaceutical industries leverage metadata management for patient data handling and regulatory adherence, while IT & Telecommunications rely on it for operational efficiency. E-commerce and retail industries utilize metadata tools for inventory management and personalized customer experiences.
Segmentation:
By Deployment Type:
- On-Premise
- Software as a Service (SaaS)
By End User industry:
- BFSI
- Healthcare & Medical
- IT & Telecommunications
- Media & Entertainment
- Government
- E-Commerce & Retail
- Logistics
- Pharmaceutical
- Manufacturing
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The Enterprise Metadata Management Market exhibits significant regional diversity, driven by varying levels of technological adoption, regulatory compliance requirements, and industry-specific demands. North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa represent key regional markets, each contributing uniquely to the sector's growth.
North America holds the largest share, accounting for approximately 40% of the global market, due to its robust technological ecosystem and the presence of leading solution providers like Oracle, IBM, and Informatica. In the United States, industries such as BFSI and healthcare account for a significant portion of metadata management adoption, fueled by regulatory requirements like the Sarbanes-Oxley Act and HIPAA. Canadian enterprises are also embracing metadata solutions, with over 65% of mid-sized organizations reporting investments in digital transformation initiatives that incorporate metadata tools.
Europe represents around 30% of the market, with countries like Germany, France, and the United Kingdom leading adoption rates. The implementation of GDPR has spurred the adoption of metadata solutions, with over 70% of enterprises reporting increased focus on data compliance and governance. The manufacturing sector, particularly in Germany, uses metadata tools to improve operational transparency, while the healthcare sector in France leverages these solutions to streamline patient data management. Government-backed digitalization programs further enhance market traction across the region.
The Asia-Pacific region is the fastest-growing market, contributing to approximately 20% of the global share. In China and India, more than 50% of large enterprises are integrating metadata management tools to support hybrid cloud deployments and real-time analytics. Japan's IT and telecom sector has also shown significant uptake, with metadata solutions being utilized to address challenges in data interoperability and integration. SMEs in the region are increasingly adopting cost-effective metadata tools, with reports showing a 45% increase in adoption rates among small businesses in 2023.
Latin America and the Middle East & Africa (MEA) collectively account for about 10% of the market share. In Latin America, countries like Brazil and Mexico are integrating metadata management solutions to enhance their growing e-commerce and retail sectors. In the MEA region, the UAE leads adoption efforts, with over 60% of enterprises in energy and financial services investing in metadata solutions to optimize data workflows and meet compliance standards. South Africa is also making strides, with increased adoption in public sector projects aimed at improving data governance.
Key Player Analysis:
- Adaptive, Inc.
- Cambridge Semantics
- Collibra
- Data Advantage Group
- Informatica LLC.
- International Business Machines Corporation
- MuleSoft, Inc.
- Oracle
- Talend
- Teradata
Competitive Analysis:
The Enterprise Metadata Management Market is characterized by the presence of both established global players and innovative niche vendors, creating a competitive and dynamic landscape. Key players such as IBM Corporation, Oracle Corporation, Informatica, SAP SE, and Alation dominate the market with robust portfolios that cater to diverse industry requirements. These companies leverage advanced technologies like AI, machine learning, and cloud integrations to enhance the functionality of their metadata management solutions, maintaining a competitive edge. For example, Oracle Enterprise Metadata Management (OEMM) is a comprehensive platform that supports metadata harvesting from various sources, including relational databases, Hadoop, ETL, and BI tools. The market is also witnessing increasing competition from emerging vendors specializing in specific applications or industry verticals. Companies like Collibra, Talend, and Adaptive focus on delivering agile and cost-effective solutions tailored to the needs of small and medium-sized enterprises. Strategic partnerships, product innovation, and geographical expansion are common strategies employed by competitors to capture market share. This competitive environment is driving innovation, ensuring continuous improvements in metadata management technologies.
Recent Developments:
- In February 2023, Alation Inc. launched Alation Marketplaces, a tool that enables users to explore external datasets from vendors like Snowflake, AWS, and data.gov within the Alation Data Catalog, enhancing analysis and data discovery.
- In February 2023, SAP collaborated with Dimexon to migrate its operations to the SAP cloud, supporting sustainable luxury initiatives by automating sourcing, inventory tracking, and improving customer experiences.
- In May 2022, Cambridge Semantics partnered with Point72, licensing its Anzo® knowledge graph technology to enhance compliance tools with data integration, business intelligence, and graph analytics.
Market Concentration & Characteristics:
The Enterprise Metadata Management Market is moderately concentrated, with a mix of global leaders and specialized vendors driving innovation and competition. Major players such as IBM Corporation, Oracle Corporation, Informatica, and SAP SE dominate the market due to their extensive portfolios, strong brand presence, and widespread adoption across industries. These companies benefit from economies of scale and invest heavily in research and development to maintain their competitive edge. The market also features niche players like Collibra, Alation, and Talend, which focus on delivering flexible and cost-effective solutions, particularly appealing to small and medium-sized enterprises. The increasing demand for cloud-based and AI-driven solutions is encouraging both established and emerging companies to adopt innovative approaches. Strategic alliances, acquisitions, and regional expansions are prevalent, shaping the competitive dynamics. This blend of global and regional vendors ensures a dynamic market environment, fostering continuous technological advancements.
Report Coverage:
The research report offers an in-depth analysis based on By Deployment Type and By End User Industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The integration of artificial intelligence and machine learning will enhance metadata tools, enabling automation and predictive analytics for better decision-making.
- Growing adoption of hybrid and multi-cloud environments will drive demand for centralized metadata management solutions.
- Regulatory frameworks like GDPR and CCPA will increase the need for compliance-focused metadata systems across industries.
- Expansion of digital transformation initiatives in emerging markets will create significant opportunities for vendors offering scalable and cost-effective solutions.
- The rise of self-service analytics will fuel demand for metadata tools that empower non-technical users to access and utilize data effectively.
- Increasing investments in data governance frameworks will boost adoption in highly regulated sectors such as BFSI, healthcare, and government.
- Innovations in real-time data integration and interoperability will expand the role of metadata management in dynamic IT ecosystems.
- Small and medium-sized enterprises will increasingly adopt cloud-based metadata solutions to enhance operational efficiency.
- Strategic partnerships and acquisitions will shape competitive dynamics, enabling vendors to expand their technological capabilities and market reach.
- Growing awareness of data democratization will reinforce the importance of metadata management as a cornerstone of enterprise-wide analytics strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Adoption of Big Data and Analytics Solutions
Enterprises are increasingly leveraging big data and analytics platforms, which require robust metadata management to organize, tag, and integrate vast volumes of structured and unstructured data, ensuring accurate and actionable insights.
Compliance with Stringent Data Governance Regulations
Regulatory frameworks such as GDPR, HIPAA, and CCPA are compelling organizations to implement metadata management solutions that provide data lineage, audit trails, and transparency, reducing the risk of non-compliance and penalties.
Advancements in Artificial Intelligence and Machine Learning
AI and ML are enhancing metadata management by enabling automated tagging, real-time classification, and improved search capabilities, which reduce manual effort and improve operational efficiency.
Proliferation of Cloud-Based and Hybrid Deployments
The shift to cloud and hybrid IT environments increases the complexity of managing metadata across distributed systems, driving demand for scalable, integrated metadata management tools that ensure consistency and accessibility.
Empowerment Through Data Democratization
Organizations are adopting metadata management solutions with user-friendly interfaces and enhanced search features, empowering non-technical users to access and utilize data, fostering a culture of data-driven decision-making.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Enterprise Metadata Management market?
What are the key drivers of this market?
Which region dominates the market?
What are the challenges faced by the market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Deployment Type
- 1.2.1 On-Premise
- 1.2.2 Software as a Service (SaaS)
- 1.3 By End User Industry
- 1.3.1 BFSI
- 1.3.2 Healthcare & Medical
- 1.3.3 IT & Telecommunications
- 1.3.4 Media & Entertainment
- 1.3.5 Government
- 1.3.6 E-Commerce & Retail
- 1.3.7 Logistics
- 1.3.8 Pharmaceutical
- 1.3.9 Manufacturing
- 1.3.10 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,676.9 million → 2032: USD 7,963.59 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Enterprise Metadata Management Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Enterprise Metadata Management Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Enterprise Metadata Management Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Enterprise Metadata Management Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Enterprise Metadata Management Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Enterprise Metadata Management Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Enterprise Metadata Management Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Enterprise Metadata Management Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,676.9 million → 2032: USD 7,963.59 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Enterprise Metadata Management Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Deployment Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 On-Premise
- 12.3.7.2 Software as a Service (SaaS)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User Industry - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 BFSI
- 12.4.7.2 Healthcare & Medical
- 12.4.7.3 IT & Telecommunications
- 12.4.7.4 Media & Entertainment
- 12.4.7.5 Government
- 12.4.7.6 E-Commerce & Retail
- 12.4.7.7 Logistics
- 12.4.7.8 Pharmaceutical
- 12.4.7.9 Manufacturing
- 12.4.7.10 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Enterprise Metadata Management End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Enterprise Metadata Management Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Enterprise Metadata Management Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Enterprise Metadata Management Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 IBM Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Oracle Corporation
- 18.4 Informatica LLC
- 18.5 SAP SE
- 18.6 Alation Inc.
- 18.7 Collibra
- 18.8 Talend
- 18.9 Cambridge Semantics
- 18.10 Adaptive, Inc.
- 18.11 Teradata
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

