
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Graphics Card Market Size 2023 | USD 33,538.53 million |
| Graphics Card Market, CAGR | 5.90% |
| Graphics Card Market Size 2032 | USD 57,038.52 million |
Market Overview
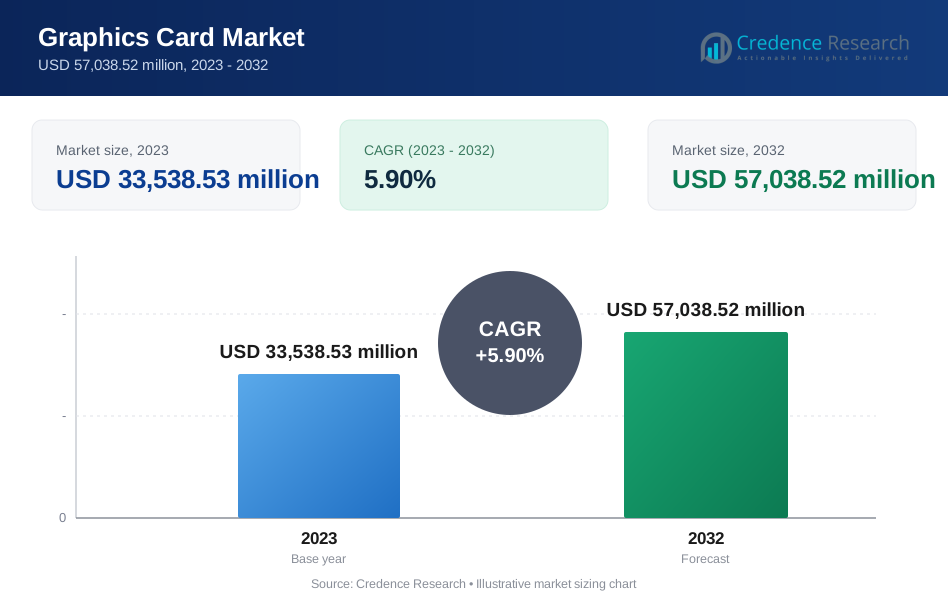
The graphics card market is projected to surge from USD 33,538.53 million in 2023 to USD 57,038.52 million by 2032, growing at a CAGR of 5.90%. Graphics processing units (GPUs), central to this growth, have transcended their traditional roles, rendering not just images but facilitating the complex calculations necessary for advanced graphics rendering and computational tasks beyond gaming or content creation. This expansion in application scope is pivotal, catering to a diverse range of industries from gaming, where the quest for immersive, real-time graphics is unending, to professional sectors like video editing, 3D rendering, and design, demanding advanced graphics solutions for increasingly complex projects.
However, this market's trajectory is not devoid of challenges. Supply chain disruptions, the fluctuating availability of semiconductors, and the steep costs of premium graphics cards represent significant hurdles, potentially impeding market momentum. Moreover, the rapid pace of technological advancements, while a boon for innovation, poses a dilemma for consumers wary of obsolescence, potentially delaying investment in new technology. In response to these challenges, industry leaders such as NVIDIA, AMD, and Intel are spearheading initiatives in research and development, pushing the boundaries of what's possible in graphics processing technology. These efforts are complemented by strategic partnerships and a commitment to sustainability, reflecting a shift towards eco-friendly manufacturing practices in response to global environmental concerns and consumer expectations. This strategic pivot not only aims to navigate current market complexities but also to redefine the potential applications and efficiency of graphics technology.
Looking forward, the graphics card market is poised on the brink of a transformative era. The integration of AI and ML technologies into graphics processing heralds a new frontier for computational capabilities, enabling more efficient data analysis and propelling innovations across a spectrum of fields, from healthcare to autonomous driving. The relentless demand for higher computational power and graphic fidelity across consumer and professional segments, coupled with advancements in virtual reality (VR) and augmented reality (AR), promises to unlock new applications and experiences. This ongoing evolution is further amplified by the industry's move towards sustainability, adopting more energy-efficient practices in production and product development, aligning with broader global sustainability goals. Despite facing its share of obstacles, the graphics card market's outlook remains overwhelmingly optimistic, propelled by a blend of technological breakthroughs, strategic industry responses to external pressures, and the expanding role of graphics processing in shaping both everyday experiences and the technologies that will define the future. As this market continues to navigate its complexities, its growth and innovation trajectory underscores a vibrant sector that is not only responding to current trends and challenges but is also actively shaping the technological landscape of tomorrow.
Segmentation Analysis
By Type:
Discrete Graphics Processing Units (GPUs) represent a significant segment of the market, characterized by their standalone nature. Unlike integrated GPUs, discrete GPUs are separate components installed in a system to enhance graphics performance. This type is preferred for high-end gaming, professional graphics work, and complex computational tasks requiring superior graphics processing power. Integrated GPUs, on the other hand, are built into the processor and share memory with the CPU, making them more cost-effective and energy-efficient, albeit with lower performance compared to discrete GPUs. They are commonly found in laptops, mobile PCs, and entry-level desktops, catering to users with basic graphics processing needs.
By Application:
In the diverse landscape of the Graphics Card Market, each segment caters to unique demands: Desktops remain the bastion for high-performance discrete GPUs, serving gamers, content creators, and professionals in need of superior graphics capabilities, driven by the quest for more immersive experiences and powerful creative tools. Meanwhile, mobile PCs have embraced both integrated and discrete GPUs, balancing portability with the need for enhanced gaming and professional graphics performance on the move. Workstations rely on discrete GPUs for complex tasks like 3D rendering and video editing, necessitating high-quality graphics output. The servers/datacenter segment has turned to GPUs for their parallel processing power, accelerating big data analytics, AI, and machine learning workloads.
Segments:
By Type:
- Discrete GPUs
- Integrated GPUs
By Application:
- Desktop
- Mobile PC
- Workstation
- Servers/datacenter
- Automotive/self-Driving Vehicles
By Region:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Market Drivers
The Gaming Industry: A Catalyst for Growth
The gaming industry stands as the cornerstone of the graphics card market, propelling demand to unprecedented heights. Gamers, in their quest for the ultimate gaming experience, continuously seek the latest and most potent graphics cards. This pursuit is fueled by game developers who push the boundaries of realism and graphical demands in their creations. As these games evolve to offer more intricate and visually stunning experiences, the requirement for advanced graphics cards escalates, ensuring the gaming sector remains the most significant driver of market growth. For example, the introduction of GPU with real-time ray tracing and artificial intelligence capabilities is expected to drive market growth. In September 2021, NVIDIA launched the GeForce RTX 3080 Ti graphics card with advanced features such as ray tracing, AI rendering, and high-speed memory.
Technological Advancements: Shaping the Future
The relentless pace of technological advancements significantly propels the graphics card market forward. Innovations such as cutting-edge manufacturing processes, novel memory technologies, and groundbreaking new architectures empower manufacturers to produce graphics cards that are not only more powerful but also more energy-efficient and cost-effective. For example, NVIDIA’s RTX 4090 is undoubtedly the fastest gaming GPU in the world, but it also has a 450W TDP, making it one of the most power-hungry GPUs we have ever seen. These advancements not only meet the current demands of various applications but also anticipate future needs, ensuring the graphics card market remains at the forefront of technological innovation. Emerging technologies like DLSS (Deep Learning Super Sampling) by Nvidia, FSR (FidelityFX Super Resolution) by AMD, and XeSS (Xe Super Sampling) by Intel are reshaping the GPU market by enhancing image quality and speed, providing gamers with an immersive and high-speed gaming experience.
The Emergence of VR and AR: Expanding Horizons
Virtual Reality (VR) and Augmented Reality (AR) represent the frontier of digital interaction, offering immersive experiences that blur the lines between the virtual and the real world. However, these technologies place significant demands on graphics processing, requiring powerful graphics cards to render complex virtual environments in real-time. As VR and AR technologies gain popularity and their applications extend beyond entertainment to fields such as education, healthcare, and engineering, the demand for high-performance graphics cards is set to surge. This growing demand underscores the importance of continuous innovation in the graphics card market to support the development and expansion of VR and AR technologies.
The Rise of eSports: Competitive Gaming's Impact
eSports, the competitive arena of video gaming, has emerged as a global phenomenon, drawing players and spectators alike. Professional eSports athletes require the highest caliber of graphics cards to compete effectively, where split-second decisions can mean the difference between victory and defeat. The rise of eSports has not only popularized competitive gaming but also significantly contributed to the demand for high-end graphics cards. As eSports continue to captivate a broader audience and gain recognition as a legitimate competitive sport, its influence on the graphics card market is undeniable, driving manufacturers to cater to the high-performance needs of professional gamers.
Graphics-Intensive Industries: Broadening the Demand
Beyond gaming and entertainment, a myriad of industries relies heavily on graphics cards for their operations. Sectors such as animation, film production, architectural visualization, and data analysis utilize advanced graphics processing for creating detailed visual content and handling complex computational tasks. As these industries continue to expand and evolve, the demand for powerful graphics cards correspondingly increases. This diversification of demand highlights the versatility of graphics cards and their critical role in supporting a wide range of professional applications, further broadening the market's growth prospects.
Market Trends
Gaming: The Undisputed Catalyst
At the heart of this booming market is the gaming industry, which remains the most potent force driving demand for advanced graphics cards. The gaming sector’s relentless pursuit of realism and immersive experiences compels manufacturers to continuously push the boundaries of graphics card performance. As gamers worldwide seek to elevate their gaming experience with the latest high-definition titles, the pressure on manufacturers to innovate and release new generations of increasingly powerful GPUs intensifies. For example, in September 2021, NVIDIA launched the GeForce RTX 3080 Ti graphics card with advanced features such as ray tracing, AI rendering, and high-speed memory. This cycle of demand and innovation ensures that gaming retains its crown as a critical driver of the graphics card market, influencing product development strategies and technological advancements.
The Rising Tide of VR and AR Technologies
The advent and growing popularity of Virtual Reality (VR) and Augmented Reality (AR) technologies represent a significant market trend, opening new avenues for the application of powerful graphics cards. VR and AR technologies, known for their ability to create deeply immersive digital experiences, require substantial processing capabilities to render complex virtual environments in real-time. As these technologies become more mainstream, spanning entertainment, education, healthcare, and more, the demand for GPUs capable of supporting their processing needs is set to rise sharply. The growing demand for advanced technologies, like AR, VR, and AI, is further fueling the GPU demand, as these technologies require high-speed analysis, for which GPU is an ideal option. This trend not only expands the market for graphics cards but also drives innovation in GPU development to meet the unique demands of VR and AR applications. For example, companies in the gaming industry, such as NVIDIA Corporation, Advanced Micro Devices, and Huawei Technologies, are investing in the development of advanced hardware based on GPU-as-a-service cloud capabilities. This is expected to boost virtual reality (VR) in the gaming market share.
Diversification Through High-Memory GPUs
Another notable trend is the healthcare sector's increasing reliance on high-memory graphics cards, a development that highlights the market's diversification beyond traditional gaming applications. High-memory GPUs are becoming essential tools in medical imaging and analysis, facilitating the processing of large datasets and complex visualizations necessary in modern healthcare diagnostics and research. This shift towards high-memory graphics solutions in healthcare and other non-gaming sectors illustrates the broadening scope of applications for graphics cards, signaling a move towards more specialized, high-performance GPUs tailored to specific industry needs.
Easing Chip Shortages and Market Dynamics
A pivotal trend affecting the graphics card market is the gradual easing of the chip shortages that have previously constrained production and inflated prices. As the situation improves, the market is poised to experience increased availability of graphics cards, potentially leading to more competitive pricing and accessibility for consumers and industries alike. This shift could have far-reaching implications, enabling broader adoption of advanced graphics solutions across various sectors and driving further market growth.
Market Restraints and Challenges
Semiconductor Shortage: A Persistent Obstacle
A critical challenge that has recently come to the forefront is the semiconductor shortage, which acts as a major bottleneck in the production of graphics cards. Semiconductors serve as the backbone of graphics cards, and their limited availability has led to significant supply constraints. This shortage not only hampers the ability of manufacturers to meet the surging demand but also results in inflated prices, making it increasingly difficult for consumers to purchase graphics cards at retail prices. The ramifications of this shortage extend beyond mere inconvenience, affecting the entire supply chain and exacerbating the challenge of market saturation.
The High Cost of Cutting-Edge Technology
Moreover, the financial barrier posed by high-end graphics cards cannot be overlooked. The steep price tags attached to these advanced components deter a significant portion of potential buyers, particularly those who are budget-conscious or skeptical about the longevity of their investment given the rapid pace of technological evolution. This dynamic serves to limit market penetration and curtails the accessibility of the latest graphics technologies, potentially stifacing innovation and the adoption of new gaming or professional applications that require high-performance graphics processing capabilities.
Power Consumption and Heat: Practical Concerns
High-performance graphics cards are also notorious for their substantial power consumption and heat generation. This not only translates into higher operational costs, in terms of electricity consumption, but also necessitates the implementation of sophisticated cooling solutions to mitigate heat build-up. Such requirements add layers of complexity and additional expenses to the construction of PCs equipped with these powerful GPUs, presenting a significant challenge to both enthusiasts and professionals seeking to leverage top-tier graphics performance.
Compatibility, Driver Support, and Cryptocurrency Mining
Another set of challenges revolves around compatibility and driver support. Ensuring that a new graphics card seamlessly integrates with existing PC components can be a daunting task, compounded by the necessity for continuous driver updates to maintain optimal performance. Moreover, the rise of cryptocurrency mining has introduced a new dimension to the market's challenges. The intense demand for graphics cards from miners competes directly with traditional consumer bases, such as gamers, exacerbating stock shortages and further inflating prices. This competition not only disrupts availability but also complicates market dynamics, affecting both manufacturers' strategies and consumers' access to new technologies.
Key Players
- Intel Corporation
- Advanced Micro Devices, Inc.
- Nvidia Corporation
- Imagination Technologies Limited
- Samsung Electronics Co. Ltd
- Microsoft Corporation
- Apple Inc.
- Hewlett Packard Enterprise
- Sony Corporation
- Qualcomm Technologies, Inc.
Recent Developments
In October 2023, Advanced Micro Devices (AMD) Inc. took a pivotal step by acquiring Nod.ai, a startup known for its development of open-source software designed to accelerate artificial intelligence (AI) models. While the financial details of the acquisition remain undisclosed, this move is strategically positioned to enhance AMD's competitiveness in the AI accelerators market, potentially rivaling NVIDIA's stronghold in graphics card technologies.
In February 2024, the landscape of the graphics card market witnessed another innovative leap, this time by Japanese manufacturer Sycom. Sycom introduced the RTX 4080 Super graphics card as an integral part of its G-Master Hydro series. This launch is notable not just for the graphics card's high-end performance capabilities but also for its integration of proprietary liquid cooling technology. This innovation aims to address two critical concerns in high-performance computing: reducing operational temperatures and minimizing fan noise during peak loads.
In March 2024, NVIDIA announced the launch of its RTX 4080 SUPER graphics card marking the highest-end model within its esteemed RTX 40 series. This launch signifies NVIDIA's ongoing commitment to pushing the boundaries of graphics processing technology, further cementing its leadership position in the market. The RTX 4080 SUPER is expected to set new benchmarks in gaming, content creation, and professional graphics applications, offering unparalleled performance and efficiency.
Regional Analysis
North America
In North America, the demand for high-performance graphics cards has been consistently strong, driven by the region's thriving gaming culture and the presence of major technology companies. According to recent market reports, North America holds a significant market share of approximately 35%, with NVIDIA and AMD leading the pack as the dominant players. The adoption of cutting-edge technologies, such as ray tracing and AI-accelerated graphics, has further fueled the demand for advanced graphics solutions in this region.
Asia-Pacific
The Asia-Pacific region has emerged as a formidable force in the graphics card market, accounting for a substantial market share of around 30%. This region's growth can be attributed to the burgeoning gaming industry, particularly in countries like China, South Korea, and Japan. Additionally, the increasing demand for graphics-intensive applications in various sectors, including multimedia, engineering, and scientific computing, has propelled the market's expansion. Major players in the region include NVIDIA, AMD, and several local manufacturers, such as Colorful and Galaxy, catering to the diverse needs of consumers and professionals alike.
Europe
Europe, with its well-established gaming culture and a strong presence of technology companies, holds a market share of approximately 20% in the graphics card market. Countries like Germany, the United Kingdom, and France have been key contributors to this region's growth. The demand for high-end graphics cards for gaming, content creation, and professional applications has been steadily increasing. NVIDIA and AMD maintain a significant presence in this region, while other players, such as ASUS and Gigabyte, have also gained traction, offering a wide range of graphics solutions.
The Middle East and Africa
The Middle East and Africa region, although smaller in comparison to others, has been witnessing a gradual rise in demand for graphics cards. With a market share of around 8%, this region presents opportunities for growth, driven by factors such as increasing disposable incomes, the adoption of gaming culture, and the expansion of multimedia and entertainment industries. Major players in this region include NVIDIA, AMD, and local distributors and system integrators catering to the region's diverse consumer base.
Latin America
Latin America, with a market share of approximately 7%, has shown promising growth potential in the graphics card market. Countries like Brazil, Mexico, and Argentina have been key contributors to this region's demand. The increasing popularity of gaming, multimedia applications, and the adoption of advanced technologies have fueled the need for more powerful graphics solutions. While NVIDIA and AMD dominate the market, local manufacturers and distributors have also started to gain traction, offering affordable options to cater to the region's diverse consumer base.
Future Outlook
- The graphics card market is projected to experience significant growth, driven by escalating demands in gaming, professional visualization, and AI applications.
- Advancements in GPU technology will lead to more powerful and energy-efficient graphics cards, enhancing performance across various applications.
- Virtual reality (VR) and augmented reality (AR) technologies will become more mainstream, increasing the demand for high-performance graphics cards capable of supporting immersive experiences.
- The adoption of graphics cards in data centers for AI and machine learning workloads will continue to rise, pushing the boundaries of computational capabilities.
- The automotive sector's shift towards autonomous vehicles will boost the demand for GPUs, given their role in processing the vast amounts of data required for self-driving technology.
- Competition among leading manufacturers like NVIDIA, AMD, and Intel will intensify, spurring innovation and potentially leading to more competitive pricing for consumers.
- Cloud gaming services will gain popularity, requiring robust backend graphics processing units to deliver high-quality gaming experiences to a broader audience.
- The introduction of more advanced display technologies, such as 8K resolution, will necessitate more powerful graphics solutions, driving further market growth.
- Environmental sustainability concerns will influence the development of more energy-efficient graphics cards, aligning with global efforts to reduce carbon footprints.
- Supply chain improvements are expected to alleviate recent shortages, stabilizing prices and making high-end GPUs more accessible to a wider range of consumers.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Gaming Industry Expansion
The gaming sector's demand for high-performance, realistic graphics continues to drive the need for advanced graphics cards, as gamers and developers push for more immersive and visually complex experiences.
Technological Advancements in GPUs
Continuous innovation in GPU architecture, memory technologies, and manufacturing processes is enabling the production of more powerful and energy-efficient graphics cards, meeting the evolving needs of both consumer and professional applications.
Growth of VR and AR Applications
The increasing adoption of virtual reality and augmented reality across entertainment, education, and healthcare is fueling demand for high-end graphics cards capable of rendering complex, real-time environments.
AI and Data Center Adoption
Graphics cards are increasingly used in data centers for AI, machine learning, and big data analytics, expanding the market beyond traditional gaming and professional visualization segments.
Rise of eSports and Competitive Gaming
The global popularity of eSports is driving demand for top-tier graphics cards among professional gamers and enthusiasts, as performance advantages can directly impact competitive outcomes.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Graphics Card Market between 2023 and 2032?
What factors are driving the growth of the Graphics Card Market?
Who are the major players in the Graphics Card Market?
How is the availability of Graphics Card Market expanding, and through what channels?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Discrete GPUs
- 1.2.2 Integrated GPUs
- 1.3 By End User
- 1.3.1 Gaming
- 1.3.2 Professional Visualization
- 1.3.3 Data Center/AI
- 1.3.4 Automotive
- 1.3.5 Healthcare
- 1.4 By Application
- 1.4.1 Desktop
- 1.4.2 Mobile PC
- 1.4.3 Workstation
- 1.4.4 Servers/datacenter
- 1.4.5 Automotive/self-Driving Vehicles
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 33,538.53 million → 2032: USD 57,038.52 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Graphics Card Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Graphics Card Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Graphics Card Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Graphics Card Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Graphics Card Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Graphics Card Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Graphics Card Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Graphics Card Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 33,538.53 million → 2032: USD 57,038.52 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Graphics Card Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Discrete GPUs
- 12.3.7.2 Integrated GPUs
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Gaming
- 12.4.7.2 Professional Visualization
- 12.4.7.3 Data Center/AI
- 12.4.7.4 Automotive
- 12.4.7.5 Healthcare
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Desktop
- 12.5.7.2 Mobile PC
- 12.5.7.3 Workstation
- 12.5.7.4 Servers/datacenter
- 12.5.7.5 Automotive/self-Driving Vehicles
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Graphics Card End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Graphics Card Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Graphics Card Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Graphics Card Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Nvidia Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Advanced Micro Devices, Inc. (AMD)
- 18.4 Intel Corporation
- 18.5 Imagination Technologies Limited
- 18.6 Samsung Electronics Co. Ltd
- 18.7 Apple Inc.
- 18.8 Qualcomm Technologies, Inc.
- 18.9 Sony Corporation
- 18.10 ASUS
- 18.11 Gigabyte Technology
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

