
Market Overview:
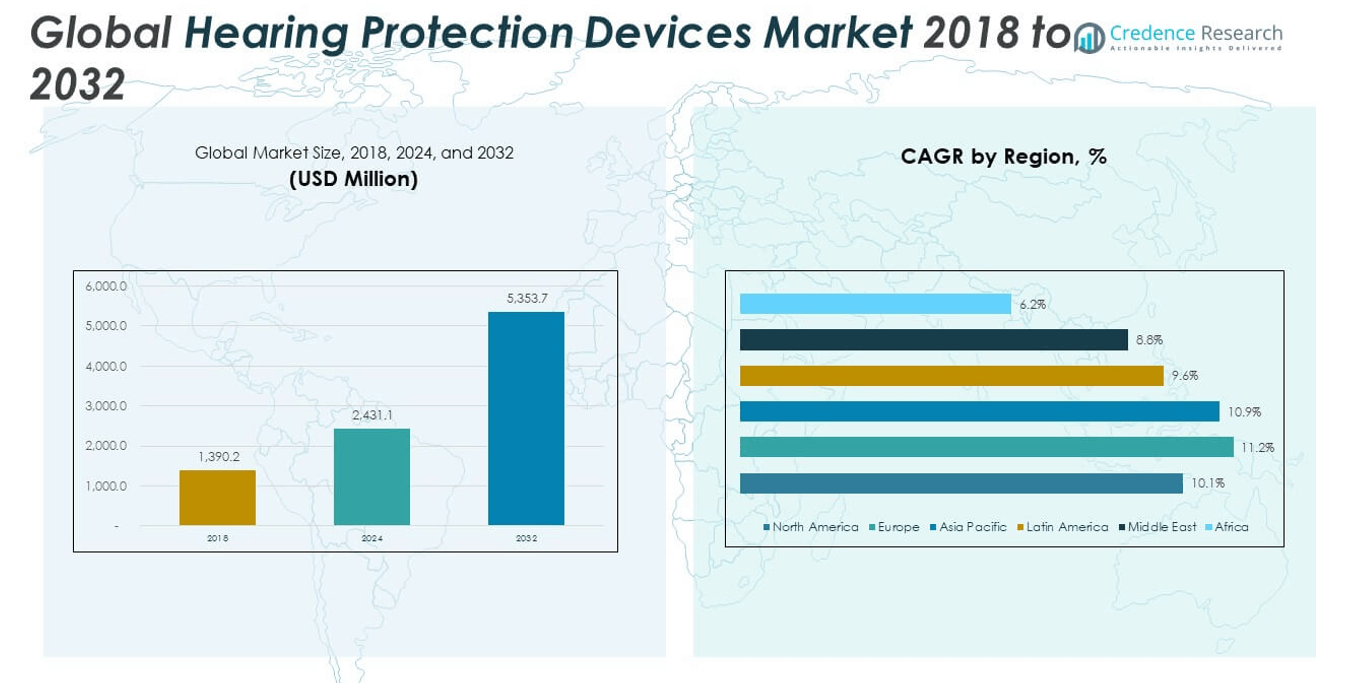
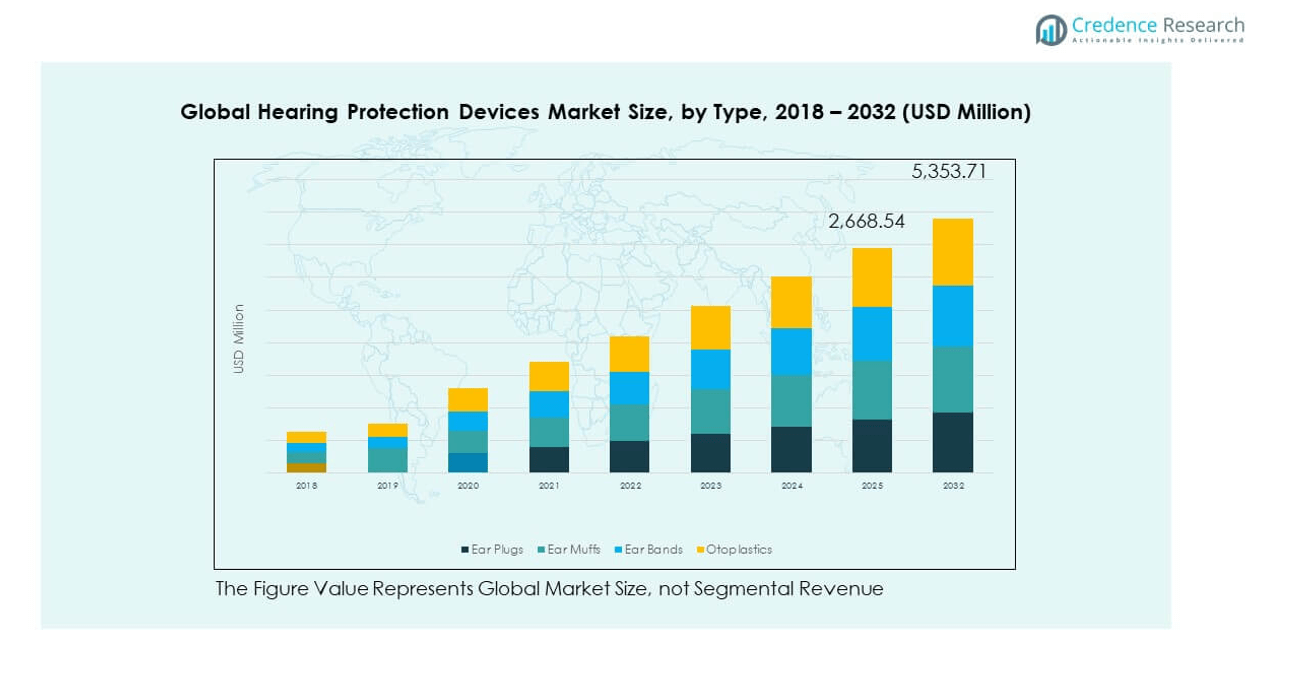
The Hearing Protection Devices Market size was valued at USD 1,390.2 million in 2018 to USD 2,431.1 million in 2024 and is anticipated to reach USD 5,353.7 million by 2032, at a CAGR of 10.46% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hearing Protection Devices Market Size 2024 | USD 2,431.1 million |
| Hearing Protection Devices Market, CAGR | 10.46% |
| Hearing Protection Devices Market Size 2032 | USD 5,353.7 million |
The market is witnessing robust growth due to increasing awareness of occupational noise-induced hearing loss and stricter government regulations mandating the use of hearing protection in industrial settings. Rising demand from construction, mining, and manufacturing sectors is significantly driving adoption. Innovations in earplug and earmuff designs that enhance comfort and communication capabilities have made these devices more appealing. Additionally, rising military spending on soldier safety and growing usage of personal protective equipment across sectors such as aviation and oil & gas further contribute to market expansion.
North America leads the hearing protection devices market due to stringent workplace safety regulations and the strong presence of key manufacturers. Europe follows closely, driven by robust industrial activity and regulatory enforcement. Asia Pacific is emerging as a high-growth region, with expanding manufacturing hubs in China, India, and Southeast Asia, alongside increasing worker safety awareness. Latin America and the Middle East & Africa show moderate growth but are gaining traction as regional governments and private industries increase investment in occupational health and safety initiatives.
Market Insights:
- The Hearing Protection Devices Market was valued at USD 2,431.1 million in 2024 and is projected to reach USD 5,353.7 million by 2032, growing at a CAGR of 10.46%.
- Increasing workplace safety regulations across manufacturing, mining, and construction sectors are driving consistent demand for hearing protection.
- Rising military investment in tactical communication-integrated hearing devices is supporting market expansion.
- Discomfort during prolonged use and communication interference continue to hinder widespread user compliance.
- North America leads the market due to strong regulatory frameworks and high industrial safety standards.
- Europe follows with rapid adoption of eco-friendly and smart hearing protection solutions aligned with occupational health goals.
- Asia Pacific is emerging quickly due to expanding industrialization, infrastructure development, and government-led safety initiatives.
Market Driver:
Stringent Occupational Safety Regulations Fueling Demand Across Industries
Governments across major economies are enforcing stricter occupational safety standards to prevent hearing loss among industrial workers. Regulatory bodies such as OSHA and NIOSH mandate employers to provide hearing protection when noise levels exceed permissible exposure limits. This legal framework compels industries to integrate hearing protection devices into standard PPE kits. The Hearing Protection Devices Market benefits from these mandates, especially in high-risk sectors like construction, mining, and manufacturing. Companies seek compliance to avoid legal penalties and compensation costs. Rising litigation and insurance risks also push enterprises to adopt effective safety gear. It drives demand for certified and performance-tested hearing protection solutions. The industrial sector continues to invest in safety programs that align with regulatory expectations.
- For instance, 3M’s PELTOR™ X Series earmuffs have been tested to provide a noise reduction rating (NRR) of up to 31 decibels, exceeding OSHA’s minimum recommended rating for high-noise environments, and are widely adopted as part of mandated PPE in U.S. manufacturing plants.
Military and Defense Expenditure Enhancing Tactical Safety Equipment
Global defense organizations are prioritizing soldier health and operational effectiveness, driving demand for advanced hearing protection. Battlefield environments expose personnel to high-decibel noise from firearms, explosives, and machinery. The Hearing Protection Devices Market responds with tactical solutions offering both noise attenuation and situational awareness. Military-grade devices now integrate communication systems to enable command coordination without compromising ear safety. Procurement budgets in defense have expanded, supporting innovation in combat-ready hearing gear. Governments in the U.S., UK, China, and India are investing in smart hearing protection to reduce auditory injuries. These technologies are also tailored to harsh field conditions and long wear durations. Defense-focused R&D continues to create momentum for market growth.
- For instance, Gentex Corporation’s Ops-Core AMP Communication Headset is equipped with 3D Hear-Through Technology that preserves natural hearing and delivers over 22 dB of consistent attenuation, and has been selected as standard issue for U.S. Special Operations Command since 2020.
Increased Awareness of Occupational Hearing Loss Among Workers
Worker awareness of the long-term impact of noise-induced hearing loss has significantly increased in recent years. This shift in perception influences employers to proactively adopt protective measures. The Hearing Protection Devices Market benefits from this behavioral change as employee demand for safe working environments grows. Workers prefer companies that prioritize health and safety compliance. Training programs and awareness campaigns help reinforce the importance of ear protection. Labor unions also advocate for improved auditory safety in industrial settings. Industries now consider hearing protection as a core part of their employee welfare policies. This changing attitude translates into consistent procurement of hearing safety devices across job roles.
Growth in Construction, Aviation, and Oil & Gas Activities
Expansion in sectors such as construction, aviation, and oil & gas is generating substantial demand for hearing protection. These industries involve environments where high-decibel machinery and equipment are routinely used. The Hearing Protection Devices Market addresses the need for effective, comfortable, and job-specific solutions. Earplugs and earmuffs designed for prolonged use find high acceptance in field operations. Global infrastructure development and energy exploration projects are expanding noise-prone work areas. Engineers, pilots, and drilling operators increasingly rely on reliable auditory safety equipment. Employers prioritize operational continuity while safeguarding their workforce from occupational hazards. Market penetration improves as vendors develop application-specific models with improved ergonomics.
Market Trends:
Integration of Smart Features and Connectivity in Hearing Devices
The industry is shifting towards smart hearing protection devices equipped with sensors and wireless connectivity. These devices collect data on noise exposure, which employers use to assess risks and improve workplace safety plans. The Hearing Protection Devices Market adopts technologies like Bluetooth, real-time noise monitoring, and cloud integration to enhance product functionality. Manufacturers design solutions compatible with mobile apps and central dashboards. Industrial firms prefer data-driven tools that support compliance reporting and predictive safety measures. These devices also enable usage tracking and maintenance alerts. Market participants invest in software-enabled safety gear to differentiate their offerings. Smart PPE is gaining relevance in digital transformation strategies of industrial operations.
Customization and Ergonomic Advancements Supporting User Comfort
Demand for customized hearing protection is rising as users seek personalized fit and extended comfort. Traditional one-size-fits-all devices are being replaced by options molded to individual ear canals. The Hearing Protection Devices Market sees a shift toward ergonomically designed products that reduce fatigue during prolonged use. Soft materials, adjustable bands, and pressure-equalizing mechanisms are key innovations. This trend is especially visible in healthcare, aerospace, and military sectors. Workers are more likely to comply with safety practices when devices are comfortable. Custom-fit solutions also improve noise attenuation by minimizing sound leakage. Vendors focus on biometric scans and 3D printing for tailoring hearing protection gear. Product differentiation now emphasizes comfort without compromising safety.
- For example, Phonak Serenity Choice™ Custom earplugs are custom-molded to the unique shape of your ear canal, ensuring an unbeatable fit and maximum comfort. You can even choose from a variety of medical-grade materials, designs, and colors to match your preferences.
Increased Demand for Reusable and Eco-Friendly Hearing Products
The sustainability movement is influencing design and material choices across hearing protection solutions. Reusable earplugs and recyclable earmuffs are gaining traction in corporate procurement. The Hearing Protection Devices Market reflects growing demand for environmentally responsible PPE options. Manufacturers develop durable products that withstand multiple cleaning cycles without performance loss. Disposable items are being replaced in sectors with strong ESG goals. Green certifications and carbon-footprint transparency now influence buyer decisions. Corporates are integrating sustainability into safety budgets, influencing vendor selection. Eco-conscious designs also align with cost-saving strategies for long-term usage. Suppliers are optimizing packaging and production processes to meet these new expectations.
Adoption of Hearing Protection in Non-Industrial Settings
The market is expanding beyond traditional industrial environments into entertainment, sports, and personal use. Consumers now purchase hearing protection for concerts, shooting ranges, and motorsports. The Hearing Protection Devices Market adapts to this trend by offering lifestyle-oriented models with fashionable designs. Lightweight, discreet, and color-customizable earplugs appeal to the general public. Noise sensitivity awareness is growing, encouraging use in schools, airports, and public transit. Musicians and performers seek specialized in-ear protection that preserves audio fidelity. Recreational users also favor products with portable cases and user-friendly interfaces. This diversification broadens market reach and generates new consumer segments outside occupational settings.
- For instance, Eargasm High Fidelity Earplugs have documented wide adoption among lifestyle, entertainment, and recreational users. The official site confirms “over 1 million happy ears and counting,” and they are rated at an NRR of 16 dB, with standard attenuation of 21 dB using the high-dB filter insert. Eargasm’s range is popular with music festival goers, event attendees, and professionals who require hearing protection that preserves sound fidelity
Market Challenges Analysis:
Compliance Gaps and Low Enforcement in Informal Work Sectors
Despite clear safety regulations, informal sectors and small enterprises often fail to implement proper auditory protection practices. Lack of enforcement mechanisms leads to poor compliance, especially in developing economies. The Hearing Protection Devices Market struggles to penetrate these segments due to limited awareness and budget constraints. Informal construction sites, small factories, and agriculture often overlook hearing safety. Workers may consider protection devices unnecessary or uncomfortable. Employers deprioritize investment in hearing protection due to cost or absence of perceived short-term benefits. Education and outreach programs are insufficient to influence lasting behavioral change. This limits overall adoption despite growth in regulated sectors.
Product Discomfort and Lack of Compatibility with Communication Tools
User resistance due to comfort issues and communication barriers affects device adoption across industries. Many hearing protection devices hinder verbal communication or cause discomfort during extended wear. The Hearing Protection Devices Market addresses this with design innovation, but perception lags behind product development. Workers in dynamic environments often remove devices to communicate, reducing protection effectiveness. Incompatibility with helmets or safety glasses also limits practical use. Some users report pressure buildup, ear canal pain, or heat accumulation with earmuffs. These challenges necessitate advanced ergonomic designs and multifunctional solutions. Until addressed fully, user adherence remains inconsistent across job roles and sectors.
Market Opportunities:
Expansion of Industrial Automation and Smart PPE Programs
Emerging industrial automation initiatives are driving investments in connected and intelligent PPE solutions. The Hearing Protection Devices Market aligns with this trend by offering smart, sensor-enabled products that integrate with broader workplace safety platforms. Employers in manufacturing and logistics seek automation-friendly hearing protection gear that communicates real-time data. Vendors can tap into this opportunity by offering solutions with diagnostics, alerts, and cloud dashboards. Industrial IoT growth fuels the adoption of such technologies in occupational safety programs.
Growth in Healthcare, Education, and Consumer Segments
New opportunities are opening in healthcare facilities, schools, and consumer wellness sectors. The Hearing Protection Devices Market can leverage rising awareness of noise sensitivity and sensory wellness in non-industrial environments. Pediatric clinics, elderly care centers, and academic institutions are adopting noise-reducing solutions. The market also benefits from increased online sales and consumer self-education. Suppliers can expand into B2C channels by offering lifestyle-oriented, user-friendly hearing protection gear.
Market Segmentation Analysis:
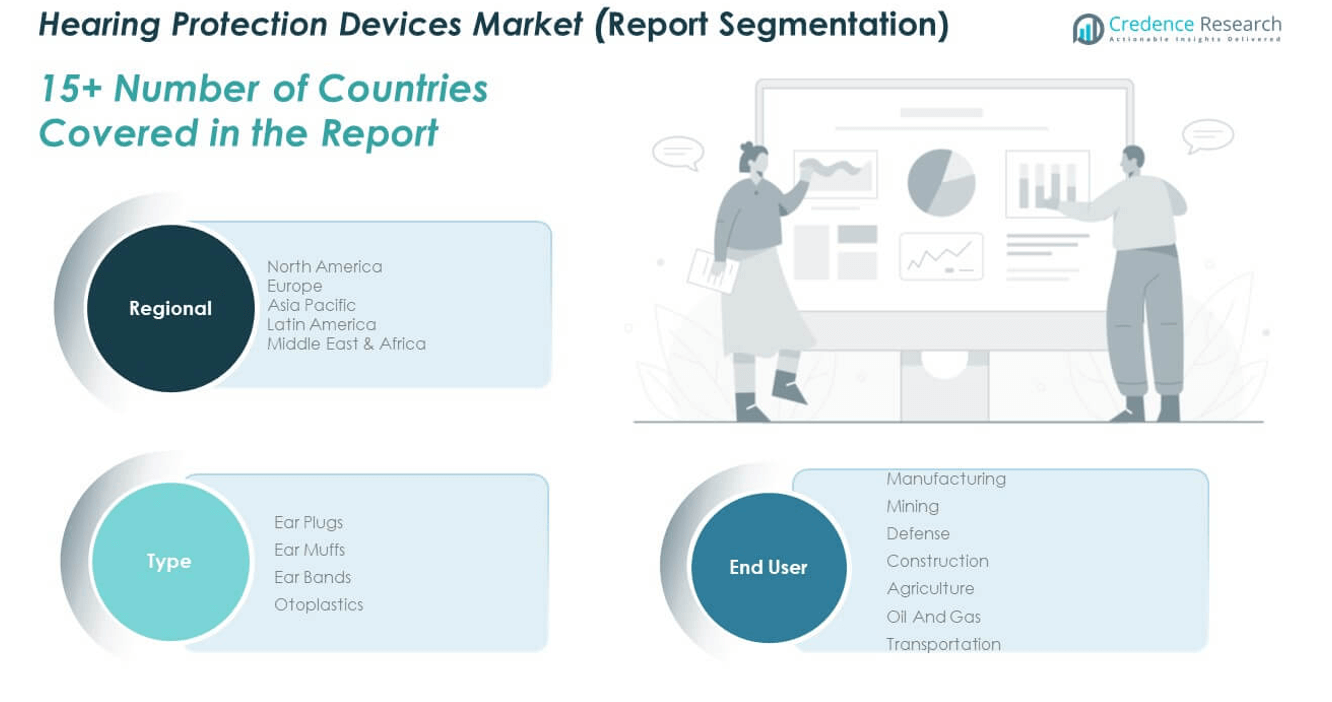
By type, ear plugs lead the Hearing Protection Devices Market due to their affordability, compact design, and effective attenuation in both industrial and recreational settings. Ear muffs follow closely, favored in high-noise environments like aviation and construction for their full-ear coverage and ease of use. Ear bands, offering quick removal and reinsertion, find steady adoption in intermittent noise environments. Otoplastics, though niche, cater to personalized protection needs and are gaining popularity in healthcare, defense, and custom industrial applications where fit and comfort are critical.
- For example, the Honeywell Howard Leight Impact Sport earmuffs are favored in shooting sports, aviation, and construction. They provide an NRR of 22 dB (as tested per ANSI S3.19-1974 standard) and feature electronic sound amplification of safe ambient sounds below 82 dB, with automatic shutoff for noise above that level. Honeywell confirms wide global adoption in certified occupational settings.
By end user, the manufacturing sector dominates the Hearing Protection Devices Market, driven by continuous machinery operation and regulatory mandates. Mining represents a significant share due to the extreme noise levels and worker exposure duration. Defense shows strong growth, with modern battlefield demands encouraging use of advanced tactical hearing protection. Construction follows closely, propelled by expanding infrastructure projects and strict safety norms. Oil and gas facilities implement hearing protection as part of broader HSE compliance strategies. Agriculture and transportation, while relatively smaller segments, exhibit increasing demand due to mechanization and awareness of occupational hearing risks. Each end-use vertical seeks products tailored to specific operational conditions and user preferences.
- 3M™ E-A-R™ Classic Earplugs and Peltor™ earmuffs are widely used in industrial environments across the U.S. to support compliance with OSHA’s 85 dBA 8-hour permissible exposure limit. These hearing protection devices are known for their reliable attenuation and are frequently selected in manufacturing settings to support employee safety under regulated hearing conservation programs.
Segmentation:
By Type
- Ear Plugs
- Ear Muffs
- Ear Bands
- Otoplastics
By End User
- Manufacturing
- Mining
- Defense
- Construction
- Agriculture
- Oil and Gas
- Transportation
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Hearing Protection Devices Market size was valued at USD 511.32 million in 2018 to USD 875.63 million in 2024 and is anticipated to reach USD 1,873.80 million by 2032, at a CAGR of 10.1% during the forecast period. North America accounted for a market share of 35.99% in 2024. It leads the global market due to stringent occupational safety regulations, particularly in the United States and Canada. Regulatory frameworks such as OSHA mandate the provision of hearing protection in high-noise industries, reinforcing product adoption. The region benefits from a well-established manufacturing base and high investment in advanced PPE technologies. Military modernization programs also fuel demand for tactical hearing protection. Industrial automation and smart PPE integration drive innovation in product design. High awareness levels among workers contribute to consistent usage across sectors. Major players maintain a strong presence in the region, ensuring continuous product availability and development.
Europe
The Europe Hearing Protection Devices Market size was valued at USD 400.11 million in 2018 to USD 729.80 million in 2024 and is anticipated to reach USD 1,695.52 million by 2032, at a CAGR of 11.2% during the forecast period. Europe held a 29.99% market share in 2024. It shows strong growth supported by robust safety regulations and enforcement across industries. Countries such as Germany, France, and the UK emphasize auditory safety in industrial and defense sectors. The region encourages sustainable and reusable PPE solutions, aligning with environmental goals. Rising adoption of smart factories and connected devices enhances demand for tech-integrated protection. Labor unions and worker safety councils advocate for mandatory hearing protection policies. Europe also sees rising use in public services, aviation, and logistics. Market penetration improves with growing e-commerce platforms offering advanced protective gear. Innovation centers in Scandinavia and Western Europe contribute to next-generation product development.
Asia Pacific
The Asia Pacific Hearing Protection Devices Market size was valued at USD 297.93 million in 2018 to USD 533.91 million in 2024 and is anticipated to reach USD 1,213.69 million by 2032, at a CAGR of 10.9% during the forecast period. Asia Pacific accounted for a market share of 21.96% in 2024. It is emerging rapidly due to expanding manufacturing hubs and infrastructure development. Countries like China, India, Japan, and South Korea are investing in worker safety as part of industrial modernization. Government-led awareness campaigns and labor reforms support the adoption of hearing protection. High levels of construction and mining activity create strong demand across job sites. Multinational corporations operating regionally enforce global safety standards. Growth in aviation and automotive sectors further strengthens demand for hearing protection. Local vendors are entering the market with cost-effective options. Urbanization and industrial automation offer long-term market prospects.
Latin America
The Latin America Hearing Protection Devices Market size was valued at USD 94.26 million in 2018 to USD 157.75 million in 2024 and is anticipated to reach USD 326.58 million by 2032, at a CAGR of 9.6% during the forecast period. The region held a 6.49% market share in 2024. Latin America presents steady growth driven by increasing focus on workplace safety in countries such as Brazil, Mexico, and Argentina. Mining, oil & gas, and construction sectors are key drivers of hearing protection demand. Industrial growth and new infrastructure projects expose workers to high decibel environments. Companies are gradually aligning with international safety standards to attract foreign investments. Market awareness is growing, though enforcement remains inconsistent. Import reliance for high-end devices is common, but domestic manufacturing is expanding. Distribution networks are evolving with the rise of e-commerce and B2B channels. Public and private sectors are gradually investing in employee safety programs.
Middle East
The Middle East Hearing Protection Devices Market size was valued at USD 51.02 million in 2018 to USD 82.24 million in 2024 and is anticipated to reach USD 160.61 million by 2032, at a CAGR of 8.8% during the forecast period. It held a market share of 3.38% in 2024. The region's growth is supported by significant oil and gas operations and large-scale infrastructure developments. Countries like Saudi Arabia and the UAE are enhancing industrial safety protocols. Mega construction projects, including urban development and transportation infrastructure, contribute to the rising use of PPE. The Hearing Protection Devices Market in the Middle East remains heavily import-driven but is witnessing localized distribution growth. Workforce protection in harsh environments is a major concern. Awareness of hearing damage risks is increasing among employers and regulatory bodies. Adoption of advanced and comfortable hearing protection is gradually improving. Demand is expected to rise with the diversification of the industrial base.
Africa
The Africa Hearing Protection Devices Market size was valued at USD 35.59 million in 2018 to USD 51.82 million in 2024 and is anticipated to reach USD 83.52 million by 2032, at a CAGR of 6.2% during the forecast period. Africa accounted for a 2.13% market share in 2024. It remains a nascent but developing market, with growing awareness of occupational safety in sectors like mining and construction. South Africa leads regional adoption, supported by labor unions and public health campaigns. Many countries are beginning to implement industrial safety standards. Affordability remains a challenge, with limited access to advanced hearing protection products. International donors and NGOs play a role in promoting workplace safety. Imports dominate the market, although local production is slowly emerging. Training and compliance enforcement are needed to drive adoption. Long-term market growth depends on infrastructure development and improved regulatory support.
Key Player Analysis:
- 3M
- Cotral Lab Inc
- Custom Protect Ear Inc
- David Clark Company
- EAR Inc
- Etymotic Research, Inc
- Gentex Corporation
- Insta-Mold Products Inc
- Precision Laboratories, Inc.
- Sensear Pty Ltd.
- Elvex Corporation
- Honeywell International Inc
- Moldex-Metric, Inc.
- Tasco Corporation
Competitive Analysis:
The Hearing Protection Devices Market features several global and regional players competing on product performance, innovation, and distribution reach. Key manufacturers offer broad portfolios that include electronic earplugs, earmuffs, and smart-connected solutions. It emphasizes R&D investments to integrate sensors and improve wearer comfort. Larger firms leverage scale to drive down unit costs and expand into emerging markets. It faces competition from smaller niche brands focusing on ergonomic customization and industry-specific needs. The market rewards firms that maintain strong relationships with industrial, military, and consumer buyers. Brand reputation around certification and durability influences buyer preference. It demands continuous product upgrades and service support to retain competitive advantage.
Recent Developments:
- In May 2025, David Clark Company launched the DC Jet-X Headset, an ultra-lightweight, on-ear headset tailored for airline and corporate pilots. The new series emphasizes lightweight comfort without sacrificing protection, reflecting the brand’s ongoing commitment to innovation in aviation hearing safety.
- In Jan 2025, Gentex Corporation revealed at CES 2025 a range of technological innovations, including their expanding expertise in electrochromic technology for wearables and safety gear. While they showcased prototypes like EC sunglasses, there was no specific hearing protection product launch, but Gentex announced a partnership with the U.S. Navy for next-generation helmet programs due for operational fielding in late 2025.
- In October 2024, 3M launched the WorkTunes Connect + Solar Hearing Protector, which is the first solar-charging wireless Bluetooth hearing protector available to consumers. This innovative headset uses Powerfoyle™ flexible solar cell technology to allow continuous charging from both indoor and outdoor light, and offers upgraded noise reduction, improved sound, and all-day comfort for professionals and hobbyists.
Market Concentration & Characteristics:
The Hearing Protection Devices Market remains moderately consolidated, with leading firms controlling a significant share due to strong R&D capabilities and global distribution networks. It exhibits a mix of vertically integrated manufacturers and specialized OEM suppliers. Large companies invest heavily in product innovation and certification, placing pressure on smaller competitors. The market supports partnerships between PPE providers and industrial safety service firms. It values certification compliance, product quality, and aftermarket support. Buyers often prefer suppliers that offer full-service solutions, including training and fit testing. This dynamic elevates barriers to entry and reinforces dominance by established firms.
Report Coverage:
The research report offers an in-depth analysis based on Type and End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Demand for smart hearing protection with real-time monitoring features is expected to expand across industrial sectors.
- Growth in global construction and infrastructure projects will drive sustained adoption of hearing protection equipment.
- Military and defense modernization will fuel innovation in tactical hearing protection technologies.
- Increasing integration of hearing protection in workplace safety training programs will support market penetration.
- Rising consumer use in recreational activities such as shooting, motorsports, and live events will broaden market scope.
- E-commerce channels will play a larger role in product accessibility and sales, especially for individual buyers.
- Emerging economies will experience greater adoption driven by industrialization and regulatory enforcement.
- Custom-fit and ergonomic product development will enhance user comfort and boost long-term usage.
- Sustainability initiatives will influence the design and material choices of reusable hearing protection devices.
- Collaborations between PPE manufacturers and industrial automation firms will strengthen smart PPE ecosystems.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Occupational Safety Regulations
Governments and regulatory bodies such as OSHA and NIOSH are enforcing stricter workplace safety standards, mandating the use of hearing protection in high-noise environments. This compels industries to integrate certified hearing protection devices into standard PPE kits, especially in sectors like manufacturing, construction, and mining.
Rising Military and Defense Expenditure
Global defense organizations are prioritizing soldier safety, driving demand for advanced tactical hearing protection devices that offer both noise attenuation and integrated communication systems. Increased military budgets and modernization programs are fueling innovation and adoption of smart hearing protection solutions.
Growing Awareness of Occupational Hearing Loss
Workers and employers are increasingly aware of the long-term risks of noise-induced hearing loss, leading to greater adoption of hearing protection devices. Training programs, labor union advocacy, and employee welfare policies are reinforcing the importance of auditory safety in industrial settings.
Expansion in Construction, Aviation, and Oil & Gas Sectors
Rapid growth in construction, aviation, and oil & gas industries exposes more workers to hazardous noise levels, driving demand for effective and comfortable hearing protection solutions tailored to these environments.
Technological Advancements and Smart Features
Innovations such as smart hearing protection devices with real-time noise monitoring, Bluetooth connectivity, and ergonomic customization are making products more appealing and improving compliance, thus expanding the market across both industrial and consumer segments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for HEARING PROTECTION DEVICES MARKET, and what is its projected size in 2032?
Which HEARING PROTECTION DEVICES MARKET market segment held the largest share in 2024?
Who are the leading companies in the HEARING PROTECTION DEVICES MARKET?
Which region commanded the largest share of the HEARING PROTECTION DEVICES MARKET in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Ear Plugs
- 1.2.2 Ear Muffs
- 1.2.3 Ear Bands
- 1.2.4 Otoplastics
- 1.3 By End User
- 1.3.1 Manufacturing
- 1.3.2 Mining
- 1.3.3 Defense
- 1.3.4 Construction
- 1.3.5 Agriculture
- 1.3.6 Oil and Gas
- 1.3.7 Transportation
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,431.1 million → 2032: USD 5,353.7 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hearing Protection Devices Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hearing Protection Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hearing Protection Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hearing Protection Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hearing Protection Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hearing Protection Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hearing Protection Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hearing Protection Devices Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,431.1 million → 2032: USD 5,353.7 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hearing Protection Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Ear Plugs
- 12.3.7.2 Ear Muffs
- 12.3.7.3 Ear Bands
- 12.3.7.4 Otoplastics
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Manufacturing
- 12.4.7.2 Mining
- 12.4.7.3 Defense
- 12.4.7.4 Construction
- 12.4.7.5 Agriculture
- 12.4.7.6 Oil and Gas
- 12.4.7.7 Transportation
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hearing Protection Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Hearing Protection Devices Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Hearing Protection Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Hearing Protection Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 3M
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Honeywell International Inc
- 18.4 Gentex Corporation
- 18.5 David Clark Company
- 18.6 Cotral Lab Inc
- 18.7 Moldex-Metric, Inc.
- 18.8 Custom Protect Ear Inc
- 18.9 Etymotic Research, Inc
- 18.10 Sensear Pty Ltd.
- 18.11 Elvex Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

