
Neonatal Hearing Screening Devices Market Overview:
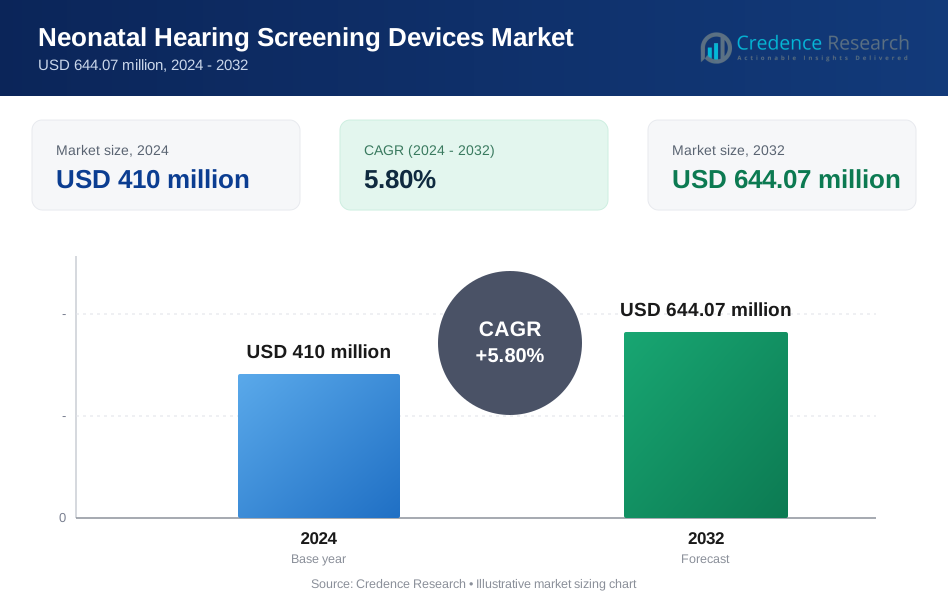
The Neonatal Hearing Screening Devices Market size was valued at USD 410 million in 2024 and is anticipated to reach USD 644.07 million by 2032, at a CAGR of 5.8 % during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Neonatal Hearing Screening Devices Market Size 2024 | USD 410 million |
| Neonatal Hearing Screening Devices Market, CAGR | 5.8 % |
| Neonatal Hearing Screening Devices Market Size 2032 | USD 644.07 million |
Neonatal Hearing Screening Devices Market Insights:
- North America holds the largest share at 38.5%, driven by mandatory newborn screening laws, high healthcare expenditure, and strong reimbursement systems, while Europe accounts for 29.4% due to nationally coordinated screening programs, and Asia-Pacific represents 21.8% supported by expanding hospital infrastructure.
- Asia-Pacific is the fastest-growing region with a 21.8% share, fueled by high birth rates, rising public health investments, increasing awareness of early hearing loss detection, and rapid expansion of private maternity care networks.
- By product type, screening devices dominate with a 62.6% share due to routine equipment replacement and widespread deployment in hospitals, while accessories and consumables collectively account for 37.4% driven by recurring usage volumes.
- By modality, otoacoustic emissions systems lead with a 58.9% share because of cost efficiency and fast testing, while automated auditory brainstem response systems hold 41.1%, supported by adoption in neonatal intensive care and high-risk screening.

Neonatal Hearing Screening Devices Market Drivers:
Government-mandated newborn screening policies and public health compliance requirements
The Neonatal Hearing Screening Devices Market benefits from national mandates that require universal screening before hospital discharge. Health authorities prioritize early detection to reduce lifelong communication impairment and educational burden. Compliance targets push hospitals to adopt standardized screening protocols at scale. It supports predictable procurement cycles across public maternity centers. Policy enforcement sustains long-term demand stability.
- For Instance, Natus Medical’s screening technology, including the Echo-Screen and ALGO series, utilizes a proprietary binomial statistical detection algorithm that requires a 99.9% statistical confidence level to issue a 'PASS' result.
Clinical emphasis on early diagnosis to improve developmental and language outcomes
The Neonatal Hearing Screening Devices Market gains traction from strong clinical evidence that early identification improves speech and cognitive development. Pediatric and audiology associations promote screening within the first days of life. Care pathways now integrate screening with referral and intervention workflows. It strengthens the clinical value proposition for hospitals and birthing centers.
- For instance, Natus Medical's ALGO screener detected hearing loss in 99.9% of cases during newborn screening, enabling timely interventions that boosted language scores by 25 percentiles in treated infants.
Technology advancements that improve accuracy, speed, and ease of use in neonatal care
The Neonatal Hearing Screening Devices Market advances through innovations that deliver objective, rapid, and operator-independent testing. Automated systems reduce variability and shorten test duration in busy neonatal units. Compact and portable designs fit space-constrained maternity wards. It lowers training burden and supports consistent screening quality.
Expansion of maternal and neonatal healthcare infrastructure in emerging economies
The Neonatal Hearing Screening Devices Market expands with investments in hospital capacity and newborn care programs across developing regions. Governments allocate funding to reduce infant morbidity and disability. Private healthcare networks scale maternity services with standardized screening offerings. It accelerates device adoption beyond tertiary hospitals into secondary care settings.
Neonatal Hearing Screening Devices Market Trends:
Rising adoption of automated and objective screening technologies across maternity and neonatal units
The Neonatal Hearing Screening Devices Market reflects a strong shift toward automated screening systems that deliver consistent and operator-independent outcomes. Healthcare providers favor objective technologies that minimize subjectivity and reduce repeat testing. Device designs now emphasize rapid test cycles that align with early discharge timelines in maternity hospitals. Manufacturers integrate simplified user interfaces to support use by nursing staff. It improves workflow efficiency in high-volume birth centers. Integration with electronic health records gains attention to support traceability and follow-up. Technology standardization across hospital networks strengthens uniform screening practices.
- For instance, Interacoustics' automated ABR systems complete screenings in under 30 seconds per ear, enabling efficient use in busy neonatal units with minimal training.
Increasing focus on data connectivity, portability, and decentralized screening models
The Neonatal Hearing Screening Devices Market shows growing demand for portable devices that support bedside and outreach screening programs. Compact systems enable use in neonatal intensive care units and community health settings. Data storage and wireless transfer features support centralized monitoring and quality audits. Providers value systems that facilitate referral tracking and longitudinal outcome assessment. It enhances continuity of care between screening and early intervention services. Manufacturers respond with modular platforms that scale across care levels. Decentralized screening expands access in regions with limited specialist availability.
- For instance, Vivosonic's Integrity V500 offers VivoLink wireless recording up to 30 feet (10 meters) for untethered ABR data transfer in NICUs.
Neonatal Hearing Screening Devices Market Challenges Analysis:
High upfront device costs and budget constraints across public healthcare systems
The Neonatal Hearing Screening Devices Market faces challenges due to the high capital cost of screening equipment and maintenance requirements. Public hospitals often operate under fixed budgets that limit technology upgrades. Procurement cycles remain lengthy in government-funded facilities. It delays replacement of aging systems and slows adoption in secondary care centers. Cost sensitivity influences purchasing decisions in emerging economies. Limited access to financing options further restricts penetration beyond urban hospitals.
Operational gaps related to workforce training, follow-up compliance, and program consistency
The Neonatal Hearing Screening Devices Market encounters obstacles tied to inconsistent screening execution and post-test follow-up. Shortages of trained staff affect testing quality in high-birth-volume settings. Referral tracking remains weak in fragmented healthcare systems. It reduces early intervention rates despite screening availability. Variability in national guidelines creates uneven implementation across regions. Data management limitations also constrain long-term outcome monitoring.
Neonatal Hearing Screening Devices Market Opportunities:
Expansion of universal newborn screening coverage across underserved and emerging regions
The Neonatal Hearing Screening Devices Market presents strong opportunity through expansion of screening programs in underserved geographies. Many countries continue to scale national maternal and child health initiatives. Public health agencies prioritize early disability prevention within newborn care frameworks. It creates sustained demand for cost-efficient and scalable screening solutions. Partnerships between governments and private providers support program rollout. Local manufacturing and procurement reforms improve market accessibility. Rural and semi-urban deployment remains a key growth avenue.
Product innovation focused on portability, affordability, and integrated care pathways
The Neonatal Hearing Screening Devices Market benefits from opportunities tied to innovation in compact and affordable device platforms. Manufacturers develop solutions suited for decentralized and bedside screening. Integrated software supports referral management and outcome tracking. It enhances clinical value beyond initial screening. Subscription-based service models attract resource-constrained hospitals. Digital integration aligns devices with broader neonatal care ecosystems.
Neonatal Hearing Screening Devices Market Segmentation Analysis:
By Product Type
The Neonatal Hearing Screening Devices Market by product type includes screening devices, accessories, and consumables. Screening devices account for the dominant share due to routine replacement cycles and technology upgrades in maternity and neonatal units. Accessories and consumables support recurring revenue through regular usage in high-volume screening programs. It benefits from standardized testing protocols that require single-use components. Product differentiation focuses on durability, accuracy, and ease of maintenance.
- For Instance, Natus Medical’s Echo-Screen III (the latest generation in the series) features an all-in-one handheld design for automated ABR, TEOAE, and DPOAE testing. While TEOAE screenings can be completed in an average of 20 seconds and DPOAE in approximately 30 seconds, the AABR (Automated Auditory Brainstem Response) technology typically requires an average of 2 minutes per ear for a full screening.
By Modality
The Neonatal Hearing Screening Devices Market by modality covers otoacoustic emissions and automated auditory brainstem response systems. Otoacoustic emissions devices achieve broad adoption due to fast testing and cost efficiency. Automated auditory brainstem response systems gain traction in neonatal intensive care units and high-risk infant screening. It reflects clinical preference for objective and reliable modalities. Hospitals often deploy both modalities to support tiered screening workflows.
- For Instance, Natus Medical's newborn hearing screening systems, such as the ALGO devices, have been used in large-scale clinical deployments and consistently achieve a discharge referral rate below 4%.
By End User
The Neonatal Hearing Screening Devices Market by end user includes hospitals, maternity centers, and diagnostic clinics. Hospitals represent the largest share due to universal newborn screening mandates and integrated neonatal services. Maternity centers increase adoption to support early discharge protocols. Diagnostic clinics support referral testing and follow-up care. It strengthens demand across both public and private healthcare settings.
Segmentations:
By Product Type
- Screening Devices
- Accessories
- Consumables
By Modality
- Otoacoustic Emissions
- Automated Auditory Brainstem Response
By End User
- Hospitals
- Maternity Centers
- Diagnostic Clinics
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Strong institutional adoption and policy-driven coverage in North America
The Neonatal Hearing Screening Devices Market shows mature performance in North America due to well-established universal newborn screening programs. Federal and state mandates support consistent screening before hospital discharge. Hospitals maintain high compliance through standardized clinical pathways. It benefits from strong reimbursement structures and advanced neonatal infrastructure. Device replacement demand remains steady across public and private facilities. Manufacturers focus on workflow efficiency and data integration to meet provider expectations. High awareness among clinicians and parents sustains long-term adoption.
Structured national programs and regulatory alignment across Europe
The Neonatal Hearing Screening Devices Market maintains stable growth across Europe supported by nationally coordinated screening initiatives. Many countries integrate hearing tests into routine neonatal assessments. Public healthcare systems drive centralized procurement and protocol standardization. It supports broad access across urban and regional hospitals. Regulatory emphasis on quality assurance strengthens demand for reliable and validated devices. Technology upgrades focus on accuracy and interoperability. Consistent follow-up frameworks improve screening effectiveness.
Rapid expansion supported by healthcare investment in Asia-Pacific
The Neonatal Hearing Screening Devices Market records the fastest expansion in Asia-Pacific due to rising birth volumes and healthcare spending. Governments increase focus on early diagnosis and disability prevention. Urban hospitals lead adoption through modern maternity and neonatal units. It gains momentum as private healthcare networks scale standardized screening services. Awareness campaigns improve acceptance among parents and providers. Local manufacturing and cost-sensitive solutions support wider deployment. Regional disparities persist but show steady improvement.
Key Player Analysis:
- Draeger India Private Limited
- Echodia S.A.S
- Grason-Stadler, Inc.
- Guangzhou Melison Medical Instrument Co., Ltd.
- iClear Healthcare
- Intelligent Hearing Systems Corp.
- Interacoustics A/S
- MAICO Diagnostics GmbH
- Natus Medical Incorporated
- Neurosoft
- Otodynamics Ltd
- Path Medical GmbH
Competitive Analysis:
The Neonatal Hearing Screening Devices Market features a moderately consolidated competitive structure with global and regional manufacturers competing on technology reliability, workflow efficiency, and service support. It favors companies that offer validated screening accuracy, durable hardware, and integrated data management capabilities. Leading participants invest in product upgrades that reduce test time and operator dependency. Portfolio breadth across otoacoustic emissions and automated auditory brainstem response systems strengthens competitive positioning. Natus Medical maintains strong visibility through comprehensive neonatal care solutions and hospital relationships. Otometrics and Interacoustics compete through advanced signal processing and clinician-focused interfaces. Maico Diagnostics emphasizes portability and cost-efficient systems for decentralized screening. It rewards vendors that combine regulatory compliance, training support, and responsive after-sales service. Competitive intensity increases in emerging markets where pricing and local partnerships influence procurement decisions.
Recent Developments:
- In April 2024, Draeger India Private Limited unveiled the Vista 300, a new patient monitoring system.
- In October 2025, Drägerwerk AG & Co. KGaA reported preliminary Q3 2025 figures showing a 10.1% increase in net sales.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Modality, End User and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The Neonatal Hearing Screening Devices Market will advance through broader enforcement of universal newborn screening policies across public and private healthcare systems.
- Manufacturers will prioritize automated, objective technologies that deliver consistent accuracy with minimal operator dependency in high-volume maternity settings.
- Portable and compact device formats will gain preference to support bedside testing, neonatal intensive care units, and community outreach programs.
- Integration with digital health records will strengthen screening traceability, referral management, and long-term outcome monitoring.
- Healthcare providers will seek solutions that reduce test duration and align with early discharge protocols in maternity hospitals.
- Emerging economies will witness stronger adoption supported by maternal and child health investments and expanding hospital infrastructure.
- Cost-efficient platforms will attract mid-tier and secondary care facilities seeking standardized screening capability.
- Vendors will emphasize training support and service reliability to improve program consistency and user confidence.
- Public-private partnerships will play a larger role in expanding screening coverage beyond urban healthcare centers.
- Technology validation and regulatory compliance will remain critical factors shaping procurement decisions and vendor differentiation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size of the Neonatal Hearing Screening Devices Market, and what is its projected value by 2032?
At what Compound Annual Growth Rate is the Neonatal Hearing Screening Devices Market expected to grow during the forecast period?
Which segment held the largest share of the Neonatal Hearing Screening Devices Market in 2024?
What are the key factors driving growth in the Neonatal Hearing Screening Devices Market?
Who are the leading companies operating in the Neonatal Hearing Screening Devices Market?
Which region dominated the Neonatal Hearing Screening Devices Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Neonatal Hearing Screening Devices Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Neonatal Hearing Screening Devices Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 410 million → 2032: USD 644.07 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Neonatal Hearing Screening Devices Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Neonatal Hearing Screening Devices Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Neonatal Hearing Screening Devices Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Neonatal Hearing Screening Devices Market Drivers
- 3.3 Neonatal Hearing Screening Devices Market Restraints & Challenges
- 3.4 Neonatal Hearing Screening Devices Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Neonatal Hearing Screening Devices Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Neonatal Hearing Screening Devices Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Neonatal Hearing Screening Devices category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Neonatal Hearing Screening Devices Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Neonatal Hearing Screening Devices Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Neonatal Hearing Screening Devices market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Neonatal Hearing Screening Devices Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Neonatal Hearing Screening Devices Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Neonatal Hearing Screening Devices Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Neonatal Hearing Screening Devices (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Neonatal Hearing Screening Devices Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Neonatal Hearing Screening Devices Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Neonatal Hearing Screening Devices Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Neonatal Hearing Screening Devices Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Neonatal Hearing Screening Devices Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Neonatal Hearing Screening Devices Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Neonatal Hearing Screening Devices Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Neonatal Hearing Screening Devices Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Neonatal Hearing Screening Devices Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
