
Market Overview
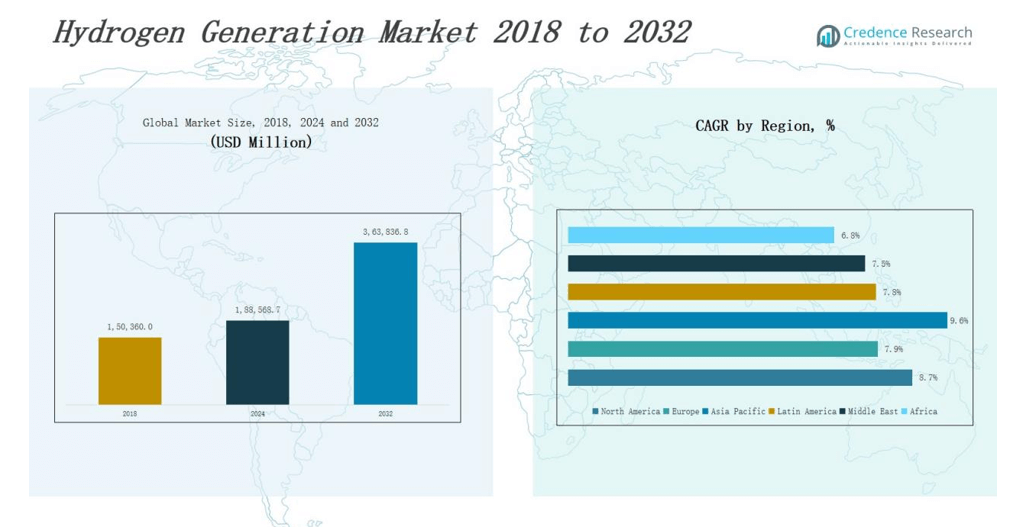
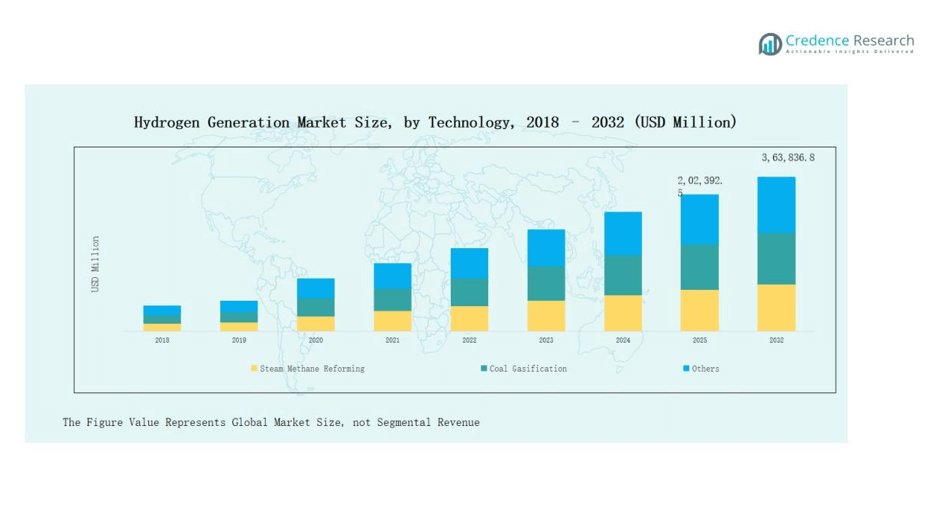
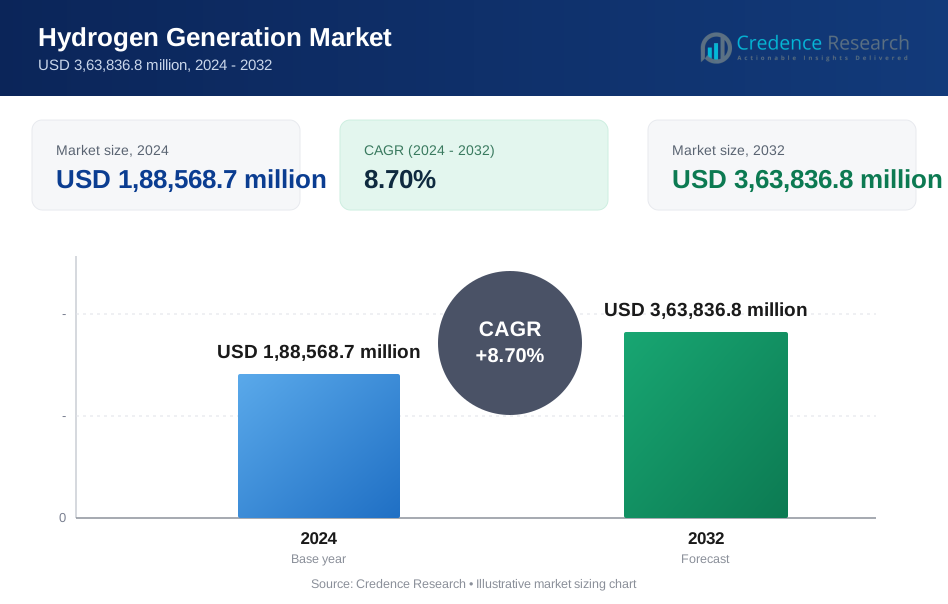
Hydrogen Generation Market size was valued at USD 1,50,360.0 million in 2018 to USD 1,88,568.7 million in 2024 and is anticipated to reach USD 3,63,836.8 million by 2032, at a CAGR of 8.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hydrogen Generation Market Size 2024 | USD 1,88,568.7 million |
| Hydrogen Generation Market, CAGR | 8.7% |
| Hydrogen Generation Market Size 2032 | USD 3,63,836.8 million |
The hydrogen generation market is shaped by leading companies such as Air Liquide, Linde plc, Air Products and Chemicals Inc., Cummins Inc., Plug Power Inc., Nel ASA, Siemens Energy, and Ballard Power Systems. These players focus on scaling production capacity, advancing electrolyzer technology, and forming partnerships with governments and industries to drive adoption across mobility, industrial, and energy sectors. Regionally, Asia Pacific leads the hydrogen generation market, accounting for 41 percent of the global share, supported by strong investments in renewable energy integration, government-backed hydrogen roadmaps in countries like Japan, China, and South Korea, and rapid development of green hydrogen projects.
Market Insights
- The Hydrogen Generation Market grew from USD 1,50,360.0 million in 2018 to USD 1,88,568.7 million in 2024, projected at USD 3,63,836.8 million by 2032.
- Steam methane reforming dominates with 63 percent share, while electrolysis gains traction through rising green hydrogen initiatives and supportive global government policies.
- Ammonia production leads applications with 34 percent share, driven by strong fertilizer demand, while transportation and power generation expand through fuel cell and clean energy adoption.
- Captive hydrogen generation holds 62 percent share, ensuring consistent industrial supply, while merchant systems expand through distribution investments and decentralized power applications worldwide.
- Asia Pacific leads with 30 percent share, supported by China, Japan, and South Korea, while North America follows with 27 percent and Europe accounts for 22 percent.
Market Segment Insights
By Technology:
Steam methane reforming dominates the hydrogen generation market, holding nearly 63 percent share. Its leadership is driven by cost-effectiveness, mature infrastructure, and large-scale adoption across refineries and chemical industries. Coal gasification accounts for a significant portion but faces environmental concerns, while other methods, including water electrolysis, are gaining momentum due to rising focus on green hydrogen initiatives and supportive government policies.
- For instance, Air Products operates the world’s largest SMR facility in Port Arthur, Texas, supplying hydrogen to nearby refineries.
By Application:
Ammonia production leads the application segment with 34 percent share, supported by strong fertilizer industry demand worldwide. Methanol production follows closely, while petroleum refining sustains steady demand for hydrogen to remove impurities and meet fuel quality standards. Transportation and power generation segments are growing at faster rates, driven by fuel cell vehicles, decarbonization goals, and government incentives promoting clean energy adoption.
- For instance, ExxonMobil’s Baton Rouge refinery in Louisiana operates large-scale steam methane reformers dedicated to manufacturing hydrogen used in its hydrodesulfurization units.
By Systems:
Captive hydrogen generation holds the majority share at 62 percent, as industries prefer on-site production for continuous and cost-efficient supply. This approach reduces dependency on external suppliers and enhances operational reliability. Merchant hydrogen systems, accounting for the remaining market share, are expanding due to rising investments in distribution networks and increasing demand from mobility and decentralized power generation applications.
Market Overview
Decarbonization and Clean Energy Transition
The hydrogen generation market grows significantly as countries commit to decarbonization targets and net-zero goals. Governments invest in hydrogen as a clean fuel alternative to reduce reliance on fossil fuels. Industries adopt hydrogen for refining, power generation, and transportation, creating broad market demand. Green hydrogen, produced from renewable sources, emerges as a central focus of energy transition strategies. This push for sustainable energy security drives long-term investments in infrastructure, research, and commercialization, positioning hydrogen as a critical pillar in global clean energy adoption.
- For instance, in the U.S., the Department of Energy supports clean hydrogen projects that focus on using hydrogen as a substitute for carbon-intensive sources in industrial processes like ammonia production and refining, while also advancing hydrogen's role in energy storage and heavy-duty transportation.
Government Incentives and Policy Support
Strong policy frameworks and financial incentives accelerate hydrogen adoption across industries. Many nations provide subsidies, tax credits, and grants to scale hydrogen projects, particularly for green hydrogen production. Large-scale pilot projects and national hydrogen roadmaps create favorable market environments. International partnerships further strengthen supply chains and promote standardization. Such initiatives reduce production costs and encourage both private and public investments. These actions solidify hydrogen’s role in energy diversification strategies while enabling companies to align with regulatory compliance and low-carbon objectives.
- For instance, Japan’s Green Innovation Fund allocated more than ¥2 trillion (about $15 billion) to advance hydrogen and fuel cell technologies, including Mitsubishi Heavy Industries’ large-scale hydrogen gas turbine development for clean power generation.
Industrial and Transportation Demand
Rising industrial requirements and clean mobility initiatives fuel hydrogen generation. Refineries, ammonia plants, and methanol producers continue to demand hydrogen for process optimization. Simultaneously, the adoption of hydrogen fuel cells in buses, trucks, and trains is accelerating. Automotive companies invest in hydrogen-powered vehicles, supported by infrastructure development and government mandates for low-emission transport. Heavy industries and shipping sectors also explore hydrogen as a decarbonization option. This dual demand from industrial applications and transportation creates a strong growth pathway, balancing short-term commercial needs with long-term clean energy expansion.
Key Trends & Opportunities
Rapid Growth of Green Hydrogen
Green hydrogen production represents the fastest-growing trend in the market. Falling renewable energy costs and technological improvements in electrolysis make production more viable. Governments worldwide prioritize green hydrogen in decarbonization plans, integrating it into industrial clusters and energy storage systems. International collaborations support cross-border hydrogen supply chains, positioning it as a global commodity. With strong environmental benefits and alignment with climate targets, green hydrogen opens large-scale opportunities for investors, technology developers, and energy companies.
- For instance, German company HY2GEN operates SUNRHYSE, a 30 MW solar-powered electrolysis plant supplying hydrogen for mobility and maritime sectors.
Expansion of Hydrogen Infrastructure
Opportunities are rising through heavy investments in hydrogen transport, storage, and refueling networks. Countries expand dedicated hydrogen pipelines and hubs to support industrial and mobility applications. Deployment of fueling stations for trucks and passenger vehicles improves adoption feasibility. Infrastructure development reduces supply bottlenecks and enhances reliability. By creating a strong ecosystem, governments and private players prepare the market for future scalability. These initiatives not only boost local consumption but also strengthen export potential for regions with abundant renewable energy.
- For instance, Air Liquide announced in 2023 the development of a 200 km hydrogen pipeline network in Normandy, France, to link industrial users with low-carbon production sites.
Key Challenges
High Production Costs
One of the major barriers for the hydrogen generation market is high production cost, especially for green hydrogen. Electrolysis remains expensive compared to traditional methods like steam methane reforming. Limited economies of scale and the cost of renewable electricity add to challenges. Although technology is improving, affordability remains a constraint in widespread adoption. Without further innovation, subsidies, and cost reductions, hydrogen’s competitiveness against other energy sources will remain limited in the short to medium term.
Infrastructure and Storage Limitations
The lack of widespread hydrogen infrastructure slows market development. Transporting and storing hydrogen safely requires advanced systems, increasing project complexity and costs. Pipelines, liquefaction, and compression facilities are limited, making large-scale distribution difficult. The absence of standardized frameworks across countries further complicates investments. Infrastructure gaps hinder hydrogen’s potential in mobility and power generation sectors, restricting adoption despite rising demand. Addressing these limitations is critical to building a resilient and efficient global hydrogen economy.
Environmental Concerns of Conventional Production
A significant challenge is the reliance on steam methane reforming and coal gasification, which emit large volumes of carbon dioxide. Despite being cost-effective, these methods raise sustainability concerns and conflict with net-zero goals. Unless paired with carbon capture technologies, conventional production undermines the environmental benefits of hydrogen. This creates regulatory and social pressure on companies to transition to greener alternatives. The shift to clean hydrogen requires large-scale investments and innovation, making it a challenging but necessary transformation.
Regional Analysis
North America:
North America accounts for 27 percent share of the hydrogen generation market in 2024, supported by strong industrial applications and rising clean mobility projects. The market grows from USD 41,950.4 million in 2018 to USD 99,701.5 million by 2032, registering a CAGR of 8.7 percent. The U.S. leads regional adoption through large-scale hydrogen hubs, federal funding, and rapid fuel cell vehicle integration. Canada and Mexico also expand their hydrogen portfolios, driven by renewable integration and industrial decarbonization efforts. Infrastructure growth and technological advancements position the region as a key global hub.
Europe:
Europe holds 22 percent share of the hydrogen generation market in 2024, with demand growing from USD 34,733.2 million in 2018 to USD 75,224.2 million by 2032, reflecting a CAGR of 7.9 percent. Germany, France, and the UK lead adoption through government-backed hydrogen strategies, strong renewable energy integration, and industrial decarbonization policies. The European Union supports cross-border hydrogen transport and storage projects, strengthening regional competitiveness. Focus on green hydrogen and carbon neutrality targets enhances long-term opportunities. Europe's strategic policy support and innovation ecosystem drive consistent market expansion.
Asia Pacific:
Asia Pacific dominates with 30 percent share of the hydrogen generation market in 2024, increasing from USD 53,964.2 million in 2018 to USD 1,43,835.9 million by 2032, achieving a CAGR of 9.6 percent. China, Japan, South Korea, and India lead investments in hydrogen infrastructure, renewable-powered electrolysis, and fuel cell vehicle deployment. Governments implement national hydrogen roadmaps, supporting large-scale industrial and transportation projects. Rapid energy demand growth and industrialization fuel adoption across refining and chemical sectors. The region’s leadership is strengthened by technological advancements, cost competitiveness, and strong policy commitments.
Latin America:
Latin America represents 9 percent share of the hydrogen generation market in 2024, expanding from USD 10,194.4 million in 2018 to USD 22,805.3 million by 2032, at a CAGR of 7.8 percent. Brazil and Argentina lead with renewable energy-based hydrogen projects, leveraging abundant wind and solar resources. The region explores green hydrogen exports to Europe and Asia, positioning itself as a potential supplier. Industrial applications in refining and chemicals remain important, while policy-driven renewable integration accelerates growth. Strategic investments in infrastructure and partnerships enhance Latin America’s role in the global hydrogen economy.
Middle East:
The Middle East holds 7 percent share of the hydrogen generation market in 2024, rising from USD 6,465.5 million in 2018 to USD 13,500.3 million by 2032, reflecting a CAGR of 7.5 percent. Countries like Saudi Arabia, UAE, and Qatar invest heavily in green hydrogen projects, supported by large renewable capacity and export ambitions. Hydrogen production aligns with diversification strategies under Vision 2030 initiatives, reducing reliance on oil revenues. Mega-projects for ammonia exports to Europe and Asia enhance regional competitiveness. Government support and international partnerships drive the Middle East’s emerging hydrogen leadership.
Africa:
Africa contributes 5 percent share of the hydrogen generation market in 2024, expanding from USD 3,052.3 million in 2018 to USD 8,769.6 million by 2032, achieving a CAGR of 6.8 percent. South Africa leads adoption through pilot projects and industrial applications, while Egypt develops large-scale renewable hydrogen initiatives. Abundant solar and wind resources offer long-term potential for green hydrogen exports. However, infrastructure and investment gaps remain significant barriers. International collaborations and rising global demand create opportunities for Africa to evolve into a strategic hydrogen supplier in the coming decades.
Market Segmentations:
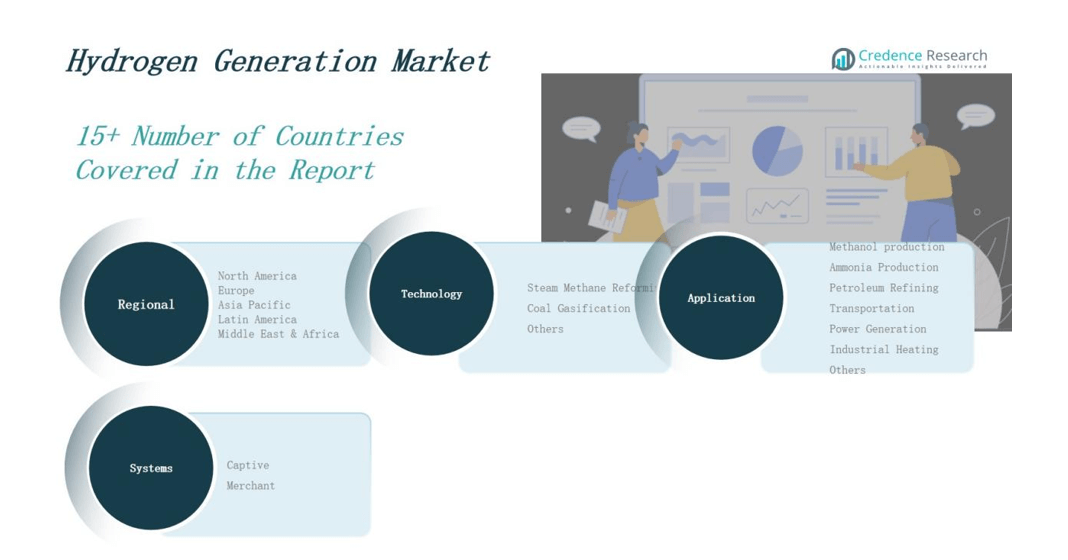
By Technology
- Steam Methane Reforming
- Coal Gasification
- Others
By Application
- Methanol Production
- Ammonia Production
- Petroleum Refining
- Transportation
- Power Generation
- Industrial Heating
- Others
By Systems
- Captive
- Merchant
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the hydrogen generation market is defined by a mix of global industrial gas companies, energy firms, and emerging technology providers. Leading players such as Air Liquide, Linde Plc, Air Products and Chemicals Inc., Cummins Inc., Plug Power Inc., Nel ASA, Siemens Energy, Iwatani Corporation, and Ballard Power Systems hold strong positions through broad portfolios and large-scale projects. These companies focus on expanding green hydrogen capabilities, advancing electrolyzer technologies, and building strategic partnerships with governments and industries to accelerate adoption. Investments in hydrogen hubs, pilot projects, and infrastructure development strengthen their market influence. The competition is further shaped by acquisitions, research collaborations, and joint ventures aimed at scaling production and reducing costs. Regional players, especially in Asia Pacific and Europe, contribute to market growth with localized solutions and renewable integration. As the market evolves, technological innovation and policy-driven initiatives remain key factors shaping competitive intensity and long-term positioning.
Key Players
- Air Liquide International S.A
- Air Products and Chemicals, Inc.
- Hydrogenics Corporation
- INOX Air Products Ltd.
- Iwatani Corporation
- Linde Plc
- Matheson Tri-Gas, Inc.
- Messer
- SOL Group
- Tokyo Gas Chemicals Co., Ltd.
Recent Developments
- l In July 2025, CPS Energy partnered with Modern Hydrogen to pilot a clean energy project converting natural gas into hydrogen and solid carbon in Texas.
- l In July 2025, Sterlite Technologies Ltd. (STL) collaborated with Hygenco to establish Maharashtra’s first green hydrogen and oxygen facility for optical fibre manufacturing.
- l In 2025, Carbon280 launched a pilot plant in Kwinana, Australia, using Hydrilyte technology to enable safer hydrogen storage and transport with suspended metal hydrides.
- l In February 2025, Cummins Inc. partnered with GAIL (India) Limited to enhance green hydrogen production, blending, transportation, and storage using GAIL’s gas infrastructure and Cummins’ zero-emission solutions.
Market Concentration & Characteristics
The Hydrogen Generation Market shows a moderately concentrated structure with dominance by a few global industrial gas companies and energy technology firms. It is shaped by established players such as Air Liquide, Linde Plc, and Air Products and Chemicals Inc., which control significant production capacity and maintain strong project pipelines. Competition centers on cost efficiency, technological advancements, and large-scale green hydrogen initiatives supported by government policies. It relies heavily on collaborations, joint ventures, and infrastructure investments to expand regional presence and meet growing demand. Smaller companies and start-ups focus on niche technologies like electrolysis and renewable integration, adding competitive pressure. The market demonstrates high capital intensity and a strong reliance on innovation to achieve cost reductions and scalability. It is also characterized by the growing role of regional strategies, with Asia Pacific, Europe, and North America competing to secure leadership in hydrogen supply, infrastructure development, and long-term energy transition goals.
Report Coverage
The research report offers an in-depth analysis based on Technology, Application, System and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Green hydrogen demand will rise globally, driven by renewable integration and sustainability-focused energy transition efforts.
- Governments will enhance supportive policies, offering subsidies and incentives to accelerate large-scale hydrogen project deployments.
- Industrial sectors will adopt hydrogen technologies widely to decarbonize processes and reduce overall environmental impacts.
- Heavy-duty transportation will expand hydrogen fuel cell adoption, supporting clean mobility and reducing dependency on diesel.
- Hydrogen storage, pipelines, and refueling infrastructure will rapidly expand to strengthen supply chain and accessibility.
- Energy companies, technology providers, and governments will establish partnerships to accelerate commercialization of hydrogen solutions.
- Export-oriented hydrogen projects will expand in renewable-rich regions, supporting global trade and strategic energy security.
- Continuous technological advancements in electrolysis will reduce costs, enabling scalable and competitive hydrogen production worldwide.
- Carbon capture adoption will increase in conventional hydrogen production to address emission concerns and regulations.
- Regional competition will intensify as nations invest heavily in becoming global hydrogen supply leaders.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Decarbonization and Clean Energy Transition
Global commitments to net-zero emissions and decarbonization targets are driving investments in hydrogen as a clean fuel alternative. Hydrogen is increasingly adopted in refining, power generation, and transportation, positioning it as a key pillar in the energy transition.
Government Incentives and Policy Support
Strong policy frameworks, subsidies, tax credits, and national hydrogen roadmaps are accelerating the deployment of hydrogen projects, especially for green hydrogen. These incentives lower production costs and encourage both public and private sector investments.
Industrial and Transportation Demand
Growing requirements from refineries, ammonia plants, and methanol producers, combined with the adoption of hydrogen fuel cells in heavy-duty vehicles, are expanding the market. Clean mobility initiatives and industrial decarbonization are creating robust, dual demand.
Rapid Growth of Green Hydrogen
Falling renewable energy costs and advancements in electrolysis technology are making green hydrogen production more viable. Governments and industries are prioritizing green hydrogen for its environmental benefits and alignment with climate targets.
Expansion of Hydrogen Infrastructure
Significant investments in hydrogen transport, storage, and refueling networks are reducing supply bottlenecks and enabling broader adoption across industrial and mobility sectors. Infrastructure development is crucial for scaling the market and supporting export opportunities.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Hydrogen Generation Market?
What are the key drivers of the hydrogen generation market?
How is hydrogen used across different industries?
Which regions are leading the hydrogen generation market?
What is the role of green hydrogen in market growth?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By System
- 1.2.1 Captive
- 1.2.2 Merchant
- 1.3 By Technology
- 1.3.1 Steam Methane Reforming
- 1.3.2 Coal Gasification
- 1.3.3 Electrolysis
- 1.3.4 Others
- 1.4 By Application
- 1.4.1 Ammonia Production
- 1.4.2 Methanol Production
- 1.4.3 Petroleum Refining
- 1.4.4 Transportation
- 1.4.5 Power Generation
- 1.4.6 Industrial Heating
- 1.4.7 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,88,568.7 million → 2032: USD 3,63,836.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hydrogen Generation Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hydrogen Generation Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hydrogen Generation Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hydrogen Generation Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hydrogen Generation Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hydrogen Generation Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hydrogen Generation Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hydrogen Generation Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,88,568.7 million → 2032: USD 3,63,836.8 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hydrogen Generation Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By System - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Captive
- 12.3.7.2 Merchant
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Steam Methane Reforming
- 12.4.7.2 Coal Gasification
- 12.4.7.3 Electrolysis
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Ammonia Production
- 12.5.7.2 Methanol Production
- 12.5.7.3 Petroleum Refining
- 12.5.7.4 Transportation
- 12.5.7.5 Power Generation
- 12.5.7.6 Industrial Heating
- 12.5.7.7 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hydrogen Generation End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Hydrogen Generation Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Hydrogen Generation Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Hydrogen Generation Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Air Liquide
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Linde Plc
- 18.4 Air Products and Chemicals Inc.
- 18.5 Cummins Inc.
- 18.6 Plug Power Inc.
- 18.7 Nel ASA
- 18.8 Siemens Energy
- 18.9 Iwatani Corporation
- 18.10 Ballard Power Systems
- 18.11 Hydrogenics Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

