
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Incinerators Market Size 2024 | USD 18,111.06 million |
| Incinerators Market, CAGR | 2.97% |
| Incinerators Market Size 2032 | USD 22,798.36 million |
Market Overview
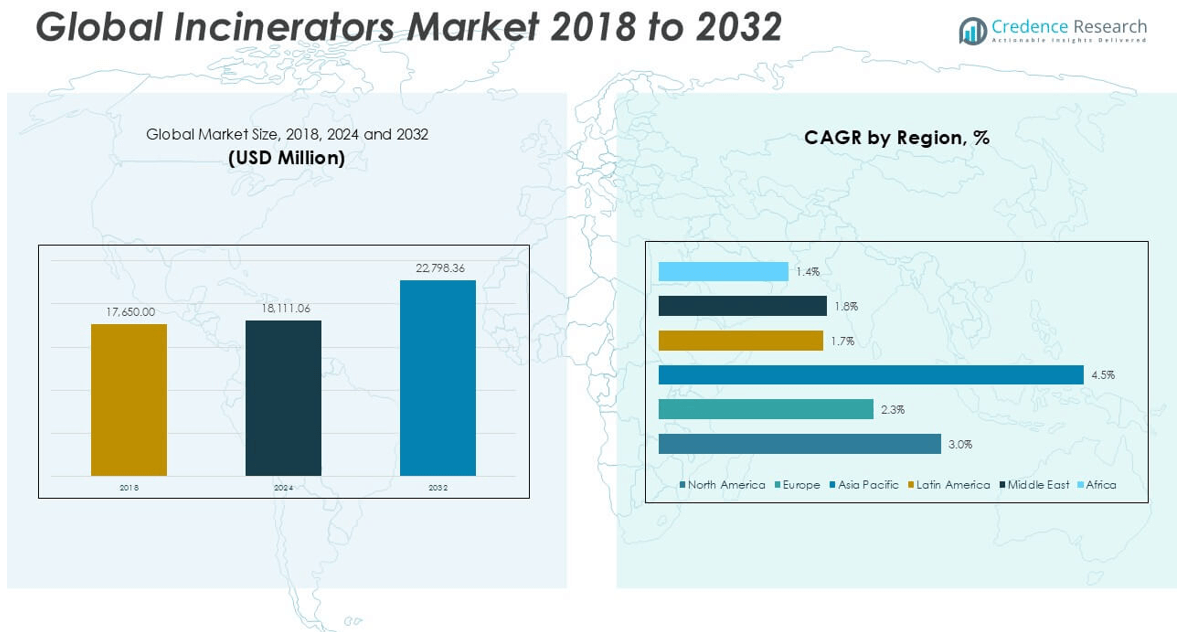
The Incinerators market size was valued at USD 17,650.00 million in 2018, increased to USD 18,111.06 million in 2024, and is anticipated to reach USD 22,798.36 million by 2032, at a CAGR of 2.97% during the forecast period.
The incinerators market is driven by key players such as Babcock & Wilcox, Mitsubishi Heavy Industries, Keppel Seghers, Atlas Incinerators, Dutch Incinerators, and Haat Incinerator India. These companies lead the market through advanced technologies, strategic partnerships, and strong global networks, focusing on energy-efficient and environmentally compliant solutions. North America dominates the global incinerators market, holding the largest share of 38.05% in 2024, supported by stringent waste management regulations and significant investments in waste-to-energy infrastructure. Europe follows, driven by strict environmental policies and the widespread adoption of advanced incineration systems, while Asia Pacific emerges as the fastest-growing region, propelled by rapid urbanization, increasing waste volumes, and expanding government initiatives to modernize waste management practices.
Market Insights
- The global incinerators market was valued at USD 18,111.06 million in 2024 and is projected to reach USD 22,798.36 million by 2032, growing at a CAGR of 2.97% during the forecast period.
- Increasing municipal solid waste generation and the rising need for effective hazardous waste management are key drivers accelerating the demand for incinerators globally.
- The market is witnessing a growing trend toward waste-to-energy technologies, with rotary kiln incinerators dominating the product segment due to their versatility and high efficiency.
- Key players such as Babcock & Wilcox, Mitsubishi Heavy Industries, and Keppel Seghers are focusing on strategic partnerships, product innovation, and expanding their global footprint to strengthen their competitive position.
- High capital investment, operational costs, and public concerns over emissions are major restraints, while North America holds the largest regional share at 38.05%, followed by Europe at 25.75% and Asia Pacific at 22.27%.
Market Segmentation Analysis:
By Product:
The incinerators market, segmented by product, is led by the rotary kiln sub-segment, which holds the largest market share due to its versatility in handling a wide range of waste types, including hazardous, medical, and municipal waste. Rotary kilns are favored for their high-temperature operations, continuous processing capability, and adaptability to various waste streams. Additionally, the growing need for efficient hazardous waste management and stricter environmental regulations worldwide are driving the demand for rotary kiln incinerators. Their ability to achieve complete combustion with minimal emissions further strengthens their dominance in the global market.
- For instance, Babcock & Wilcox’s rotary kiln system at the Dülmen Hazardous Waste Incineration Plant in Germany processes up to 55,000 tonnes of hazardous waste annually, achieving combustion chamber temperatures exceeding 1,100°C with over 99.99% destruction efficiency.
By End Use:
Among end-use segments, the municipal sector dominates the incinerators market, accounting for the largest market share. This dominance is driven by the rapid urbanization and growing population that contribute to increasing municipal solid waste volumes globally. Municipalities are increasingly adopting incineration as an effective solution to manage waste and reduce landfill dependence, particularly in urban areas where space constraints are critical. The rising focus on energy recovery from waste and stringent government policies promoting sustainable waste management practices further support the significant adoption of incinerators in the municipal sector.
- For instance, the Keppel Seghers Tuas Waste-to-Energy Plant in Singapore processes approximately 800 tonnes of municipal waste per day, generating up to 22 MW of electricity, which is sufficient to power around 45,000 households.
Market Overview
Rising Municipal Solid Waste Generation
The increasing generation of municipal solid waste (MSW) due to rapid urbanization and population growth is a major driver for the incinerators market. Many urban areas face space constraints for landfilling, prompting municipalities to adopt incineration as an efficient waste management solution. Incinerators offer a practical method to significantly reduce waste volume while enabling energy recovery through waste-to-energy (WTE) systems. Governments worldwide are investing in waste incineration infrastructure to mitigate landfill pressure and improve sustainable waste management, further fueling market expansion.
- For instance, the Spittelau Waste Incineration Plant in Vienna, operated by Wien Energie, processes approximately 250,000 tonnes of waste annually, reducing waste volume by 90% while supplying heating to over 60,000 households.
Stringent Environmental Regulations
Stringent environmental policies aimed at reducing landfill use and minimizing greenhouse gas emissions are driving the adoption of advanced incineration technologies. Regulatory bodies in developed and developing countries are enforcing stricter guidelines on waste disposal and emissions control, encouraging industries and municipalities to opt for modern, eco-friendly incinerators. These advanced systems are equipped with sophisticated air pollution control mechanisms that comply with international emission standards, promoting their widespread deployment. This regulatory pressure significantly boosts the demand for efficient and sustainable incineration solutions.
- For instance, the Amager Bakke Waste-to-Energy Plant in Copenhagen, operated by ARC, is equipped with state-of-the-art flue gas cleaning systems that reduce nitrogen oxide emissions to as low as 30 mg/Nm³, significantly below the EU emission limit of 200 mg/Nm³.
Growing Industrial Waste and Hazardous Disposal Needs
Industrialization across sectors such as pharmaceuticals, chemicals, and manufacturing is contributing to the rising volume of hazardous and non-recyclable waste. Industries are increasingly relying on incinerators to manage toxic by-products safely and comply with stringent disposal regulations. The demand for specialized incinerators capable of handling industrial waste streams is growing rapidly, particularly in emerging economies. This trend is reinforced by the rising focus on workplace safety, environmental protection, and the proper handling of hazardous materials, which collectively stimulate market growth.
Key Trends & Opportunities
Advancements in Waste-to-Energy Technologies
The integration of waste-to-energy (WTE) technologies in modern incinerators presents a significant growth opportunity. Innovations in energy recovery systems allow incinerators to efficiently convert waste into electricity and heat, offering both environmental and economic benefits. The shift toward energy-positive waste treatment is particularly attractive to municipalities and industrial operators seeking sustainable and cost-effective solutions. As governments increasingly promote renewable energy initiatives, the development and deployment of advanced WTE-incinerators are expected to gain momentum.
- For instance, Mitsubishi Heavy Industries Environmental & Chemical Engineering Co. successfully developed the Naka Waste-to-Energy Plant in Japan, which generates 13 MW of electricity by processing 396 tonnes of waste per day, utilizing high-efficiency combustion and energy recovery systems.
Expansion in Emerging Economies
Emerging economies, particularly in Asia-Pacific and Latin America, are witnessing rapid infrastructure development and urban population growth, creating substantial opportunities for incinerator market expansion. These regions face mounting waste management challenges, limited landfill capacity, and growing public health concerns. Governments are focusing on adopting modern waste treatment technologies, including incineration, to address these issues efficiently. Investments in new waste management facilities and supportive regulatory frameworks are opening new markets for incinerator manufacturers and service providers.
- For instance, in India, the Okhla Waste-to-Energy Plant operated by Jindal Urban Infrastructure processes 2,000 tonnes of municipal solid waste daily, generating approximately 16 MW of electricity, significantly contributing to New Delhi's waste management capacity.
Key Challenges
High Capital and Operational Costs
One of the primary challenges in the incinerators market is the high initial investment required for building and installing incineration facilities. Additionally, operating costs can be significant, particularly for systems that must meet stringent emission standards through advanced pollution control technologies. These financial barriers may limit adoption, especially in developing countries where budget constraints and competing infrastructure priorities exist. As a result, market penetration in cost-sensitive regions may be slower despite the pressing need for waste management solutions.
Public Opposition and Environmental Concerns
Public resistance to incineration projects, often driven by concerns over air pollution, toxic emissions, and potential health risks, poses a major challenge. Communities sometimes oppose the establishment of incineration plants near residential areas, fearing long-term environmental impacts. Negative perceptions regarding the safety and sustainability of incinerators can delay project approvals and hinder market growth. Overcoming these concerns requires continuous technological improvements, transparent communication, and strict adherence to emission regulations to build public trust.
Competition from Alternative Waste Management Methods
The growing emphasis on recycling, composting, and circular economy practices presents competition to incinerators as waste treatment solutions. Governments and environmental organizations increasingly promote waste reduction and material recovery strategies that prioritize recycling over incineration. In some regions, financial incentives and regulatory support are more favorable toward recycling and biodegradable waste management methods. This competitive pressure may limit the demand for incinerators, especially for waste streams that can be efficiently recycled or repurposed.
Regional Analysis
North America
North America dominated the incinerators market in 2024, accounting for approximately 38.05% of the global market. The market size in the region was valued at USD 6,795.25 million in 2018, which increased to USD 6,892.96 million in 2024, and is projected to reach USD 8,665.70 million by 2032 at a CAGR of 3.0%. The region’s strong waste-to-energy infrastructure and stringent waste management regulations continue to drive market growth. Additionally, increasing investments in modern incineration technologies, especially in the United States and Canada, are supporting the market's expansion across both municipal and industrial sectors.
Europe
Europe held a 25.75% share of the global incinerators market in 2024, with a market size of USD 4,730.20 million in 2018, declining slightly to USD 4,668.54 million in 2024 but projected to recover and reach USD 5,557.16 million by 2032 at a CAGR of 2.3%. The European market is driven by stringent environmental policies, particularly in countries like Germany, France, and the UK, which prioritize emission control and waste minimization. The region’s commitment to sustainable waste management practices, along with advanced incineration technologies, continues to support stable market demand despite growing competition from recycling initiatives.
Asia Pacific
Asia Pacific is the fastest-growing regional market, capturing a 22.27% share in 2024. The market was valued at USD 3,741.80 million in 2018, expanded to USD 4,035.97 million in 2024, and is expected to reach USD 5,710.67 million by 2032, growing at the highest CAGR of 4.5%. Rapid industrialization, urbanization, and increasing municipal solid waste generation in countries like China, India, and Japan are key growth drivers. Additionally, rising government investments in modern waste treatment solutions and the increasing adoption of waste-to-energy systems significantly contribute to the region’s accelerating market growth.
Latin America
Latin America accounted for 4.82% of the global incinerators market in 2024, with a market size of USD 863.09 million in 2018, increasing modestly to USD 874.58 million in 2024, and projected to reach USD 997.88 million by 2032 at a CAGR of 1.7%. The region’s market growth is supported by gradual improvements in waste management infrastructure, particularly in Brazil, Mexico, and Argentina. However, limited government budgets and competing waste management methods such as landfilling and recycling may constrain rapid growth. Increasing awareness of sustainable waste treatment and environmental concerns is expected to slowly strengthen market development.
Middle East
The Middle East represented 3.86% of the global incinerators market in 2024, with the market valued at USD 723.65 million in 2018, decreasing slightly to USD 698.97 million in 2024, but projected to grow to USD 800.35 million by 2032 at a CAGR of 1.8%. The region's growth is supported by rising urbanization, population growth, and a growing need for efficient waste management solutions in countries such as Saudi Arabia, the UAE, and Qatar. However, the market faces challenges due to the dominance of landfill-based waste management and relatively slow adoption of advanced incineration technologies.
Africa
Africa accounted for 5.19% of the global incinerators market in 2024, with a market size of USD 796.02 million in 2018, growing to USD 940.04 million in 2024, and anticipated to reach USD 1,066.60 million by 2032 at a CAGR of 1.4%. The region’s market expansion is driven by the increasing need for proper waste disposal systems amid rising urban populations and public health concerns. Growth is particularly notable in countries like South Africa, Nigeria, and Egypt. However, limited technological infrastructure and financial constraints may continue to restrict the pace of large-scale incinerator adoption across the continent.
Market Segmentations:
By Product:
- Rotary Kiln
- Fluidized Bed
- Grate
- Static Hearth
- Multiple Hearth
- Others
By End Use:
- Municipal
- Industrial
- Others
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The incinerators market is moderately fragmented, with the presence of several regional and international players competing on technology, efficiency, and environmental compliance. Key companies such as Babcock & Wilcox, Mitsubishi Heavy Industries, Keppel Seghers, and Atlas Incinerators hold significant market shares due to their advanced product offerings and strong global presence. These players focus on continuous innovation, strategic partnerships, and mergers to expand their market reach and enhance technological capabilities. Regional companies like Haat Incinerator India and Dutch Incinerators are strengthening their positions by providing cost-effective, customized solutions to local markets. Additionally, growing regulatory pressure on emissions and waste management is prompting companies to invest in eco-friendly and energy-efficient incineration technologies. The competitive landscape is also shaped by increasing demand for waste-to-energy systems, encouraging players to diversify their portfolios with integrated energy recovery solutions. Continuous innovation, environmental performance, and competitive pricing remain critical factors for sustaining market leadership.
Key Player Analysis
- Alfatherm
- Atlas Incinerators
- Babcock & Wilcox
- CHUWASTAR
- Dutch Incinerators
- Gershman, Brickner & Bratton
- Haat Incinerator India
- Incinco
- Keller Manufacturing
- Keppel Seghers
- Ketek Group
- MARTIN
- Maximus Envirotech
- Mitsubishi Heavy Industries
- Vikas Engineering
Recent Developments
- In December 2024, Atlas Incinerators launched the X10 Titan range, starting with the X610 Titan model. This new incinerator allows for the simultaneous incineration of solid waste and oil sludge without preheating the sludge oil, significantly reducing energy consumption, installation complexity, and operational costs. It also boasts an upgraded control system with advanced HMI technology and has received MED-type approval from DNV GL.
- In November 2024, Babcock & Wilcox (B&W) was awarded a contract to conduct a full-scale feasibility study of its SolveBright™ carbon capture technology at Mälarenergi AB’s waste-to-energy plant in Västerås, Sweden. The goal is to capture 400,000 tonnes of CO₂ annually and achieve carbon neutrality by 2035. The study will focus on integrating B&W’s carbon capture system with the plant’s existing waste-to-energy and district heating operations.
- In 2024, Alfatherm supplied a new incinerator to Al Fujairah Municipal Corporation (UAE) for the treatment of bio-medical waste. The incinerator was specifically designed for this purpose, reflecting a focus on tailored solutions for hazardous waste streams.
Market Concentration & Characteristics
The Incinerators Market shows a moderate level of concentration, with several established players holding significant shares across key regions. It features both global companies and strong regional participants competing on technology, efficiency, and regulatory compliance. The market focuses on delivering solutions that meet strict emission standards and support waste-to-energy initiatives. Leading companies prioritize product innovation, strategic partnerships, and capacity expansion to strengthen their competitive positions. It presents a diverse product landscape, including rotary kiln, fluidized bed, and grate-type incinerators, each addressing specific waste treatment needs. The market demonstrates steady demand from municipal and industrial sectors, driven by the increasing need for effective waste management and the growing preference for energy recovery from waste. Companies in this space face cost challenges related to capital investment and system maintenance while striving to improve operational efficiency and environmental performance. Competition remains dynamic, with companies continuously seeking technological improvements to enhance system lifespan and reduce emissions. The Incinerators Market evolves through regulatory shifts, infrastructure upgrades, and changing waste management strategies across different regions.
Report Coverage
The research report offers an in-depth analysis based on Product, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The incinerators market is expected to grow steadily, driven by increasing municipal and industrial waste volumes worldwide.
- Advancements in waste-to-energy technologies will enhance energy recovery efficiency from incineration processes.
- Governments will continue to implement stricter environmental regulations, pushing the adoption of modern, low-emission incinerators.
- Public-private partnerships are likely to increase, supporting the development of large-scale waste treatment facilities.
- Asia Pacific will emerge as the fastest-growing region due to rapid urbanization and infrastructure expansion.
- Investment in portable and small-scale incinerators will rise to meet the needs of remote and specialized waste treatment.
- Companies will focus on integrating air pollution control systems to meet global emission standards.
- Competition will intensify as more players introduce cost-effective and energy-efficient incinerator models.
- Waste management companies will prioritize incineration solutions that offer long-term sustainability and operational safety.
- Growing awareness about environmental safety will drive the demand for advanced incineration technologies across all sectors.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Municipal Solid Waste Generation
Rapid urbanization and population growth are leading to increased municipal solid waste volumes, especially in urban areas where landfill space is limited. This drives municipalities to adopt incineration as an efficient waste management solution that reduces waste volume and enables energy recovery.
Stringent Environmental Regulations
Governments and regulatory bodies are enforcing stricter guidelines on waste disposal and emissions, compelling industries and municipalities to invest in advanced, environmentally compliant incinerators. This regulatory pressure accelerates the adoption of modern incineration technologies.
Growth in Industrial and Hazardous Waste
Industrialization in sectors such as pharmaceuticals, chemicals, and manufacturing is generating more hazardous and non-recyclable waste. The need for safe disposal and compliance with disposal regulations is increasing demand for specialized incinerators capable of handling complex waste streams.
Advancements in Waste-to-Energy Technologies
Innovations in energy recovery systems are making incinerators more attractive by enabling efficient conversion of waste into electricity and heat. This not only addresses waste management challenges but also supports renewable energy goals, making waste-to-energy incinerators a preferred choice.
Expansion in Emerging Economies
Emerging markets in Asia Pacific and Latin America are experiencing rapid infrastructure development and urban growth, leading to greater waste management challenges. Investments in modern incineration facilities and supportive regulatory frameworks are opening new opportunities for market expansion in these regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Incinerator market?
What factors are driving the growth of the Incinerator market?
What are the key segments within the Incinerator market?
What are some challenges faced by the Incinerator market?
Who are the major players in the Incinerator market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Municipal
- 1.2.2 Industrial
- 1.2.3 Others
- 1.3 By Product
- 1.3.1 Rotary Kiln
- 1.3.2 Fluidized Bed
- 1.3.3 Grate
- 1.3.4 Static Hearth
- 1.3.5 Multiple Hearth
- 1.3.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 18,111.06 million → 2032: USD 22,798.36 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Incinerators Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Incinerators Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Incinerators Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Incinerators Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Incinerators Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Incinerators Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Incinerators Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Incinerators Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 18,111.06 million → 2032: USD 22,798.36 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Incinerators Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Municipal
- 12.3.7.2 Industrial
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Rotary Kiln
- 12.4.7.2 Fluidized Bed
- 12.4.7.3 Grate
- 12.4.7.4 Static Hearth
- 12.4.7.5 Multiple Hearth
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Incinerators End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Incinerators Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Incinerators Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Incinerators Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Babcock & Wilcox
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Mitsubishi Heavy Industries
- 18.4 Keppel Seghers
- 18.5 Atlas Incinerators
- 18.6 Dutch Incinerators
- 18.7 Haat Incinerator India
- 18.8 Alfatherm
- 18.9 CHUWASTAR
- 18.10 Gershman, Brickner & Bratton
- 18.11 MARTIN
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

