
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
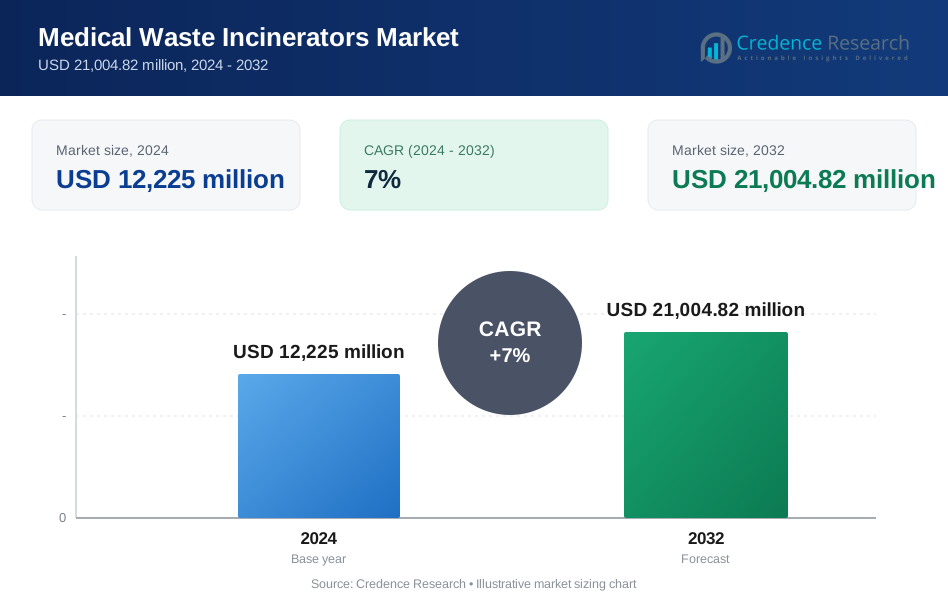
| Medical Waste Incinerators Market Size 2024 | USD 12,225 Million |
| Medical Waste Incinerators Market, CAGR | 7% |
| Medical Waste Incinerators Market Size 2032 | USD 21,004.82 Million |
Market Overview
The Medical Waste Incinerators Market is projected to grow significantly, increasing from USD 12,225 million in 2024 to USD 21,004.82 million by 2032, reflecting a robust compound annual growth rate (CAGR) of 7%.
The medical waste incinerators market is driven by stringent regulations regarding waste disposal and the increasing volume of medical waste generated globally. The rising awareness of environmental sustainability and the adoption of advanced incineration technologies further fuel market growth. Additionally, the growing demand for efficient waste management solutions in healthcare facilities highlights the need for reliable incineration systems. Trends indicate a shift towards environmentally friendly practices, such as energy recovery from waste incineration, which enhances operational efficiency and reduces carbon emissions. Overall, these factors collectively support the market's expansion and innovation.
The geographical landscape of the medical waste incinerators market reveals significant growth opportunities across North America and the Asia-Pacific region. North America, driven by stringent regulations and advanced healthcare infrastructure, holds a substantial market share, with key players like Stericycle AG and Waste Management Inc. leading the sector. In the Asia-Pacific region, expanding healthcare facilities and rising public awareness boost demand, with companies such as Veolia Environmental Services and Triumvirate Environmental playing pivotal roles. These key players are strategically positioned to capitalize on regional growth trends by offering innovative and compliant waste management solutions tailored to local needs.
Market Drivers
Stricter Regulations
Governments worldwide are increasingly implementing stricter regulations to safeguard public health and the environment from the risks posed by improper medical waste disposal. These regulations often mandate the use of specific waste management technologies, such as incineration, which minimizes the environmental impact of healthcare waste. For instance, in Peru, most of the biomedical waste produced is not adequately treated, and the average production of biocontaminated waste from health facilities at the national level ranges between 0.15 and 840 kg/day, depending on the grade and category. By enforcing compliance with stringent waste disposal standards, authorities aim to protect communities from potential health hazards while promoting responsible waste management practices across the healthcare sector.
Rising Healthcare Costs Incineration presents a cost-effective solution for disposing of medical waste, particularly in regions where landfill space is limited or disposal fees are prohibitively high. The adoption of incineration helps healthcare facilities reduce operational costs associated with waste management. For instance, in India, the healthcare sector produced 774 tons of biomedical waste per day in 2020, highlighting the need for efficient disposal methods. Furthermore, proper disposal through incineration mitigates legal risks tied to the improper handling of hazardous materials, ensuring that healthcare providers maintain compliance with regulatory standards and protect their reputations.
Increasing Healthcare Waste Volume
As the global population continues to grow, the demand for healthcare services escalates, resulting in a significant increase in medical waste generation. This surge in healthcare activities, driven by advancements in medical technology and new medical procedures, contributes to the rising volume of healthcare waste. The introduction of innovative pharmaceuticals and complex medical devices also adds to this waste stream, necessitating effective disposal solutions to manage the growing challenges associated with medical waste.
Enhanced Incinerator Technology
Recent advancements in incinerator technology have resulted in more efficient and environmentally friendly systems with significantly reduced emissions. Modern incinerators incorporate advanced pollution control devices designed to minimize air pollution and ensure adherence to environmental regulations. These innovations not only improve the overall efficacy of medical waste disposal but also align with the growing emphasis on sustainability within the healthcare sector. As a result, healthcare facilities are increasingly adopting these advanced incineration technologies to enhance their waste management practices.
Market Trends
Technological Advancements
The medical waste incineration sector is experiencing significant technological advancements that enhance operational efficiency and environmental compliance. For instance, plasma arc technology is being increasingly adopted, as it can handle a broader spectrum of waste types, including hazardous materials and infectious substances. This capability not only ensures safe disposal but also reduces the risks associated with handling diverse waste streams. Additionally, incinerators are now integrating advanced pollution control systems designed to minimize emissions and adhere to stringent environmental regulations. These sophisticated systems help mitigate the environmental impact of incineration, ensuring that healthcare facilities operate in compliance with regulatory standards while maintaining a commitment to sustainability.
Emphasis on Sustainability
A growing emphasis on sustainability is reshaping the medical waste incineration landscape. Incinerators that incorporate energy recovery systems are becoming increasingly popular, as they reduce the overall carbon footprint of waste disposal while generating revenue from the energy produced. This dual benefit aligns with global sustainability goals and appeals to environmentally conscious stakeholders. Moreover, efforts to integrate medical waste incineration into circular economy models are gaining traction, where waste is viewed as a resource rather than a liability. This approach promotes innovative waste management practices that not only improve operational efficiency but also contribute to resource conservation. By treating medical waste as a valuable resource, healthcare facilities can enhance their sustainability initiatives and reduce their environmental impact.
Market Challenges Analysis
High Capital Costs
The medical waste incineration industry faces significant challenges due to high capital costs associated with the installation and operation of incinerators. Data from government surveys indicates that the initial investment required for setting up these facilities can range from hundreds of thousands to millions of dollars, depending on the size and capacity. For instance, a large-scale medical waste incinerator at a referral hospital can have substantial equipment-related capital costs. Operating costs also pose a challenge, with fuel consumption being a major factor. For example, one study found that a large-scale incinerator used an average of 362 L of fuel per day to process medical waste. These costs necessitate careful financial planning and can deter many healthcare providers from investing in incineration technology, especially when budget constraints are a significant concern.
Strict Environmental Regulations
Compliance with strict environmental regulations presents another formidable challenge for the medical waste incineration sector. Incinerators must adhere to rigorous emission standards aimed at minimizing air pollution, including the release of particulate matter, greenhouse gases, and hazardous substances. These regulatory requirements necessitate significant investment in advanced pollution control technologies, which can further elevate capital and operational costs. Additionally, obtaining the necessary permits and licenses for incinerator operations can be a complex and time-consuming process, often involving extensive documentation and approval from various regulatory bodies. This bureaucratic hurdle can delay the implementation of incineration facilities and deter investment in the sector. Furthermore, the increasing scrutiny from environmental advocacy groups and the public amplifies the pressure on healthcare facilities to demonstrate compliance and mitigate environmental impacts, complicating their operations and strategies.
Market Segmentation Analysis:
By Type of Waste:
The medical waste incinerators market is primarily segmented by the type of waste, which includes hazardous and non-hazardous categories. Hazardous waste encompasses materials that pose substantial risks to public health and the environment, such as sharps, infectious waste, and chemical byproducts. This segment necessitates advanced incineration technologies to ensure complete destruction and compliance with stringent regulations. Non-hazardous waste, on the other hand, includes general waste generated from healthcare facilities, which may not present significant risks but still requires proper disposal. As the volume of hazardous waste continues to rise due to increasing healthcare activities, the demand for specialized incinerators capable of handling these materials is expected to grow. Facilities are increasingly adopting dual-capacity incineration systems to manage both hazardous and non-hazardous waste efficiently. This trend highlights the importance of tailored waste management solutions that cater to the diverse needs of healthcare providers, ensuring both safety and environmental compliance while optimizing operational efficiency.
By Service:
In addition to waste type, the medical waste incinerators market can be segmented by service offerings, which include collection, transportation, and storage services, treatment and disposal services, incineration, autoclaving, microwaving, and recycling services. Collection, transportation, and storage services are critical for ensuring that waste is handled safely and efficiently before treatment. Treatment and disposal services encompass various methods, with incineration being the most prevalent due to its effectiveness in managing hazardous waste. Alternative methods such as autoclaving and microwaving are also gaining traction for treating certain waste types, particularly non-hazardous materials. Moreover, the incorporation of recycling services reflects a growing emphasis on sustainability, where healthcare facilities seek to recover valuable materials from waste streams. As healthcare providers increasingly prioritize environmentally friendly practices, the demand for diverse service offerings will likely rise, prompting incinerator manufacturers to innovate and expand their capabilities to meet evolving market needs. This multifaceted approach to waste management is essential for enhancing operational efficiency and compliance within the healthcare sector.
Segments:
Based on Type of Waste
- Hazardous
- Non-hazardous
Based on Service
- Collection, Transportation & Storage Services
- Treatment and Disposable Services
- Incineration
- Autoclaving
- Microwaving
- Others
- Recycling Services
- Others
Based on Waste Generator
- Hospitals
- Laboratories and research centers
- Nursing homes
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant market share in the medical waste incinerators sector, accounting for approximately 40% of the global market. This dominance is largely attributed to the region's advanced healthcare infrastructure, stringent regulatory frameworks, and heightened awareness of environmental sustainability. The increasing volume of medical waste generated due to the proliferation of healthcare facilities, coupled with strict government regulations regarding waste disposal, drives the demand for efficient incineration solutions. Moreover, the adoption of innovative incineration technologies and advanced pollution control systems further enhances the market potential in this region. The presence of key players and ongoing investments in waste management infrastructure are also contributing factors to North America’s robust market position.
Asia-Pacific
In contrast, the Asia-Pacific region is witnessing rapid growth in the medical waste incinerators market, with a market share of approximately 30%. This growth is primarily driven by the expanding healthcare sector, increasing urbanization, and rising public awareness regarding proper medical waste management. Developing countries in this region are experiencing a surge in healthcare infrastructure development, leading to increased waste generation and a corresponding demand for effective disposal solutions. Additionally, the varying regulatory landscapes across countries necessitate tailored incineration solutions to meet specific regional requirements. As governments in the Asia-Pacific region implement stricter waste management regulations, the demand for reliable and efficient incineration technologies is expected to rise significantly. Furthermore, partnerships between public and private sectors to improve waste management practices will bolster market growth, ensuring that healthcare facilities adopt sustainable and compliant waste disposal methods.
Key Player Analysis
- BioMedical Waste Solutions LLC
- Daniels Sharpsmart, Inc.
- Gamma Waste Systems
- GRP & Associates, Inc.
- Republic Services, Inc.
- Stericycle AG
- Triumvirate Environmental
- Veolia Environmental Services
- Waste Management Inc.
- Clean Harbors, Inc.
Competitive Analysis
The competitive landscape of the medical waste incinerators market is characterized by a mix of established players and innovative companies. Leading firms such as Stericycle AG, Waste Management Inc., Clean Harbors, Inc., Veolia Environmental Services, and Triumvirate Environmental dominate the sector, leveraging advanced technologies and comprehensive service offerings. Established firms focus on compliance with stringent regulations and environmental standards while investing in innovative incineration technologies and pollution control systems. Specialized waste handling services and tailored solutions for healthcare providers have become essential in addressing the unique needs of the sector. Additionally, many companies emphasize operational efficiency and customer-centric approaches, which help them differentiate themselves in a crowded market. The competitive dynamics also encourage collaboration and partnerships, enabling companies to enhance their market presence and effectively address the growing demand for efficient medical waste management solutions across various regions. As the market evolves, companies that prioritize sustainability and innovative practices will likely gain a competitive edge.
Recent Developments
- In May 2022, Republic Services acquired the U.S. Ecology to expand in the U.S. and Canada by expanding its environmental solutions business. This platform provided higher cross-selling revenue opportunity and additional acquisitions. This strategy helped the company to increase its market position across the industry.
- In May 2022, Veolia Environnement S.A. acquired Suez Environnement. The companies signed an agreement for the acquisition of all of the hazardous waste assets in France to address the European Commission competition concerns made by Veolia.
Market Concentration & Characteristics
The medical waste incinerators market exhibits moderate concentration, characterized by a mix of large, established firms and smaller specialized companies. Major players often dominate key geographical regions, leveraging their extensive networks and resources to offer comprehensive waste management solutions. These companies typically focus on compliance with stringent environmental regulations, investing in advanced incineration technologies and pollution control systems to minimize emissions. Moreover, the market is marked by innovation, with firms continually developing new technologies to enhance efficiency and reduce operational costs. Additionally, there is a growing emphasis on sustainability, prompting companies to explore alternative waste treatment methods, such as energy recovery and recycling. This evolving landscape encourages collaboration and partnerships among stakeholders, including healthcare providers and waste management firms, aiming to create more effective waste disposal solutions. As the demand for efficient medical waste management increases, market characteristics are likely to shift toward greater integration and technological advancement.
Report Coverage
The research report offers an in-depth analysis based on Type of Waste, Service, Waste Generator and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The medical waste incinerators market is expected to experience significant growth driven by increasing healthcare activities and waste generation.
- Technological advancements will enhance the efficiency and effectiveness of incineration processes, improving emissions control and overall sustainability.
- Regulatory frameworks are likely to become more stringent, prompting healthcare facilities to adopt compliant waste management solutions.
- The trend toward sustainability will encourage the development of incinerators that incorporate energy recovery systems, reducing the carbon footprint.
- Rising awareness of public health risks associated with improper waste disposal will drive demand for reliable medical waste incineration solutions.
- Emerging markets in Asia-Pacific and Africa will present new opportunities for market expansion as healthcare infrastructure continues to develop.
- Increased collaboration between public and private sectors will lead to improved waste management practices and resource sharing.
- The integration of digital technologies, such as IoT and data analytics, will optimize waste management operations and predictive maintenance.
- Healthcare providers will increasingly seek tailored waste management solutions to address their specific waste disposal challenges.
- The competitive landscape will continue to evolve, with mergers and acquisitions driving innovation and expanding service offerings within the industry.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Medical Waste Incinerators market?
What factors are driving the growth of the Medical Waste Incinerators?
What are the key segments within the Medical Waste Incinerators?
What are some challenges faced by the Medical Waste Incinerators?
Who are the major players in the Medical Waste Incinerators?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Medical Waste Incinerators Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Medical Waste Incinerators Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 12,225 million → 2032: USD 21,004.82 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Medical Waste Incinerators Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Medical Waste Incinerators Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Medical Waste Incinerators Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Medical Waste Incinerators Market Drivers
- 3.3 Medical Waste Incinerators Market Restraints & Challenges
- 3.4 Medical Waste Incinerators Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Medical Waste Incinerators Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Medical Waste Incinerators Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Medical Waste Incinerators category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Medical Waste Incinerators Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Medical Waste Incinerators Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Medical Waste Incinerators market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Medical Waste Incinerators Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Medical Waste Incinerators Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Medical Waste Incinerators Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Medical Waste Incinerators (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Medical Waste Incinerators Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Medical Waste Incinerators Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Medical Waste Incinerators Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Medical Waste Incinerators Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Medical Waste Incinerators Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Medical Waste Incinerators Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Medical Waste Incinerators Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Medical Waste Incinerators Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Medical Waste Incinerators Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
