
Market Overview
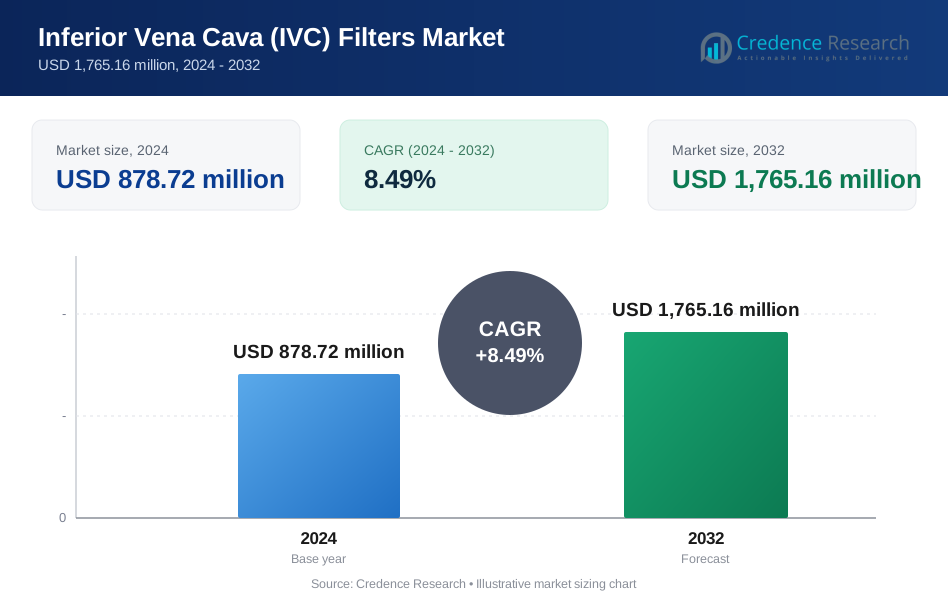
The market for Inferior Vena Cava (IVC) filters is projected to grow from USD 878.72 million in 2024 to USD 1,765.16 million by 2032, reflecting a compound annual growth rate (CAGR) of 8.49%.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Inferior Vena Cava (IVC) Filters Market Size 2024 | USD 878.72 Million |
| Inferior Vena Cava (IVC) Filters Market, CAGR | 8.49% |
| Inferior Vena Cava (IVC) Filters Market Size 2032 | USD 1,765.16 Million |
The market for Inferior Vena Cava (IVC) filters is driven by the rising prevalence of venous thromboembolism (VTE) and an increasing aging population susceptible to related complications. Technological advancements in filter design, such as retrievable filters and improved biocompatibility, enhance safety and efficacy, further stimulating market growth. Additionally, growing awareness about preventive measures in high-risk patients and the rising number of surgical procedures contribute to the demand for IVC filters. Current trends indicate a shift towards minimally invasive techniques and an emphasis on personalized medicine, aligning treatment options with individual patient profiles for better outcomes.
The global Inferior Vena Cava (IVC) filters market is characterized by significant regional dynamics, with North America leading in market share due to advanced healthcare infrastructure and rising awareness of venous thromboembolism. Key players such as Becton Dickinson and Co, Cook Medical, Boston Scientific Corporation, and Medtronic plc dominate the landscape, offering innovative IVC filter solutions. In Europe, companies like Argon Medical Devices and Cardinal Health are gaining traction, driven by increasing adoption rates and regulatory support. Meanwhile, emerging markets in Asia-Pacific present growth opportunities for established firms and new entrants alike, including Johnson & Johnson and VENITI.
Market Drivers
Increasing Prevalence of Venous Thromboembolism (VTE)
The rising incidence of venous thromboembolism (VTE), encompassing conditions like deep vein thrombosis (DVT) and pulmonary embolism (PE), significantly drives the demand for Inferior Vena Cava (IVC) filters. For instance, data from the CDC indicates that up to 900,000 people in the United States are affected by VTE each year, with a significant portion of cases related to hospitalization, cancer treatment, and pregnancy. DVT involves the formation of blood clots in the deep veins of the legs, while PE occurs when these clots travel to the lungs, posing serious health risks. Contributing factors such as sedentary lifestyles, obesity, and an aging population heighten the likelihood of VTE, prompting healthcare providers to recommend IVC filters as an effective preventive measure.
Advancements in IVC Filter Technology
Recent advancements in IVC filter technology have further bolstered market growth. Retrievable filters, which can be removed after the risk of blood clots has diminished, mitigate long-term complications associated with permanent filters. For instance, the introduction of retrievable IVC filters in 2003 has significantly increased their use due to the ability to remove them once the risk of VTE has passed. Additionally, modern designs feature smaller, less invasive filters that reduce procedural risks and improve patient outcomes. These innovations enhance the appeal of IVC filters to both clinicians and patients, driving adoption in clinical settings.
Growing Awareness of VTE and Its Consequences
Growing public awareness regarding the risks and consequences of VTE is increasingly influencing patients to seek preventive measures, including IVC filters. Educational campaigns and improved access to information have empowered individuals to understand their health better, leading to proactive decisions about managing VTE risk. This heightened awareness contributes to a growing market for IVC filters as patients prioritize preventive healthcare.
Increased Use in Minimally Invasive Procedures
The rising preference for minimally invasive surgical techniques is another factor driving demand for IVC filters. These filters are frequently utilized alongside procedures such as laparoscopic surgeries, where the risk of VTE may be elevated. The integration of IVC filters into these practices enhances patient safety and aligns with the current trend toward less invasive interventions, further expanding their market potential.
Market Trends
Shift Towards Retrievable Filters
The market for Inferior Vena Cava (IVC) filters is experiencing a notable shift towards retrievable filters, which offer distinct advantages over traditional permanent options. One of the primary benefits is the reduced risk of complications; retrievable filters can be removed once the risk of blood clots has passed, minimizing potential long-term issues such as filter thrombosis or migration. For instance, a study conducted at an academic medical center in Appalachia found that the rate of IVC filter retrieval was 25.4%, with common reasons for failure of retrieval including loss to follow-up and patient preference. This capability significantly enhances patient safety and comfort. Furthermore, patient preference is increasingly favoring retrievable filters due to their ability to provide peace of mind. Patients are more likely to opt for solutions that allow for intervention after the acute risk has diminished, reflecting a broader trend in healthcare that prioritizes individualized and flexible treatment options.
Advancements in Filter Design and Growing Emphasis on Safety
Technological advancements in filter design are also driving market trends. Manufacturers are focusing on developing smaller and less invasive filters, which reduce the risk of complications and improve patient comfort during and after procedures. Additionally, innovations in filter durability are ensuring that these devices are less likely to fail or degrade over time, thus enhancing their reliability in clinical applications. This focus on safety and efficacy is underscored by the increasing regulatory scrutiny from health authorities, which demand robust evidence regarding the safety and effectiveness of IVC filters. The rise in clinical trials and studies examining long-term outcomes of filter use further emphasizes the commitment to ensuring patient safety and optimal treatment results.
Market Challenges Analysis
Safety Concerns and Complications
Despite the growing adoption of Inferior Vena Cava (IVC) filters, several safety concerns and complications pose significant challenges to their market acceptance. Filter thrombosis, the formation of blood clots within the filter itself, can lead to severe complications, including increased risk of pulmonary embolism. For instance, a survey conducted by the American Society of Hematology highlighted that filter thrombosis is a common complication observed in clinical practice. Additionally, filter migration where the device shifts from its intended position can cause damage to blood vessels or surrounding organs, potentially resulting in life-threatening scenarios. Long-term complications, such as filter fracture or erosion, also remain pressing concerns among healthcare providers and patients alike. These complications underscore the need for careful patient selection and monitoring, as well as robust protocols for managing and mitigating risks associated with IVC filter use. Consequently, these safety issues can hinder widespread acceptance and use in clinical practice, leading to hesitancy among healthcare professionals and patients.
Regulatory Scrutiny and Cost Issues
Regulatory scrutiny of IVC filters has intensified in recent years, complicating their market dynamics. The U.S. Food and Drug Administration (FDA) has issued warnings regarding the potential risks associated with these devices, prompting increased oversight and potential restrictions on their use. Being classified as Class III medical devices means that IVC filters must undergo rigorous testing and approval processes before they can be marketed, leading to longer development timelines and increased costs for manufacturers. Moreover, the high costs associated with IVC filters raise concerns about affordability and reimbursement. Insurance coverage for these devices can be inconsistent, with many insurers imposing restrictions or requiring prior authorization, which further complicates access for patients. The presence of alternative prevention strategies, such as anticoagulant therapy and lifestyle modifications, also presents competitive pressures on the IVC filter market. These factors create a challenging environment for manufacturers and healthcare providers, emphasizing the need for comprehensive strategies to address these hurdles while ensuring patient safety and effective treatment outcomes.
Market Segmentation Analysis:
By Product Type:
The market for Inferior Vena Cava (IVC) filters is categorized into two primary product types: retrievable IVC filters and permanent IVC filters. Retrievable filters are gaining popularity due to their ability to be removed once the risk of thromboembolism has subsided, thus reducing long-term complications. This flexibility appeals to both healthcare providers and patients, particularly in high-risk situations where the duration of filter placement can be uncertain. In contrast, permanent IVC filters remain a staple for patients requiring ongoing protection against venous thromboembolism, such as those with recurrent DVT or PE. As awareness of the risks associated with long-term filter use increases, the preference for retrievable options is likely to drive market growth.
By Material:
The material composition of IVC filters further segments the market into metal and non-metal categories. Metal filters, typically constructed from materials such as stainless steel or titanium, offer durability and strength, making them suitable for long-term use. Conversely, non-metal filters, often made from polymers, are designed to be less invasive and may present reduced complication rates. This diversification in materials allows manufacturers to cater to varying patient needs, ultimately enhancing safety and comfort in clinical applications. As innovations continue, the evolution of IVC filter designs in both metal and non-metal categories will likely play a crucial role in shaping market dynamics.
Segments:
Based on Product Type
- Retrievable IVC Filters
- Permanent IVC Filters
Based on Material
- Metal
- Non-Metal
Based on Placement
- Suprarenal IVC Filters
- Infrarenal IVC Filters
Based on Application
- Deep Vein Thrombosis
- Pulmonary Embolism
- Trauma and Surgical Procedures
- Others
Based on End User
- Hospitals
- Ambulatory Surgical Centers
- Specialty Clinics
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
In North America, the Inferior Vena Cava (IVC) filters market holds a significant share, accounting for approximately 40% of the global market. This dominance is attributed to the high prevalence of venous thromboembolism (VTE) in the region, driven by factors such as sedentary lifestyles and an aging population. For instance, a report by the American Society of Hematology highlighted that the prevalence of VTE is notably high among the elderly population in the United States. The robust healthcare infrastructure, coupled with increased awareness of VTE and its associated risks, has led to a rising demand for IVC filters as a preventive measure. Furthermore, stringent regulatory standards from agencies like the FDA ensure the availability of safe and effective IVC filters, fostering greater adoption in clinical settings. The presence of key market players and ongoing research initiatives to enhance filter technology further contribute to the market’s growth in North America. For example, ongoing research by Johns Hopkins Medicine focuses on improving the safety and efficacy of IVC filters.
Asia-Pacific
In contrast, the Asia-Pacific region is experiencing rapid growth in the IVC filters market, with a projected market share of approximately 25% by 2032. The increasing incidence of lifestyle-related diseases and the expanding aging population in countries like India and China are primary drivers of this growth. Furthermore, rising healthcare expenditures and improving access to advanced medical technologies have led to greater adoption of IVC filters in hospitals and specialty clinics. As healthcare providers in the Asia-Pacific region become more aware of the benefits of preventive measures against VTE, the demand for both retrievable and permanent IVC filters is expected to rise. Additionally, government initiatives aimed at enhancing healthcare quality and accessibility will likely facilitate market growth, positioning the Asia-Pacific region as a critical player in the global IVC filter landscape.
Key Player Analysis
- Becton Dickinson and Co
- Argon Medical Devices
- Cook Medical
- Boston Scientific Corporation
- Braile Biomdica
- Cardinal Health
- R. Bard (acquired by BD)
- VENITI
- Johnson & Johnson
- Medtronic plc
Competitive Analysis
The competitive landscape of the Inferior Vena Cava (IVC) filters market features several leading players: Becton Dickinson and Co, Argon Medical Devices, Cook Medical, Boston Scientific Corporation, Braile Biomdica, Cardinal Health, C. R. Bard (acquired by BD), VENITI, Johnson & Johnson, and Medtronic plc. These companies leverage advanced technologies and robust R&D capabilities to develop innovative IVC filter solutions, enhancing patient safety and treatment efficacy. Major players are focused on expanding their product portfolios through strategic partnerships and acquisitions, enhancing their market presence. Unique filter designs and patient-centric approaches are key differentiators in this competitive environment. Companies strive to improve clinical outcomes, which intensifies the competition. Additionally, regulatory compliance and quality assurance remain critical factors for maintaining market share. Overall, the market is characterized by fierce competition, with firms continuously innovating to solidify their positions in a rapidly evolving healthcare landscape.
Recent Developments
- In October 2024, Medtronic announced a voluntary recall notifying insulin pump users of potential risks of shortened pump battery life.
- In October 2024, Cook Medical is facing ongoing lawsuits related to their IVC filters. As of October 2024, there are 7,634 pending cases in multidistrict litigation against Cook Medical.
- In October 2024, Boston Scientific is defending multiple individual lawsuits about its Greenfield IVC filter. The company won one case in a summary judgment in October 2022.
- In May 2022, Argon Medical announced a partnership with Terumo India, a global leader in medical technology, to bring their products to the Indian market and offer comprehensive solutions for interventional radiology, vascular surgery, interventional cardiology, and clinical oncology.
Market Concentration & Characteristics
The market for Inferior Vena Cava (IVC) filters exhibits moderate to high concentration, dominated by several key players with significant market share. This concentration results from substantial investments in research and development, enabling these companies to innovate and introduce advanced IVC filter technologies. The market characteristics include a strong focus on product differentiation, with manufacturers striving to enhance filter safety, retrievability, and efficacy to meet evolving clinical demands. Regulatory requirements also play a crucial role in shaping market dynamics, as firms must adhere to stringent safety and performance standards. The growing prevalence of venous thromboembolism (VTE) and increased awareness of the benefits of IVC filters further fuel market growth. Additionally, the emergence of new entrants and ongoing mergers and acquisitions among established players contribute to a dynamic competitive environment, fostering innovation and improving patient outcomes. Overall, the IVC filter market is characterized by a blend of stability and ongoing transformation driven by technological advancements.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Material, Placement, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Increasing incidence of venous thromboembolism is expected to drive demand for IVC filters in the coming years.
- Technological advancements will lead to the development of more effective and safer filter designs.
- Growing awareness of the benefits of IVC filters among healthcare professionals and patients will boost adoption rates.
- Regulatory agencies will continue to enforce stringent safety and performance standards, impacting product development timelines.
- Enhanced retrievability features will become a focal point, improving patient outcomes and reducing complications.
- The trend toward minimally invasive procedures will influence the design and use of IVC filters.
- Expansion into emerging markets will present new growth opportunities for established and new players in the industry.
- Increased collaboration and partnerships among key stakeholders will foster innovation and product development.
- The rise of personalized medicine will encourage tailored IVC filter solutions to meet specific patient needs.
- Continuous education and training for healthcare providers will improve the implementation and management of IVC filter therapies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Inferior Vena Cava (IVC) Filters market?
What factors are driving the growth of the Inferior Vena Cava (IVC) Filters?
What are the key segments within the Inferior Vena Cava (IVC) Filters?
What are some challenges faced by the Inferior Vena Cava (IVC) Filters?
Who are the major players in the Inferior Vena Cava (IVC) Filters?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Inferior Vena Cava (IVC) Filters Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Inferior Vena Cava (IVC) Filters Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 878.72 million → 2032: USD 1,765.16 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Inferior Vena Cava (IVC) Filters Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Inferior Vena Cava (IVC) Filters Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Inferior Vena Cava (IVC) Filters Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Inferior Vena Cava (IVC) Filters Market Drivers
- 3.3 Inferior Vena Cava (IVC) Filters Market Restraints & Challenges
- 3.4 Inferior Vena Cava (IVC) Filters Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Inferior Vena Cava (IVC) Filters Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Inferior Vena Cava (IVC) Filters Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Inferior Vena Cava (IVC) Filters category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Inferior Vena Cava (IVC) Filters Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Inferior Vena Cava (IVC) Filters Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Inferior Vena Cava (IVC) Filters market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Inferior Vena Cava (IVC) Filters Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Inferior Vena Cava (IVC) Filters Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Inferior Vena Cava (IVC) Filters Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Inferior Vena Cava (IVC) Filters (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Inferior Vena Cava (IVC) Filters Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Inferior Vena Cava (IVC) Filters Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Inferior Vena Cava (IVC) Filters Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Inferior Vena Cava (IVC) Filters Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Inferior Vena Cava (IVC) Filters Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Inferior Vena Cava (IVC) Filters Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Inferior Vena Cava (IVC) Filters Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Inferior Vena Cava (IVC) Filters Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Inferior Vena Cava (IVC) Filters Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
