
Market Overview:
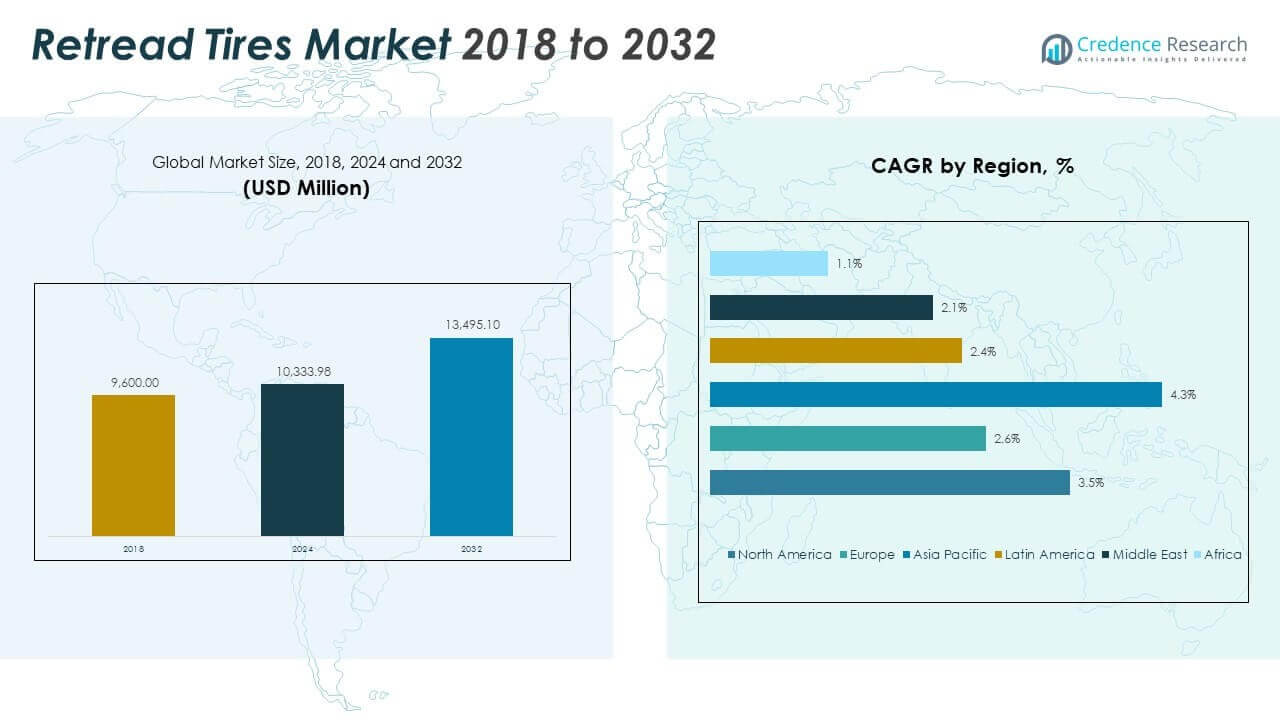
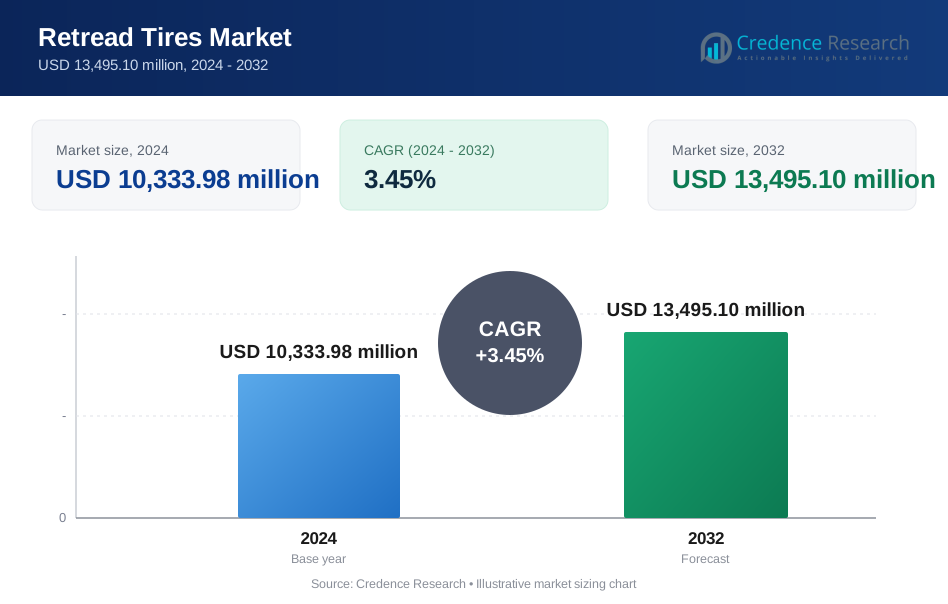
The Retread Tires Market size was valued at USD 9,600.00 million in 2018 to USD 10,333.98 million in 2024 and is anticipated to reach USD 13,495.10 million by 2032, at a CAGR of 3.45% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Retread Tires Market Size 2024 | USD 10,333.98 million |
| Retread Tires Market , CAGR | 3.45% |
| Retread Tires Market Size 2032 | USD 13,495.10 million |
The market is driven by rising demand for cost-effective tire alternatives across logistics, mining, and commercial transportation sectors. Fleet operators increasingly rely on retread tires to extend tire life and reduce total ownership costs. Environmental regulations are encouraging tire recycling, boosting retread adoption. Technological advancements have enhanced durability and traction performance, making retreads more appealing. Structured maintenance cycles support casing recovery and repeat use. Public transport fleets adopt retreads to meet budget targets without compromising safety. The demand for sustainable fleet operations also supports growth in regulated markets.
Asia Pacific leads the market due to its large commercial vehicle population and high cost sensitivity among fleet operators. North America maintains strong demand backed by fleet lifecycle programs and structured casing recovery. Europe shows steady adoption aligned with circular economy policies and product certification mandates. Latin America and Africa are emerging markets where affordability and increasing road transport activity fuel interest in retreading. Middle East adoption is supported by logistics and construction fleets seeking long-term cost savings.
Market Insights:
- The Retread Tires Market was valued at USD 9,600.00 million in 2018, USD 10,333.98 million in 2024, and is projected to reach USD 13,495.10 million by 2032, growing at a CAGR of 3.45%.
- Asia Pacific leads with a 36.76% share, driven by strong logistics activity, low-cost manufacturing, and rising commercial fleet usage. North America holds 28.25%, supported by structured retread programs. Europe accounts for 22.83%, aligning with sustainability goals and strict product standards.
- Asia Pacific is the fastest-growing region at 4.3% CAGR, with demand fueled by cost-sensitive fleet operators, increasing tire recycling, and regional aftermarket networks.
- Heavy Commercial Vehicles dominate vehicle type segmentation due to long-distance wear cycles and high casing recovery, accounting for the largest volume share.
- Pre Cure retreading leads the process type segment, favored for its lower setup costs and widespread use in independent retread shops.
Market Drivers
Growing Preference for Cost-Effective Tire Alternatives Among Commercial Fleets
Commercial fleets consistently seek tire solutions that reduce operational costs without compromising performance. Retread tires offer a lower price point compared to new tires, supporting cost control across logistics and transport firms. Fleet operators gain value by extending tire life through retreading cycles. The Retread Tires Market benefits from this shift toward long-term operational efficiency. It serves a broad range of applications in freight, passenger, and mining vehicles. Large fleet owners increasingly formalize retreading into regular maintenance schedules. OEM partnerships with retreaders also reinforce procurement planning. Demand remains strong in sectors prioritizing high-mileage vehicle use.
- For instance, Michelin reports that their REMIX 2 retreaded tires deliver mileage performance close to 95% of new tires while costing 60% of the price of equivalent new tires.
Stricter Environmental Policies Supporting Tire Recycling Initiatives Globally
Environmental agencies promote tire retreading to reduce landfill waste and raw material extraction. Regulations in North America and Europe encourage commercial fleet operators to reduce tire disposals. The Retread Tires Market aligns with global sustainability goals by minimizing carbon and material footprints. It supports resource circularity by recovering and reusing casing materials. Public policies often offer incentives or mandates for retreading in public transportation fleets. These measures reinforce manufacturer accountability in tire end-of-life management. Compliance requirements also drive upgrades in retreading standards and certifications. Market stakeholders gain regulatory support to improve visibility and growth.
Technological Advancements in Retreading Equipment and Material Formulations
Ongoing upgrades in retreading technology improve tire performance, safety, and mileage reliability. Tread rubber compounds now offer better traction and wear resistance, even in demanding road conditions. The Retread Tires Market benefits from automation in buffing, curing, and inspection stages. It allows consistent output quality across high-volume retread facilities. Tire manufacturers partner with specialized compound suppliers to improve performance. Machine vision and quality control systems now detect casing damage more accurately. Modern retreads closely match new tire standards, earning broader user trust. Retreaders continue to invest in precision tools and compound innovation.
- For instance, Michelin's X MULTI ENERGY D Pre-Mold Retread provides 25% longer tread life through dual energy compound technology and 21/32nds original tread depth.
Fleet Digitization and Data-Driven Lifecycle Monitoring Support Retread Adoption
Digital platforms allow fleet managers to track tire condition and optimize retreading schedules. Tire management systems flag wear patterns and help plan retreading in advance. The Retread Tires Market gains from data-centric decisions around tire reuse. It reduces downtime by aligning retread schedules with vehicle availability. GPS and telematics tools further aid tire lifecycle monitoring. Predictive analytics helps determine casing viability and retread potential. Fleet operators lower replacement frequency and inventory costs through better planning. Smart tracking ensures higher retread efficiency across mixed-vehicle fleets.
Market Trends
OEM Partnerships With Retreaders to Deliver Integrated Tire Lifecycle Services
Original equipment manufacturers now collaborate with retreading companies to offer bundled tire programs. This trend allows end users to receive new tires and guaranteed retread services under a single contract. The Retread Tires Market adapts to customer expectations around full-lifecycle support. It strengthens aftermarket retention and brand loyalty for OEMs. Bundled pricing models allow better cost forecasting for fleet operators. Companies also use co-branding to promote retread quality standards. Integration helps streamline casing return and transportation logistics. This partnership model is gaining traction in regional and national fleet contracts.
- For instance, Bridgestone launched the Bandag BDR-AS3 retread in 2024 for package delivery fleets, featuring a non-directional tread pattern with 22/32nds depth that delivers an 18% improvement in wear over the prior BDR-AS model.
Expansion of Retread Services Across Mining, Military, and Aviation Sectors
Demand for high-performance retreads is expanding beyond commercial trucks into specialized industries. The mining sector, in particular, benefits from retreading large-diameter tires to reduce replacement costs. The Retread Tires Market now serves military fleets with durable, tested retreads that meet mission standards. It is also growing in aviation where certified retread providers meet strict FAA and EASA guidelines. These sectors seek consistent performance under heavy load and variable terrain. The retread process supports tire reusability without compromising safety. New certifications and segment-specific compounds support this diversification trend.
Use of Sustainable and Bio-Based Compounds in Tread Rubber Formulations
Tire retreaders are shifting toward environmentally friendly compounds made from natural or recycled materials. This trend helps reduce reliance on petroleum-derived inputs while supporting sustainability goals. The Retread Tires Market benefits from growing investment in green chemistry and cleaner production. It enables tire makers to meet internal carbon reduction targets. Bio-oils and silica alternatives enhance tread performance while reducing emissions. Some suppliers now promote low-VOC curing processes to meet environmental standards. Demand from ESG-conscious buyers drives this innovation forward. Green compounds are fast becoming a differentiator in retread quality.
Rise in Retread Franchise Models Across Developing Regions for Scale Expansion
Franchise-based expansion is gaining popularity among leading retread brands entering new geographic markets. This model allows local partners to operate under global quality standards while gaining technical support. The Retread Tires Market sees rising investment in India, Southeast Asia, and Latin America under this model. It helps brands maintain control over process integrity and material sourcing. Franchising supports uniform brand visibility and service availability. New entrants reduce startup costs and gain faster access to established demand clusters. Scalable frameworks improve facility replication and operator training in untapped areas.
- For instance, Goodyear has expanded its Wingfoot Commercial Tire Systems franchise network in Asia-Pacific regions, including India, to equip facilities with advanced retreading technology aimed at improving casing utilization in high‑volume operations.
Market Challenges Analysis
Quality Perception Gap Between Retread and New Tires Among Some End Users
Many fleet operators in cost-sensitive regions still hesitate to adopt retread tires due to performance concerns. Despite advancements in compound quality and process precision, retreads face skepticism about safety under harsh driving conditions. The Retread Tires Market continues to address this perception challenge through awareness programs and certifications. It suffers in markets where informal or unregulated retreading practices persist. End users often associate past failures with the broader retread category. Limited access to premium-quality casing inventory also weakens product reliability. Bridging the trust gap remains essential for market growth. Investments in testing, tracking, and branding will help strengthen buyer confidence.
Raw Material Cost Volatility and Used Casing Availability Constraints
Tread rubber pricing is sensitive to fluctuations in natural rubber and petroleum-derived inputs. Price instability impacts profit margins for independent retreaders without bulk sourcing capabilities. The Retread Tires Market also faces uneven access to quality used casings, particularly in emerging economies. It depends on the availability of sound casings from fleets that follow structured tire management. Disruptions in collection networks or improper handling reduce casing recovery rates. Larger fleets often reuse casings internally, limiting supply for small-scale retreaders. Material cost inflation and inconsistent feedstock quality limit production planning and scalability.
Market Opportunities
Government-Led Programs Promoting Tire Retreading in Public Transportation Fleets
Governments across Asia, Latin America, and Africa are implementing mandates to support tire retreading in public buses and freight vehicles. These programs aim to cut imports of new tires and reduce waste volume. The Retread Tires Market benefits from public sector fleet commitments and structured procurement cycles. It also receives technical guidance and funding support to upgrade production standards. Public-private collaboration in setting up retreading facilities increases localized capacity. These initiatives drive long-term adoption, especially in cities with rising bus fleet counts.
Digital Monitoring Tools Creating New Value for Tier 2 and Tier 3 Retreaders
Affordable tire tracking platforms now allow small and mid-sized retreaders to offer digital lifecycle reports. This shift improves service visibility and aligns product offerings with fleet expectations. The Retread Tires Market uses these digital tools to close service gaps and improve customer retention. It also gains insight into wear rates, return cycles, and casing usage trends. Smaller retreaders can now compete with larger networks by leveraging performance transparency and predictive analytics.
Market Segmentation Analysis:
By Vehicle Type
Passenger cars use retread tires in low volumes, mainly in emerging regions with cost-focused consumers. Demand for retreads is highest among heavy commercial vehicles due to long-distance operations and consistent wear patterns. These vehicles generate strong casing recovery rates and structured maintenance schedules, making them ideal for retreading. Light commercial vehicles also contribute to growing volumes, especially in urban logistics and e-commerce fleets. Off-road vehicles in mining and construction sectors rely on retreads to reduce tire replacement costs under rugged conditions. The Retread Tires Market supports all four vehicle classes, with heavy trucks leading adoption due to cost and mileage optimization.
- For instance, Goodyear’s UniCircle® Endurance® LHD retread is engineered for long‑haul commercial trucks with a focus on durability and extended miles to removal, helping fleet operators achieve consistent performance and lower lifecycle costs.
By Process Type
Pre cure retreading dominates due to lower equipment costs and operational flexibility. It allows centralized production of tread rubber, supporting consistent quality and process control. Mold cure is preferred by larger facilities and OEM-aligned retreaders that require tighter performance matching. Mold cure offers precise tread pattern replication but requires higher capital investment. The “Others” category includes advanced hybrid or custom techniques gaining traction in specialized segments. Each process type serves different capacity scales and product quality levels. It allows the market to support both high-volume industrial users and small regional players effectively.
By Sales Channel
Independent service providers dominate the global volume share, especially in cost-sensitive and rural areas. These providers offer flexible pricing and localized casing recovery. OEM-aligned retreaders focus on brand consistency, warranty support, and national contracts. The OEM channel grows in urban and fleet-heavy markets where brand preference and lifecycle assurance matter. It adds value through integrated tire monitoring and return logistics. The Retread Tires Market balances both channels to ensure service access across diverse user segments, from single-vehicle owners to multinational freight carriers.
- For instance, Michelin’s REMIX retread system uses advanced compound technology and casing‑specific processing to help commercial fleets achieve performance close to new tires, while supporting digital traceability of retread casings across service cycles.
Segmentation:
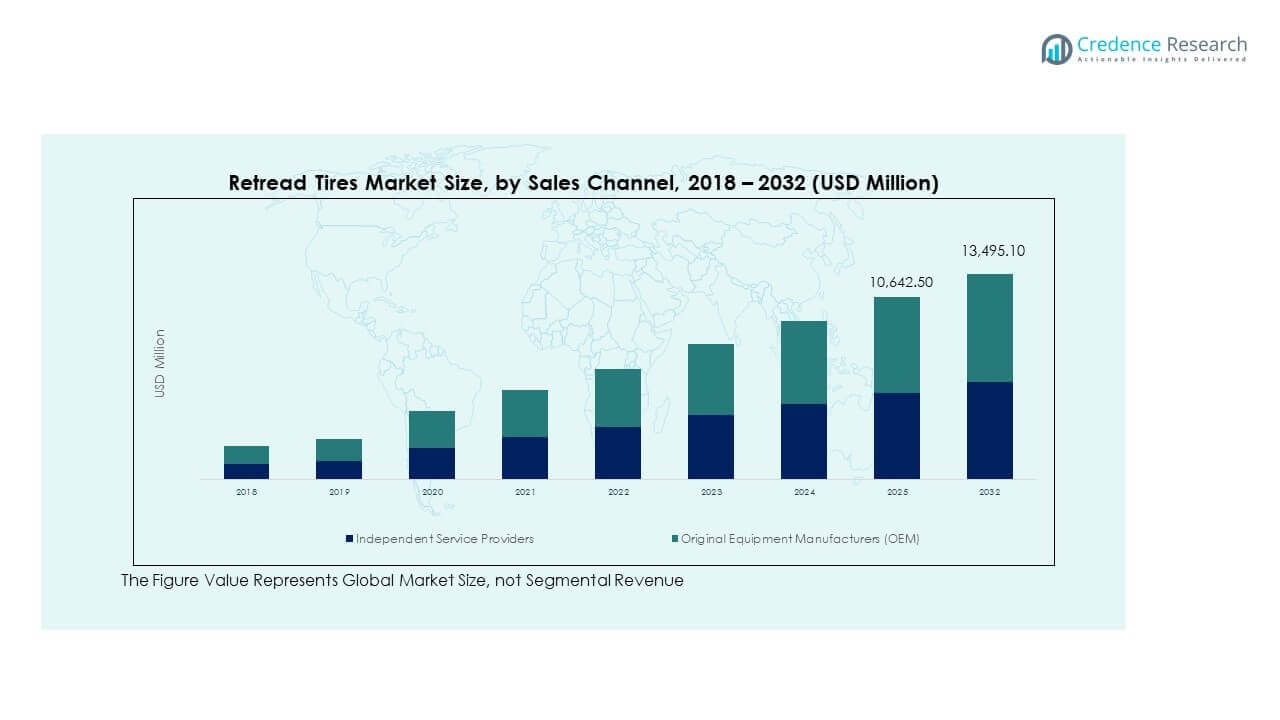
By Vehicle Type
- Passenger Cars
- Heavy Commercial Vehicles
- Light Commercial Vehicles
- Off-road Vehicles
By Process Type
- Pre Cure
- Mold Cure
- Others
By Sales Channel
- Independent Service Providers
- Original Equipment Manufacturers (OEM)
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Retread Tires Market size was valued at USD 2,755.20 million in 2018 to USD 2,920.32 million in 2024 and is anticipated to reach USD 3,806.99 million by 2032, at a CAGR of 3.5% during the forecast period. North America holds approximately 28.25% share of the global market in 2024. Strong adoption across commercial trucking fleets and public transportation drives demand. The region benefits from mature retreading infrastructure, structured casing recovery, and regulatory support for recycling. Fleets prioritize cost control through retread programs integrated with fleet management. High awareness and strict product safety standards support consistent quality. Retreaders in the U.S. often work under OEM alliances, ensuring brand continuity. Mexico and Canada contribute to cross-border growth through logistics fleet expansion. It continues to gain relevance in sustainability-focused procurement.
Europe
The Europe Retread Tires Market size was valued at USD 2,289.60 million in 2018 to USD 2,358.97 million in 2024 and is anticipated to reach USD 2,891.36 million by 2032, at a CAGR of 2.6% during the forecast period. Europe accounts for around 22.83% of the 2024 global revenue. The region follows circular economy frameworks that align well with tire retreading. Germany, France, and Italy are key markets, driven by freight regulations and carbon reduction goals. Product certification under ECE R109 ensures safety compliance across member states. It supports public fleet retreading through municipal contracts and incentive schemes. Commercial adoption is led by long-haul transporters seeking cost and environmental benefits. Limited raw material availability boosts interest in casing reuse. Regional retreaders invest in process standardization to maintain quality benchmarks.
Asia Pacific
The Asia Pacific Retread Tires Market size was valued at USD 3,425.28 million in 2018 to USD 3,799.24 million in 2024 and is anticipated to reach USD 5,318.43 million by 2032, at a CAGR of 4.3% during the forecast period. Asia Pacific holds the largest share at 36.76% in 2024. China and India lead volume due to expansive freight, construction, and mining sectors. Strong aftermarket networks and lower retreading costs support wide-scale adoption. The market benefits from availability of used casings through informal collection channels. Growth is also fueled by government-led transport electrification programs that reuse existing tire assets. Japan and South Korea follow premium retread practices with OEM affiliations. Southeast Asia offers expansion potential due to urban logistics growth. Local players focus on cost-effective mold and pre-cure options.
Latin America
The Latin America Retread Tires Market size was valued at USD 556.80 million in 2018 to USD 593.07 million in 2024 and is anticipated to reach USD 713.49 million by 2032, at a CAGR of 2.4% during the forecast period. Latin America contributes around 5.74% of the global market revenue in 2024. Brazil leads in retread usage due to its vast road freight ecosystem. Economic pressure on fleet operators supports high reliance on retread solutions. Independent service providers dominate the supply structure in most countries. Public sector fleets, especially buses, maintain structured retread cycles. Informal retreaders pose challenges in quality enforcement. Local regulations are improving to standardize safety norms. Argentina and Chile also offer growth through mining and industrial fleet support.
Middle East
The Middle East Retread Tires Market size was valued at USD 364.80 million in 2018 to USD 367.82 million in 2024 and is anticipated to reach USD 433.27 million by 2032, at a CAGR of 2.1% during the forecast period. The region holds a market share of 3.56% in 2024. Fleet operations in logistics, construction, and oilfield transport support retread demand. The UAE and Saudi Arabia lead adoption due to growing infrastructure investment. Retreaders serve cost-sensitive operators through localized services. Limited raw material production encourages casing reuse and recovery. It supports sustainability mandates under national development plans. Imports of new tires make retreading a viable cost-saving measure. OEM partnerships remain limited but expected to expand.
Africa
The Africa Retread Tires Market size was valued at USD 208.32 million in 2018 to USD 294.56 million in 2024 and is anticipated to reach USD 331.56 million by 2032, at a CAGR of 1.1% during the forecast period. Africa accounts for approximately 2.85% of the global market in 2024. The market is driven by budget-conscious fleet owners operating in public and freight transport. South Africa leads with established retread service networks. Many countries rely on used tire imports, making retreading an essential extension strategy. Informal sector presence impacts standardization and safety. It continues to evolve through support from regional development programs. Growing road freight activities increase tire wear, creating long-term retread opportunities. Egypt and Nigeria show rising potential through private fleet modernization.
Key Player Analysis:
- Bridgestone Corporation (Bandag Retreads)
- Michelin (Michelin Retread Technologies)
- Goodyear Tire & Rubber Company
- Continental AG (ContiLifeCycle)
- Marangoni S.p.A.
- Tire Group International (TGI)
- Nokian Tyres
- Oliver Rubber Company
- Kraiburg Austria GmbH & Co. KG
- REMA TIP TOP AG
- Vipal Rubber
- Hawkinson Tire & Retreading
Competitive Analysis:
The Retread Tires Market shows moderate consolidation, with global tire manufacturers and specialized retread firms competing across regions. Leading players such as Bridgestone, Michelin, and Goodyear leverage strong OEM networks, proprietary tread compounds, and certified retread systems to secure long-term fleet contracts. It favors companies that control both casing supply and retreading processes. Mid-sized firms compete through regional reach, pricing flexibility, and service responsiveness. Independent retreaders maintain relevance in cost-sensitive markets through localized operations and faster turnaround times. Technology adoption in quality inspection and process automation creates differentiation. Strategic focus remains on expanding franchise networks, strengthening distributor partnerships, and aligning offerings with sustainability goals. Competitive intensity increases in Asia Pacific due to fragmented supply and rising demand. Firms with strong brand trust and process consistency maintain a clear advantage across commercial vehicle segments.
Recent Developments:
- In Oct 2025, Michelin announced a rollout of TreadEye technology across its U.S. retread network (positioned as a network-wide technology deployment rather than a new tread SKU).
- In July 2024, Bridgestone Corporation (Bandag Retreads) launched the BDR-AS3 retread designed for Package & Delivery and Last-Mile Delivery applications. This tread offers improved runout and cost per mile for supply chain fleets.
- In May 2024, Tireco completed the acquisition of Retread Tire Company, expanding its production capacity and market presence in the Eastern United States to better serve commercial and fleet customers.
Report Coverage:
The research report offers an in-depth analysis based on Vehicle Type, Process Type and Sales Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- OEM-retreader partnerships will expand across North America and Europe to offer lifecycle-based tire services.
- Asia Pacific will remain the highest growth zone due to rising logistics and off-road fleet activity.
- Government recycling mandates will promote wider use of retreads in public transport and municipal fleets.
- Technological upgrades in tread rubber and curing equipment will improve retread reliability and traction.
- Low-cost retreading models will grow in Latin America and Africa, led by local service providers.
- ESG targets will push fleet operators to adopt retreads as a carbon-saving alternative to new tires.
- Franchising models will help global players enter fragmented regional markets with quality control.
- Data-enabled casing tracking will boost retread scheduling and lifecycle planning in large fleets.
- Safety certifications and product traceability will become critical for market share in developed regions.
- Companies will invest in green tread compounds and sustainable processing to meet regulatory norms.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Preference for Cost-Effective Tire Alternatives Among Commercial Fleets
Fleet operators in logistics, mining, and public transport are increasingly adopting retread tires to reduce total ownership costs and extend tire life, making retreads a preferred solution for high-mileage and budget-conscious operations.
Stricter Environmental Policies Supporting Tire Recycling Initiatives Globally
Government regulations and sustainability mandates in regions like North America and Europe are encouraging tire recycling and retreading, reducing landfill waste and supporting circular economy goals, which directly boosts market adoption.
Technological Advancements in Retreading Equipment and Material Formulations
Innovations in tread rubber compounds, automation, and quality control systems have improved the durability, safety, and performance of retread tires, making them more competitive with new tires and increasing user confidence.
Fleet Digitization and Data-Driven Lifecycle Monitoring Support Retread Adoption
The integration of digital platforms and telematics enables fleet managers to monitor tire conditions and optimize retreading schedules, reducing downtime and improving cost efficiency, which drives higher retread utilization.
OEM Partnerships and Integrated Tire Lifecycle Services
Collaborations between original equipment manufacturers and retreaders are expanding, offering bundled tire and retread services that provide lifecycle value, brand assurance, and streamlined procurement for large fleet customers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Retread Tires Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Retread Tires Market projected to grow between 2024 and 2032?
Which Retread Tires Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Retread Tires Market?
Who are the leading companies in the Retread Tires Market?
Which region commanded the largest share of the Retread Tires Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Process Type
- 1.2.1 Pre Cure
- 1.2.2 Mold Cure
- 1.2.3 Others
- 1.3 By Vehicle Type
- 1.3.1 Passenger Cars
- 1.3.2 Heavy Commercial Vehicles
- 1.3.3 Light Commercial Vehicles
- 1.3.4 Off-road Vehicles
- 1.4 By Sales Channel
- 1.4.1 Independent Service Providers
- 1.4.2 Original Equipment Manufacturers (OEM)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 10,333.98 million → 2032: USD 13,495.10 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Retread Tires Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Retread Tires Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Retread Tires Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Retread Tires Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Retread Tires Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Retread Tires Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Retread Tires Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Retread Tires Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 10,333.98 million → 2032: USD 13,495.10 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Retread Tires Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Process Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Pre Cure
- 12.3.7.2 Mold Cure
- 12.3.7.3 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Vehicle Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Passenger Cars
- 12.4.7.2 Heavy Commercial Vehicles
- 12.4.7.3 Light Commercial Vehicles
- 12.4.7.4 Off-road Vehicles
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Independent Service Providers
- 12.5.7.2 Original Equipment Manufacturers (OEM)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Retread Tires Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Retread Tires Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Retread Tires Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Bridgestone Corporation (Bandag Retreads)
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Michelin (Michelin Retread Technologies)
- 17.4 Goodyear Tire & Rubber Company
- 17.5 Continental AG (ContiLifeCycle)
- 17.6 Marangoni S.p.A.
- 17.7 Tire Group International (TGI)
- 17.8 Nokian Tyres
- 17.9 Oliver Rubber Company
- 17.10 REMA TIP TOP AG
- 17.11 Vipal Rubber
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

