
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Kosher Food Market Size 2024 | USD 43,091.27 Million |
| Kosher Food Market, CAGR | 6.31% |
| Kosher Food Market Size 2032 | USD 70,304.36 Million |
Market Overview:
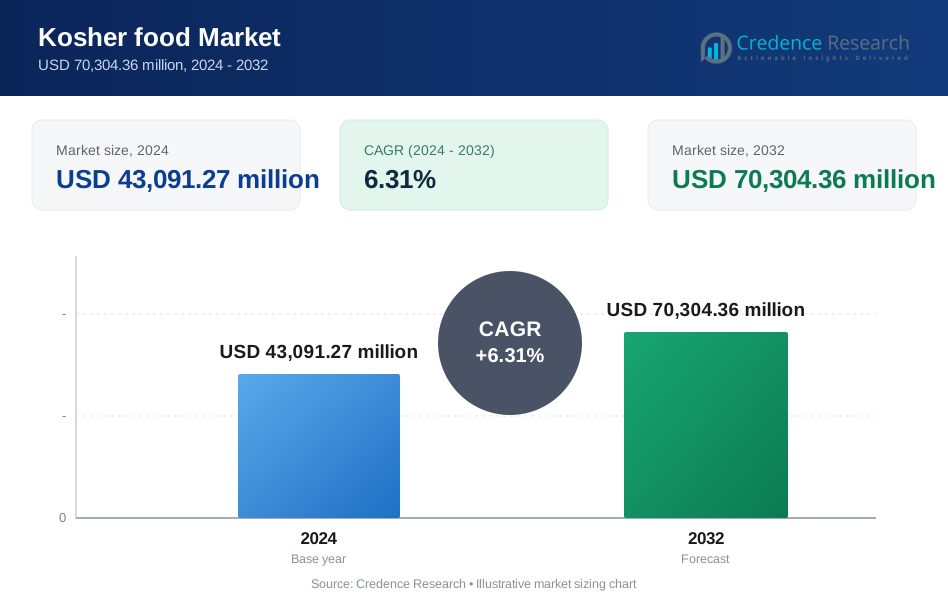
The Global Kosher Food Market is projected to grow from USD 43,091.27 million in 2024 to USD 70,304.36 million by 2032, with a compound annual growth rate (CAGR) of 6.31%.
The kosher food market is driven by increasing consumer demand for clean-label, high-quality, and ethically produced food products that cater to dietary preferences. Health-conscious consumers and those with dietary restrictions, such as lactose intolerance or gluten allergies, are turning to kosher-certified products due to their perceived purity and stringent production standards. The growing popularity of plant-based and vegan diets has also contributed to the expansion of kosher-certified alternatives in the market. Additionally, the rise of e-commerce and global supply chain integration has made kosher products more accessible to a wider audience. Cultural trends, including a broader appreciation for diverse culinary experiences, further fuel the demand for kosher foods beyond traditional religious groups. The kosher certification is increasingly viewed as a marker of safety and quality, which appeals to consumers seeking transparency in food labeling, thereby driving market growth and innovation in product offerings.
The kosher food market demonstrates varying levels of growth across key regions, including North America, Europe, Asia Pacific, the Middle East and Africa, and Latin America. North America leads the market, driven by a large Jewish population and expanding consumer interest in kosher products. Europe follows, with growing demand for clean-label and ethically sourced foods. Asia Pacific is emerging due to increasing awareness of food safety standards, while the Middle East and Africa, particularly Israel, show steady growth due to religious observance. Latin America, though smaller, is also experiencing rising interest in kosher-certified foods. Leading players, such as Nestlé S.A., PepsiCo, Inc., and Tyson Foods, Inc., have a significant presence in these regions, contributing to the global expansion of the kosher food market through their diverse product offerings and strategic market positioning.
Market Insights:
- The global kosher food market is expected to grow from USD 43,091.27 million in 2024 to USD 70,304.36 million by 2032, with a CAGR of 6.31%.
- Increasing consumer demand for clean-label, high-quality, and ethically produced food products is a major driver of market growth.
- Health-conscious consumers, along with those with dietary restrictions like lactose intolerance and gluten allergies, are driving demand for kosher-certified products due to their perceived purity and safety.
- The rising popularity of plant-based and vegan diets is contributing to the expansion of kosher-certified alternatives in the market.
- E-commerce and global supply chain integration are making kosher products more accessible to consumers worldwide, expanding the market reach.
- Kosher certification is increasingly seen as a mark of safety, quality, and transparency in food labeling, appealing to a wider consumer base beyond religious groups.
- North America, Europe, Asia Pacific, the Middle East, Africa, and Latin America are the key regions driving growth in the kosher food market.
Market Drivers:
Growing Consumer Awareness and Demand for Clean-Label Products:
The increasing demand for clean-label and natural food products is a significant driver of the kosher food market. Consumers are becoming more health-conscious and prefer food items that offer transparency in their sourcing and manufacturing processes. Kosher certification, known for its rigorous standards, ensures that the food meets stringent requirements for purity, quality, and ethical production. For instance, Trader Joe's offers a range of kosher-certified snacks and pantry staples, catering to consumers seeking transparency in sourcing and production. As a result, both religious and non-religious consumers are turning to kosher products, perceiving them as safer and of higher quality.
Expansion of Specialty Diets and Food Preferences:
The rise in dietary preferences such as lactose intolerance, gluten allergies, and the growing trend of plant-based diets have further propelled the kosher food market. Many kosher-certified products, particularly in the dairy-free and gluten-free categories, cater to consumers with specific dietary needs. Additionally, the growing vegan and vegetarian populations are finding kosher products appealing due to their clear labeling and the availability of plant-based alternatives, making kosher food a preferred choice for diverse dietary groups.
Increasing Accessibility through E-Commerce and Global Distribution:
The expansion of e-commerce platforms and global supply chains has made kosher food products more accessible to consumers worldwide. Online retailing allows consumers to easily purchase kosher-certified items regardless of their geographical location. The integration of kosher food into mainstream retail channels has also improved the visibility and availability of these products, making it convenient for consumers to access kosher options in both urban and rural areas, thus widening the market reach.
Kosher Certification as a Mark of Quality and Trust:
Kosher certification has increasingly become associated with trust, safety, and quality, driving the demand for kosher products. In a market where consumers seek transparency and ethical standards, the kosher label serves as a reliable indicator of adherence to strict food safety protocols. For instance, leading brands like Coca-Cola have long embraced kosher certification to meet consumer expectations and expand their global market share. This association boosts consumer confidence and fosters a growing market for kosher-certified foods across various product categories.
Market Trends:
Rise of Plant-Based and Vegan Kosher Products:
One of the prominent trends in the kosher food market is the increasing demand for plant-based and vegan products. As consumers become more environmentally conscious and seek alternatives to animal-based products, kosher-certified vegan options have gained significant traction. For instance, Impossible Foods offers kosher-certified plant-based burgers that replicate the taste and texture of meat, catering to both kosher and vegan consumers. These products not only meet the dietary needs of kosher consumers but also appeal to a broader audience looking for sustainable and health-focused food alternatives. The introduction of plant-based meats, dairy substitutes, and ready-to-eat kosher vegan meals reflects the market’s response to this growing trend.
Growing Popularity of Kosher Snacks and Convenience Foods:
Convenience is a key factor driving current trends in the kosher food market, with ready-to-eat meals and snacks experiencing a surge in demand. Busy lifestyles and the need for quick, nutritious meals have prompted manufacturers to introduce a variety of kosher-certified snacks, frozen meals, and on-the-go options. This trend reflects consumer preferences for convenience without compromising on dietary restrictions or food quality, making kosher convenience foods a growing segment in the market.
Expanding Appeal Beyond Religious Communities:
Kosher food is no longer confined to religious communities, as its appeal has expanded to health-conscious and quality-focused consumers across various demographics. The perception that kosher-certified products adhere to higher safety and purity standards has attracted a growing number of non-Jewish consumers. This widening consumer base has prompted food manufacturers to diversify their kosher offerings, extending beyond traditional kosher foods to include a wide range of mainstream and specialty products.
Increasing Innovation in Product Offerings:
The kosher food market is witnessing innovation in product development, with manufacturers introducing new and diverse offerings to meet evolving consumer preferences. For instance, Manischewitz has introduced gluten-free matzo crackers, providing a kosher-certified option for individuals with gluten sensitivities. From gourmet kosher ingredients to organic and gluten-free products, the market continues to evolve with creative solutions that address the demand for high-quality, ethically produced, and diverse food options. This innovation helps sustain market growth and keeps kosher food relevant in an increasingly competitive landscape.
Market Challenges Analysis:
High Costs of Kosher Certification and Compliance:
One of the major challenges in the kosher food market is the high cost associated with obtaining and maintaining kosher certification. The certification process is rigorous, requiring manufacturers to adhere to strict guidelines and undergo regular inspections by kosher certifying authorities. For instance, the Orthodox Union (OU), one of the most recognized kosher certification agencies, mandates thorough audits of every ingredient and production process, which can take months to complete. This can be particularly challenging for small and medium-sized enterprises (SMEs) that may lack the resources to meet these requirements. The added expense of certification often increases production costs, which are ultimately passed on to consumers in the form of higher prices. For businesses trying to maintain competitive pricing while meeting the demand for kosher-certified products, balancing costs and profitability becomes a significant hurdle. Additionally, the need for dedicated kosher production lines or facilities further complicates logistics and adds operational expenses, which can be a barrier for companies entering the kosher market. Over time, this challenge can discourage new entrants and slow the expansion of kosher products into more mainstream markets.
Limited Consumer Awareness and Misconceptions:
Another challenge facing the kosher food market is limited consumer awareness and prevalent misconceptions about kosher certification. Many consumers, especially those outside religious communities, are unfamiliar with the exact meaning and benefits of kosher-certified products. This lack of awareness can lead to confusion and skepticism about the necessity of kosher labeling, reducing the perceived value of such products in the broader market. Furthermore, there are misconceptions that kosher products are only relevant for religious dietary observance, which limits their appeal to a wider audience. Despite the growing popularity of kosher food, bridging the knowledge gap remains a challenge for producers. Marketing and educational efforts are required to highlight the quality, safety, and ethical standards associated with kosher certification to expand the consumer base. Without greater consumer understanding, the market may face limitations in its growth potential as it struggles to communicate the broader benefits of kosher-certified products to a global audience, especially in non-traditional markets.
Market Opportunities:
The kosher food market presents significant growth opportunities driven by increasing consumer demand for healthier, cleaner, and more ethical food options. As the global trend toward transparency in food sourcing and production grows, kosher certification is gaining recognition as a mark of quality and safety. This creates an opportunity for food manufacturers to tap into a broader consumer base beyond traditional religious groups, including health-conscious individuals, vegetarians, and those with dietary restrictions. The expansion of plant-based and allergen-free products within the kosher market also provides ample opportunity for companies to innovate and meet the evolving preferences of modern consumers seeking sustainable and ethical food choices.
Another opportunity lies in the growing accessibility of kosher products through e-commerce and global retail channels. As online shopping continues to expand, especially in underserved markets, kosher food companies can leverage digital platforms to reach a wider and more diverse audience. Increased consumer awareness about kosher standards, paired with the convenience of online shopping, can drive demand across various regions where kosher products have historically been less available. Additionally, the potential for collaboration between food producers and kosher certifying agencies offers a way to enhance product offerings, increase visibility, and build consumer trust. By capitalizing on these opportunities, the kosher food market is well-positioned for sustained growth and expansion in the coming years.
Market Segmentation Analysis:
By Type
The kosher food market is segmented by type into categories such as meat, dairy, pareve (neutral), and other processed foods. Among these, pareve and plant-based products are experiencing the fastest growth due to rising demand for vegan, vegetarian, and allergen-free alternatives, offering diverse choices for health-conscious consumers.
By Application
Kosher food finds applications across various sectors, including processed foods, beverages, snacks, and bakery products. The growing popularity of kosher-certified processed and convenience foods, coupled with consumer preferences for ready-to-eat meals and snacks, is driving demand in this segment, especially among non-religious and global consumers.
By Distribution Channel
The distribution channel segment includes supermarkets, hypermarkets, specialty stores, and online platforms. E-commerce has become a key driver of growth, with online platforms offering easy access to a wide range of kosher products, while supermarkets and specialty stores continue to cater to consumers seeking certified kosher items in physical retail locations.
Segments:
Based on Type:
- Buckwheat
- Seafood
- Lamb
- Pulses
- Others
Based on Application
- Culinary Products
- Snacks and Savory
- Baker and Confectionery Products
- Beverages
- Meat
- Dietary Supplements
Based on Distribution Channel
- Offline
- Online
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the kosher food market, accounting for 40% of the global market in 2024. The significant Jewish population in the region, particularly in the United States, has long been a key driver of demand for kosher-certified products. However, the market's growth has expanded beyond religious consumers to include health-conscious individuals, those with dietary restrictions, and consumers who perceive kosher foods as higher quality or safer. The presence of well-established kosher food manufacturers and widespread availability of kosher products in supermarkets and specialty stores further bolster North America's market dominance. Additionally, the region has seen a rise in plant-based and vegan kosher options, contributing to the expanding market base.
Europe
Europe represents 25% of the global kosher food market in 2024, driven by both religious and secular demand. Countries such as France and the United Kingdom have substantial Jewish communities that maintain a steady demand for kosher-certified products. Moreover, the growing trend toward clean-label and ethically sourced food has encouraged non-Jewish consumers in Europe to embrace kosher options. The European market is also seeing a rise in the availability of kosher-certified snacks, convenience foods, and gourmet products. The expansion of online retail platforms has made it easier for European consumers to access a wide variety of kosher products, contributing to market growth in the region.
Asia Pacific
The Asia Pacific region holds 18% of the kosher food market share in 2024. Although the Jewish population in this region is relatively small, the rising interest in kosher certification is driven by a growing awareness of food safety and quality. Countries such as China, India, and Japan are witnessing increasing demand for kosher-certified products, particularly among health-conscious consumers and those with dietary restrictions. The expansion of e-commerce platforms has facilitated greater access to kosher products across the region, helping to boost market growth. Additionally, kosher certification is often seen as a sign of adherence to high food safety standards, which appeals to a broader range of consumers in Asia Pacific.
Middle East and Africa
The Middle East and Africa account for 10% of the global kosher food market share in 2024. In this region, demand for kosher products is primarily driven by religious observance, with a sizable Jewish population in Israel contributing to steady market growth. The Middle East, particularly Israel, has a well-established kosher food industry that caters to both domestic and export markets. In Africa, the market for kosher-certified products is relatively small but growing, with increasing awareness of kosher standards in food safety and quality. The rise of digital retail channels is also contributing to greater availability of kosher products in these regions, helping to drive demand.
Latin America
Latin America represents 7% of the global kosher food market in 2024. While the region has a smaller Jewish population, countries such as Argentina and Brazil are seeing a growing interest in kosher products due to their association with high food safety standards and quality. The market is also supported by the increasing popularity of kosher-certified snacks and convenience foods. Latin America’s kosher food market is benefiting from the rise of e-commerce, which is making kosher products more accessible to consumers in urban areas across the region.
Key Player Analysis:
- Tyson Foods, Inc.
- General Mills, Inc.
- The Hershey Company
- ConAgra Foods, Inc.
- Hormel Foods Corporation
- Nestlé S.A.
- Archer Daniels Midland Company
- The Kraft Heinz Company
- PepsiCo, Inc.
- Mars, Incorporated
- Coca-Cola Company
- Unilever PLC
- Kellogg Company
Competitive Analysis:
The kosher food market is highly competitive, with leading players such as Nestlé S.A., ConAgra Foods, Inc., General Mills, Inc., PepsiCo, Inc., Kellogg Company, The Kraft Heinz Company, Tyson Foods, Inc., Mars, Incorporated, Unilever PLC, Hormel Foods Corporation, The Hershey Company, Coca-Cola Company, and Archer Daniels Midland Company playing a dominant role. These companies leverage their strong brand recognition, vast distribution networks, and wide product portfolios to maintain a competitive edge in the market. Many of these players are focusing on expanding their kosher-certified product lines to cater to the growing demand for ethical, high-quality, and clean-label food options. They also capitalize on innovation, introducing plant-based, gluten-free, and allergen-free kosher products to appeal to health-conscious and non-traditional kosher consumers. Additionally, partnerships with e-commerce platforms and investments in marketing strategies enhance their visibility and accessibility, positioning them as key drivers in the global expansion of the kosher food market.
Recent Developments:
- In May 2024, Tofurky, a US-based producer of plant-based meat substitutes, introduced its next-generation plant-based Deli Slices. These pre-seasoned, heat-and-serve roasts offer a convenient, kosher-friendly alternative for consumers aiming to reduce meat consumption.
- In April 2024, Forward Consumer Partners (FCP), a US-based private equity firm, acquired Firehook Bakery, a kosher artisanal baked goods manufacturer, for an undisclosed sum. The acquisition enables Firehook to tap into FCP's expertise and resources, driving its brand expansion.
- In July 2023, Cargill Incorporated and John Deere announced a collaboration to enhance the digital and in-field experience for farmers using John Deere technology, particularly those participating in the Cargill RegenConnect program.
- In March 2023, Cargill unveiled its Diamond Crystal Fine Kosher Salt, designed to elevate the flavor of fried foods and seasonings. This move capitalizes on the growing popularity of kosher products, reinforcing Cargill's commitment to culinary innovation and quality.
Market Concentration & Characteristics:
The kosher food market is moderately concentrated, with a mix of global giants and smaller, specialized players. Major companies, such as Nestlé S.A., PepsiCo, Inc., and Tyson Foods, Inc., dominate the market due to their vast distribution networks, strong brand recognition, and diversified product offerings. Despite this, the market still offers opportunities for niche players who focus on high-quality, artisanal, or specialty kosher products. These smaller firms often cater to local or specific dietary preferences, allowing them to carve out a loyal customer base. The market is characterized by a growing demand for transparency, safety, and ethical production, which has led to increased competition in the clean-label, plant-based, and allergen-free segments. Additionally, the rise of e-commerce has leveled the playing field, giving smaller companies greater access to consumers and expanding the reach of kosher-certified products globally.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The kosher food market is expected to see continued growth driven by increasing consumer demand for clean-label and ethically produced products.
- Health-conscious consumers will likely continue to turn to kosher-certified products for their perceived purity and high safety standards.
- The rise of plant-based and vegan diets will further contribute to the expansion of kosher-certified food alternatives.
- E-commerce will play a crucial role in making kosher products more accessible to a global audience.
- Kosher certification will continue to be viewed as a marker of quality and safety, appealing to both religious and non-religious consumers.
- Innovation in product development, particularly in allergen-free and specialty diets, will drive market differentiation.
- North America will remain the leading region, with strong demand from Jewish and non-Jewish consumers alike.
- Europe and Asia Pacific are expected to see increased demand due to rising food safety awareness.
- Smaller niche companies focusing on artisanal or specialty kosher products will find growth opportunities.
- Growing awareness and education about kosher standards will expand the consumer base globally.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Kosher Food Market?
What factors are driving the growth of the Kosher Food Market?
What are the key segments within the Kosher Food Market?
What are some challenges faced by the Kosher Food Market?
Who are the major players in the Kosher Food Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Kosher food Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Kosher food Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 43,091.27 million → 2032: USD 70,304.36 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Kosher food Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Kosher food Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Kosher food Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Kosher food Market Drivers
- 3.3 Kosher food Market Restraints & Challenges
- 3.4 Kosher food Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Kosher food Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Kosher food Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Kosher food category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Kosher food Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Kosher food Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Kosher food market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Kosher food Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Kosher food Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Kosher food Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Kosher food (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Kosher food Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Kosher food Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Kosher food Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Kosher food Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Kosher food Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Kosher food Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Kosher food Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Kosher food Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Kosher food Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
