
Market Overview
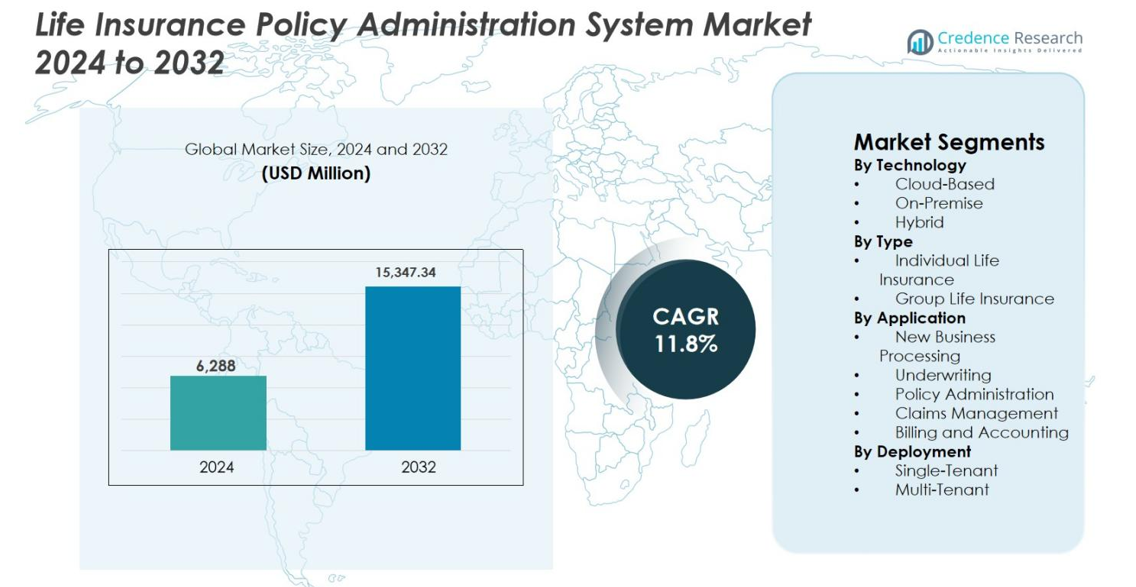
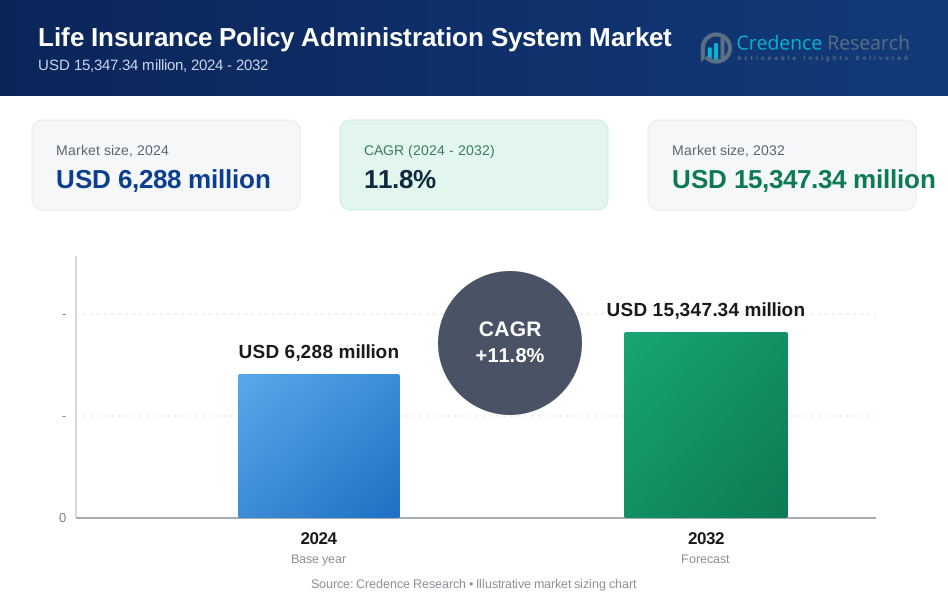
The Life Insurance Policy Administration System market size was valued at USD 6,288 million in 2024 and is anticipated to reach USD 15,347.34 million by 2032, expanding at a CAGR of 11.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Life Insurance Policy Administration System Market Size 2024 | USD 6,288 million |
| Life Insurance Policy Administration System Market, CAGR | 11.8% |
| Life Insurance Policy Administration System Market Size 2032 | USD 15,347.34 million |
Life Insurance Policy Administration System market is characterized by the strong presence of established insurance software providers and global IT service firms focused on core system modernization and digital enablement. Leading players such as Majesco, Oracle, Accenture, Infosys, EIS Group, Insurity, EXL, FAST Technology, and Edlund compete through configurable platforms, cloud-native deployments, and deep insurance domain expertise. These companies invest in automation, analytics, and API-driven integration to support complex policy lifecycles and regulatory compliance. Regionally, North America leads the market with a 38.4% share, supported by early technology adoption and large-scale modernization initiatives, followed by Europe at 26.1% and Asia-Pacific at 22.7%, where rapid digital insurance expansion continues to strengthen market momentum.
Market Insights
- Life Insurance Policy Administration System market was valued at USD 6,288 million in 2024 and is projected to reach USD 15,347.34 million by 2032, growing at a CAGR of 11.8% through the forecast period, driven by increasing digitalization and core insurance system modernization initiatives.
- Growing demand for automated policy lifecycle management, faster product launches, and enhanced customer experience drives adoption, with cloud-based deployment leading the technology segment at a 58.6% share.
- Market trends highlight increased adoption of SaaS models, API-driven ecosystems, and analytics-enabled platforms, while policy administration applications dominate with a 41.8% segment share.
- The competitive environment includes specialized insurance software providers and global IT firms focusing on configurable platforms, cloud migration, and system integration to strengthen insurer agility.
- Regionally, North America leads with a 38.4% market share, followed by Europe at 26.1% and Asia-Pacific at 22.7%, while emerging regions show steady growth driven by digital insurance expansion.
Market Segmentation Analysis:
By Technology
The Life Insurance Policy Administration System market is segmented into cloud-based, on-premise, and hybrid deployment models. Cloud-based systems dominate the segment, accounting for 58.6% market share, driven by scalability, faster implementation, and lower total cost of ownership. Insurers increasingly adopt cloud platforms to support digital policy servicing, remote operations, and rapid product configuration. Built-in analytics, API integration, and regulatory updates further strengthen adoption. Hybrid solutions are gaining traction among mid-to-large insurers seeking gradual modernization, while on-premise systems retain relevance in regions with strict data-sovereignty and legacy infrastructure constraints.
- For instance, Infosys McCamish’s NGIN platform is positioned as a cloud-native life insurance and annuity policy administration system used by global insurers to manage complete policy lifecycles with multi-geo support and scalable infrastructure
By Type
Based on type, the Life Insurance Policy Administration System market includes individual life insurance and group life insurance. Individual life insurance leads with a 64.2% share, supported by rising demand for personalized policies, flexible premium structures, and long-term protection products. Insurers require advanced systems to manage complex policy lifecycles, endorsements, renewals, and customer servicing. Growth in middle-class populations, digital direct-to-consumer channels, and product customization drives system adoption. Group life insurance systems grow steadily, fueled by employer-sponsored coverage expansion and automation needs for high-volume policy administration.
- For instance, MetLife modernized its individual life operations by deploying advanced policy administration platforms that support configurable products, automated underwriting workflows, and continuous policy servicing across digital channels.
By Application
By application, the market covers new business processing, underwriting, policy administration, claims management, and billing and accounting. Policy administration is the dominant sub-segment with a 41.8% market share, as it forms the operational core of life insurers. Demand is driven by the need for real-time policy updates, automated endorsements, compliance management, and seamless customer servicing. Integration with CRM, analytics, and digital channels enhances efficiency and retention. Increasing policy volumes, regulatory complexity, and the shift toward straight-through processing further accelerate adoption of advanced policy administration modules.
Key Growth Drivers
Digital Transformation and Core System Modernization
Accelerated digital transformation across the insurance sector is a primary growth driver for the Life Insurance Policy Administration System market. Insurers are replacing legacy, monolithic platforms with modern, configurable policy administration systems to improve agility, reduce operational costs, and support faster product launches. Modern systems enable straight-through processing, automated workflows, and real-time policy servicing, significantly enhancing operational efficiency. Increasing customer expectations for digital onboarding, self-service portals, and omnichannel engagement further push insurers to modernize core systems. Additionally, regulatory complexity and frequent product changes require flexible platforms that support rapid configuration and compliance updates. As insurers prioritize modernization to remain competitive and digitally resilient, demand for advanced policy administration solutions continues to rise steadily.
- For instance, AXA advanced its digital transformation by modernizing life insurance core systems to enable straight-through processing, automated underwriting, and real-time policy servicing, improving speed and operational efficiency across customer touchpoints.
Rising Demand for Product Personalization and Faster Time-to-Market
Growing demand for personalized life insurance products strongly drives adoption of advanced policy administration systems. Customers increasingly seek flexible coverage options, customized riders, dynamic premium structures, and usage-based features. To meet these expectations, insurers require systems capable of rapid product configuration, rule-based pricing, and automated policy lifecycle management. Modern platforms allow insurers to quickly design, test, and launch new products without extensive coding, significantly reducing time-to-market. This capability supports competitive differentiation in crowded markets. Additionally, personalized offerings generate higher customer engagement and retention, making robust policy administration systems a strategic investment for insurers focused on long-term growth and profitability.
- For instance, HDFC Life has strengthened its digital product architecture through advanced policy administration capabilities that enable rapid customization of individual life products and seamless servicing through digital channels
Expansion of Digital Distribution and Direct-to-Consumer Channels
The rapid expansion of digital distribution channels is another major growth driver for the Life Insurance Policy Administration System market. Insurers increasingly rely on online portals, mobile applications, bancassurance platforms, and digital agents to acquire and service customers. These channels require seamless integration with core policy administration systems to enable real-time underwriting decisions, instant policy issuance, and automated billing. Advanced platforms support API-based connectivity, enabling insurers to partner with fintechs, aggregators, and embedded insurance providers. As digital sales volumes increase, insurers must scale policy processing and servicing efficiently, reinforcing demand for robust, cloud-enabled policy administration systems.
Key Trends & Opportunities
Shift Toward Cloud-Based and SaaS Deployment Models
The transition toward cloud-based and software-as-a-service deployment models represents a key trend and opportunity in the Life Insurance Policy Administration System market. Insurers increasingly adopt cloud platforms to achieve scalability, faster implementation, and reduced infrastructure costs. Cloud-based systems enable continuous updates, rapid regulatory compliance, and improved disaster recovery capabilities. They also support advanced analytics, AI-driven automation, and remote operations. For vendors, cloud adoption opens opportunities to offer modular, subscription-based solutions that appeal to small and mid-sized insurers. As regulatory acceptance of cloud environments improves globally, cloud deployment continues to unlock long-term growth opportunities.
- For instance, Zurich Insurance Group has migrated core insurance workloads to cloud platforms to enable continuous system updates, stronger disaster recovery, and faster regulatory compliance across multiple regions.
Integration of Advanced Analytics and Intelligent Automation
Integration of advanced analytics, artificial intelligence, and intelligent automation is emerging as a major opportunity for policy administration system providers. Insurers leverage analytics to gain real-time insights into policy performance, customer behavior, and operational efficiency. AI-enabled automation enhances underwriting accuracy, detects anomalies in policy servicing, and streamlines claims and billing processes. Intelligent workflows reduce manual intervention, lower error rates, and improve customer experience. Vendors that embed analytics and automation capabilities within core policy administration platforms can deliver higher value, supporting data-driven decision-making and operational optimization across the insurance value chain.
- For instance, Sun Life Financial leverages intelligent automation and analytics embedded in its policy administration platforms to streamline billing, policy changes, and customer inquiries, enabling faster turnaround times and consistent omnichannel experiences.
Key Challenges
Complexity of Legacy System Migration and Data Integration
Migrating from legacy policy administration systems presents a significant challenge for insurers. Legacy platforms often contain decades of policy data, customized workflows, and regulatory configurations, making migration complex and time-consuming. Data cleansing, mapping, and validation require substantial effort and expertise. Integration with surrounding systems such as claims, billing, CRM, and third-party platforms further increases implementation risk. Any disruption during migration can impact policy servicing and customer trust. These complexities may delay modernization initiatives and increase project costs, posing a barrier to faster adoption of new policy administration systems.
Regulatory Compliance and Data Security Concerns
Regulatory compliance and data security remain critical challenges in the Life Insurance Policy Administration System market. Insurers must comply with evolving data protection laws, reporting requirements, and solvency regulations across multiple jurisdictions. Policy administration systems handle sensitive customer data, making them prime targets for cyber threats. Ensuring data privacy, secure access controls, and regulatory audit readiness adds to system complexity. Cloud adoption, while beneficial, raises additional concerns around data residency and third-party risk management. Vendors and insurers must continuously invest in security frameworks and compliance capabilities, increasing operational and implementation costs.
Regional Analysis
North America
North America leads the Life Insurance Policy Administration System market with a 38.4% market share, driven by early adoption of digital insurance platforms and large-scale core system modernization initiatives. Insurers across the US and Canada actively replace legacy policy systems to improve operational efficiency, regulatory compliance, and customer experience. Strong demand for cloud-based solutions, API-driven ecosystems, and analytics-enabled policy servicing supports market growth. High insurance penetration, complex product portfolios, and stringent regulatory requirements further accelerate investment in advanced policy administration systems, making North America the most mature and technology-driven regional market.
Europe
Europe accounts for 26.1% of the Life Insurance Policy Administration System market, supported by regulatory-driven modernization and rising digital adoption among insurers. Compliance with frameworks such as GDPR and Solvency II increases demand for flexible, audit-ready policy administration platforms. European insurers focus on system upgrades to support product standardization, cross-border operations, and digital servicing. Cloud adoption is growing steadily, particularly in Western Europe, while hybrid deployments remain common. The region’s emphasis on data security, operational transparency, and customer-centric insurance models continues to drive sustained system investments.
Asia-Pacific
Asia-Pacific represents the fastest-growing region, holding a 22.7% market share in the Life Insurance Policy Administration System market. Growth is driven by rapid expansion of life insurance penetration, rising middle-class populations, and digital-first insurance models in countries such as China, India, Japan, and Southeast Asia. Insurers increasingly adopt cloud-based platforms to support high policy volumes, digital onboarding, and scalable operations. Regulatory reforms and government-led financial inclusion initiatives further boost demand. The region’s strong focus on automation and cost-efficient system deployment accelerates adoption among both large and emerging insurers.
Latin America
Latin America holds 7.4% market share in the Life Insurance Policy Administration System market, supported by gradual digital transformation across the insurance sector. Insurers in Brazil, Mexico, and Chile increasingly invest in modern policy systems to improve operational efficiency and expand digital distribution. Cloud-based deployments gain traction due to lower upfront costs and faster implementation. Growing awareness of life insurance products, coupled with regulatory modernization, drives system upgrades. However, budget constraints and legacy infrastructure challenges moderate adoption speed, resulting in steady but comparatively slower market growth.
Middle East & Africa
The Middle East & Africa region accounts for 5.4% of the Life Insurance Policy Administration System market, driven by expanding insurance penetration and digitalization initiatives. Gulf countries lead adoption due to strong financial infrastructure, regulatory reforms, and investments in digital insurance platforms. Insurers focus on modern systems to support product diversification, regulatory reporting, and improved customer engagement. In Africa, adoption remains nascent but growing, supported by mobile-based insurance models and financial inclusion programs. Increasing demand for scalable, cloud-enabled solutions supports long-term regional growth potential.
Market Segmentations:
By Technology
- Cloud-Based
- On-Premise
- Hybrid
By Type
- Individual Life Insurance
- Group Life Insurance
By Application
- New Business Processing
- Underwriting
- Policy Administration
- Claims Management
- Billing and Accounting
By Deployment
- Single-Tenant
- Multi-Tenant
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Life Insurance Policy Administration System market features a competitive landscape characterized by the presence of global technology providers, specialized insurance software vendors, and system integrators competing on functionality, scalability, and deployment flexibility. Key players such as Majesco, Oracle, Accenture, Infosys, EIS Group, Insurity, EXL, FAST Technology, and Edlund focus on delivering configurable, cloud-enabled platforms that support end-to-end policy lifecycle management. Vendors increasingly differentiate through modular architectures, low-code configuration, and API-driven integration to support rapid product launches and digital channels. Strategic partnerships with insurers, cloud service providers, and fintech firms are common to expand solution capabilities and geographic reach. Continuous investment in analytics, automation, and regulatory compliance features strengthens vendor positioning, while system integration expertise and post-implementation support play a critical role in winning large transformation projects.
Key Player Analysis
- EIS Group Inc.
- Infosys
- Majesco
- EXL
- Oracle
- Edlund
- Accenture Plc
- FAST Technology
- Insurity
- Accenture Life Insurance Solutions Group
Recent Developments
- In January 2025, Majesco announced that Celina Insurance Group selected Majesco Intelligent Claims for P&C to modernize its claims operations, boost workforce productivity, optimize business processes, and improve overall customer experience.
- In September 2024, the Life Insurance Corporation (LIC) revealed a strategic collaboration with Infosys to build a next-generation digital platform that will underpin critical business applications, including customer and sales super apps, digital branches, and integrated portals.
Report Coverage
The research report offers an in-depth analysis based on Technology, Type, Application, Deployment and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Insurers will continue accelerating replacement of legacy policy systems to improve agility and reduce operational complexity.
- Cloud-based and SaaS policy administration platforms will see sustained adoption across large and mid-sized insurers.
- Demand for configurable and low-code systems will increase to support rapid product innovation and customization.
- Integration of artificial intelligence and automation will enhance underwriting, policy servicing, and operational efficiency.
- API-driven ecosystems will strengthen connectivity with digital channels, fintech partners, and third-party platforms.
- Insurers will prioritize real-time data processing to improve customer experience and policy lifecycle visibility.
- Regulatory compliance capabilities will become a core differentiator for policy administration system providers.
- Cybersecurity and data privacy features will gain increased focus as digital policy volumes grow.
- Emerging markets will drive incremental demand through rising insurance penetration and digital-first models.
- Vendors will expand modular offerings and managed services to support long-term insurer transformation strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Digital Transformation and Core System Modernization
Insurers are rapidly replacing legacy policy administration systems with modern, configurable platforms to improve agility, reduce operational costs, and enable faster product launches. This modernization supports straight-through processing, automated workflows, and real-time policy servicing, driving operational efficiency and competitive differentiation.
Expansion of Cloud-Based and SaaS Deployment
Cloud-based policy administration systems offer scalability, faster implementation, and lower total cost of ownership, making them attractive to insurers seeking to support digital policy servicing and remote operations. The shift to SaaS models enables continuous updates, regulatory compliance, and modular adoption, accelerating market growth.
Demand for Product Personalization and Faster Time-to-Market
Customers increasingly expect personalized life insurance products with flexible coverage and dynamic premium structures. Advanced policy administration systems allow insurers to rapidly configure, test, and launch new products, reducing time-to-market and supporting higher customer engagement and retention.
Growth of Digital Distribution and Direct-to-Consumer Channels
The proliferation of online portals, mobile apps, and digital agents requires seamless integration with core policy administration systems for real-time underwriting, instant policy issuance, and automated billing. This trend drives demand for robust, API-enabled platforms that can efficiently scale policy processing and servicing.
Regulatory Complexity and Compliance Requirements
Evolving data protection laws, solvency regulations, and cross-border compliance needs are pushing insurers to adopt flexible, audit-ready policy administration systems. The ability to rapidly adapt to regulatory changes and ensure data security is a key driver for system upgrades and new deployments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Life Insurance Policy Administration System market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Life Insurance Policy Administration System market projected to grow between 2024 and 2032?
What Features Are Typically Included in a Life Insurance PAS?
Is a life insurance PAS suitable for different types of insurance products?
Which Life Insurance Policy Administration System market segment held the largest share in 2024?
Who are the leading companies in the Life Insurance Policy Administration System market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Individual Life Insurance
- 1.2.2 Group Life Insurance
- 1.3 By Deployment
- 1.3.1 Single-Tenant
- 1.3.2 Multi-Tenant
- 1.4 By Technology
- 1.4.1 Cloud-Based
- 1.4.2 On-Premise
- 1.4.3 Hybrid
- 1.5 By Application
- 1.5.1 New Business Processing
- 1.5.2 Underwriting
- 1.5.3 Policy Administration
- 1.5.4 Claims Management
- 1.5.5 Billing and Accounting
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,288 million → 2032: USD 15,347.34 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Life Insurance Policy Administration System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Life Insurance Policy Administration System Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Life Insurance Policy Administration System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Life Insurance Policy Administration System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Life Insurance Policy Administration System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Life Insurance Policy Administration System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Life Insurance Policy Administration System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Life Insurance Policy Administration System Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,288 million → 2032: USD 15,347.34 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Life Insurance Policy Administration System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Individual Life Insurance
- 12.3.6.2 Group Life Insurance
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Deployment - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Single-Tenant
- 12.4.6.2 Multi-Tenant
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Cloud-Based
- 12.5.6.2 On-Premise
- 12.5.6.3 Hybrid
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 New Business Processing
- 12.6.6.2 Underwriting
- 12.6.6.3 Policy Administration
- 12.6.6.4 Claims Management
- 12.6.6.5 Billing and Accounting
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Life Insurance Policy Administration System End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Life Insurance Policy Administration System Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Life Insurance Policy Administration System Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Life Insurance Policy Administration System Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Majesco
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Oracle
- 18.4 Accenture
- 18.5 Infosys
- 18.6 EIS Group
- 18.7 Insurity
- 18.8 EXL
- 18.9 FAST Technology
- 18.10 Edlund
- 18.11 Accenture Life Insurance Solutions Group
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

