
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Oilseed Market Size 2024 | USD 305.1 Million |
| Oilseed Market, CAGR | 5% |
| Oilseed Market Size 2032 | USD 450.8 Million |
Market Overview:
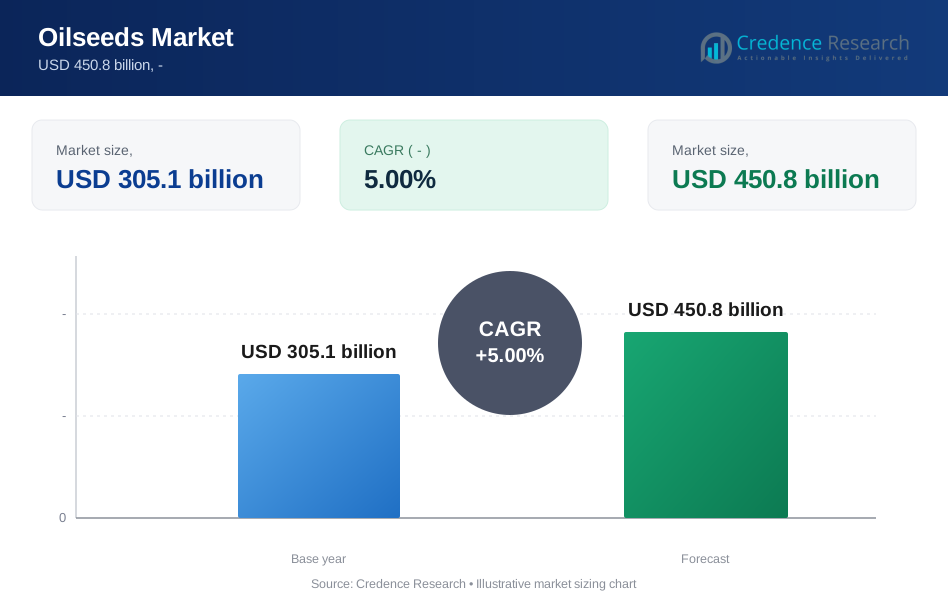
The Oilseed Market is experiencing significant growth, driven by increasing demand for oilseeds in various industries, including food, feed, and biofuels. As of 2024, the global Oilseed Market is valued at approximately USD 305.1 billion and is projected to grow at a compound annual growth rate (CAGR) of 5% over the forecast period, reaching approximately USD 450.8 billion by 2032. This growth reflects the rising global consumption of oilseeds and their derivatives, which are essential in producing vegetable oils, animal feed, and biofuel components.
Several key factors are contributing to the market's expansion. The growing global population and increasing disposable incomes are driving up the demand for edible oils and animal proteins, which in turn fuels the need for oilseeds. Additionally, advancements in agricultural technologies and practices are improving oilseed yields and quality, further supporting market growth. Government policies promoting the use of biofuels as part of sustainable energy initiatives are also playing a crucial role in boosting demand for oilseeds.
Regionally, North America holds a significant share of the Oilseed Market, driven by advanced agricultural practices and high production volumes in countries like the United States and Canada. The South American region, particularly Brazil and Argentina, is also a major player, with large-scale oilseed cultivation and exports. The Asia-Pacific region is expected to witness substantial growth during the forecast period, due to increasing demand for oilseeds in emerging economies like China and India, which are expanding their agricultural sectors and improving their oilseed processing capabilities.
Market Drivers:
Increasing Global Demand for Edible Oils:
The rising global demand for edible oils is a significant driver of growth in the Oilseed Market. As global populations expand and disposable incomes increase, especially in developing regions, the consumption of vegetable oils is surging. For Instance, according to the Food and Agriculture Organization (FAO), this demand is driven by changing dietary patterns and the increased use of oilseeds in food products and cooking oils. Additionally, reports from the International Monetary Fund (IMF) indicate that economic growth in emerging markets, such as those in Asia-Pacific and Latin America, is contributing to higher oilseed consumption. The expansion of the middle class in countries like China and India is particularly influential, as it boosts the demand for a variety of oilseed products and processed foods.
Growth in Biofuel Production:
The growth in biofuel production is another major driver of the Oilseed Market. Governments worldwide are increasingly investing in and promoting the use of biofuels as part of their sustainable energy initiatives. For Instance, The World Bank reports that policies and incentives aimed at reducing greenhouse gas emissions and dependence on fossil fuels are boosting the demand for biofuel crops, including oilseeds. Countries such as the United States and Brazil are at the forefront, implementing biofuel mandates and subsidies to encourage the use of renewable energy sources. This trend is driving substantial investment in oilseed cultivation and processing infrastructure to meet biofuel requirements.
Technological Advancements in Agriculture:
Technological advancements in agriculture significantly contribute to the growth of the Oilseed Market. Innovations such as genetically modified (GM) crops, precision farming, and advanced breeding techniques enhance oilseed yields and resilience. For Instance, The U.S. Department of Agriculture (USDA) highlights that the adoption of these technologies is leading to higher production efficiency and better-quality oilseeds. Furthermore, research and development efforts by governmental and research institutions are continually improving oilseed varieties to be more resistant to pests, diseases, and environmental stresses. These advancements help meet the increasing demand for oilseeds and reduce production costs.
Supportive Government Policies and Subsidies:
Supportive government policies and subsidies play a crucial role in driving the Oilseed Market. Many governments offer financial incentives and subsidies to farmers for growing oilseeds and investing in oilseed processing infrastructure. For instance, the European Union’s Common Agricultural Policy (CAP) provides support to oilseed farmers and promotes sustainable farming practices. Similarly, the Indian government’s National Mission on Oilseeds and Oil Palm aims to boost domestic production through various subsidies and support programs. These policies not only enhance production capacity but also ensure a stable supply of oilseeds to meet domestic and global demands. the Oilseed Market is propelled by increasing global demand for edible oils, growth in biofuel production, technological advancements in agriculture, and supportive government policies. These factors collectively drive market expansion and support the development of oilseed cultivation and processing, catering to the evolving needs of consumers and industries worldwide.
Market Trends:
Shift Towards Sustainable and Organic Farming:
A prominent trend in the Oilseed Market is the shift towards sustainable and organic farming practices. As environmental concerns grow and consumers demand eco-friendly products, there is a notable increase in the cultivation of organically produced oilseeds. The Indian Ministry of Agriculture and Farmers' Welfare reports that the government is actively promoting organic farming through various schemes and incentives, reflecting a broader global movement towards sustainable agriculture. For Instance, The European Union’s Green Deal further supports this trend by setting ambitious targets to reduce the environmental impact of farming and increase the area under organic farming. Sustainable practices not only align with regulatory frameworks but also meet the rising consumer preference for environmentally responsible products. The promotion of organic oilseeds is expected to enhance soil health, reduce chemical inputs, and lower the overall environmental footprint of oilseed production.
Expansion of Plant-Based Food Products:
The expansion of plant-based food products is another significant trend influencing the Oilseed Market. The global shift towards plant-based diets is driven by health concerns, environmental sustainability, and ethical considerations. For Instance, according to the U.S. Department of Agriculture (USDA), there is a growing demand for oilseeds in the production of plant-based food alternatives, including meat substitutes and dairy-free products. This trend is supported by research from the World Resources Institute (WRI), which highlights the environmental benefits of plant-based diets compared to traditional animal-based foods. The Indian government’s National Mission on Oilseeds and Oil Palm is also focusing on enhancing oilseed production to meet the growing demand from plant-based food industries. The expansion of plant-based foods is leading to increased investments in R&D for improving the quality and functionality of oilseed-based ingredients, driving innovation and growth in the oilseed sector. the Oilseed Market is being shaped by a significant shift towards sustainable and organic farming practices, supported by initiatives from the Indian government and the EU. Additionally, the rising popularity of plant-based foods is creating new opportunities and driving advancements in oilseed production and processing. These trends are reflective of broader global movements towards sustainability and health-conscious consumer choices.
Market Challenge Analysis:
Regulatory and Compliance Challenges:
The Oilseed Market faces significant regulatory and compliance challenges that impact production and trade. Different regions have varying regulations regarding genetically modified organisms (GMOs) and pesticide use, which can complicate the production and distribution of oilseeds. For instance, the European Union has stringent regulations on GMOs and pesticide residues, which can limit market access for oilseed products that do not meet these standards. Compliance with these diverse regulations requires substantial investment in testing, certification, and adaptation of farming practices. According to reports from the Food and Agriculture Organization (FAO), navigating these complex regulatory landscapes can be particularly challenging for producers aiming to access international markets. Additionally, the evolving nature of regulatory frameworks necessitates ongoing vigilance and adaptation, which can increase operational costs and impact market stability.
Environmental and Sustainability Concerns:
Environmental and sustainability concerns also pose significant challenges to the Oilseed Market. The cultivation of oilseeds can lead to deforestation, soil degradation, and water depletion, particularly when large-scale monocultures are employed. The World Bank highlights that addressing these environmental impacts requires implementing sustainable farming practices and managing resources more effectively. Consumers and governments are increasingly demanding environmentally responsible production methods, which pressures producers to adopt practices that mitigate environmental harm. This includes investing in sustainable agriculture techniques, such as crop rotation and integrated pest management, to reduce the ecological footprint of oilseed production. Balancing the need for increased production with environmental stewardship presents a complex challenge for the industry, necessitating innovation and commitment to sustainable practices.
Market Segmentation Analysis:
By Type
The Oilseed Market is segmented by type into Soybeans, Sunflower Seeds, Canola Seeds, Cotton Seeds, and Others. Soybeans are the largest segment, widely used for oil extraction and animal feed. Sunflower seeds are also significant, valued for their high oil content and versatility. Canola seeds, known for their low saturated fat content, are increasingly popular in cooking oils. Cotton seeds, primarily used for oil and as animal feed, contribute notably to the market. The "Others" category includes various oilseeds such as safflower and flaxseeds, catering to specific regional and industrial needs.
By Technology
The technology segment in the Oilseed Market includes Conventional Farming Techniques, Genetically Modified (GM) Seeds, Precision Agriculture Technologies, and Advanced Processing Technologies. Conventional farming remains prevalent, involving traditional practices for oilseed cultivation. Genetically modified seeds offer enhanced traits such as pest resistance and higher yields, which are driving their adoption. Precision agriculture technologies use data and analytics to optimize crop management and improve efficiency. Advanced processing technologies focus on enhancing the extraction and refining processes of oilseeds, leading to better product quality and reduced waste.
By End-User
The Oilseed Market is categorized by end-users into Food and Beverage Industry, Animal Feed Industry, Biofuels Industry, and Industrial Applications. The Food and Beverage Industry is a major consumer, utilizing oilseeds for cooking oils, margarine, and other food products. The Animal Feed Industry relies on oilseeds for nutritious feed components. The Biofuels Industry uses oilseeds to produce biodiesel and other renewable energy sources. Industrial Applications include the use of oilseeds in various non-food products, such as lubricants, plastics, and pharmaceuticals. Each end-user segment influences the demand and application of different oilseed types and technologies.
Segmentation:
Based on Product Type:
- Soybeans
- Sunflower Seeds
- Canola Seeds
- Cotton Seeds
- Other Oilseeds
Based on Technology:
- Conventional Farming Techniques
- Genetically Modified (GM) Seeds
- Precision Agriculture Technologies
- Advanced Processing Technologies
Based on End-User:
- Food and Beverage Industry
- Animal Feed Industry
- Biofuels Industry
- Industrial Applications
Based on Region:
- North America (United States, Canada, Mexico)
- Europe (Germany, France, United Kingdom, Italy, Spain)
- Asia-Pacific (China, India, Japan, Australia, South Korea)
- Latin America (Brazil, Argentina, Chile, Peru)
- Middle East & Africa (Saudi Arabia, South Africa, Egypt, United Arab Emirates)
Regional Analysis:
North America
North America holds a significant share of the global Oilseed Market, with the United States and Canada being the primary contributors. As of 2024, North America accounts for approximately 30% of the global market share. The United States is a leading producer and exporter of soybeans, which are crucial for both domestic use and international trade. The country’s advanced agricultural technologies, including precision farming and genetically modified seeds, enhance productivity and efficiency. Canada is also a major player, particularly in the production of canola seeds, which are in high demand for their oil content. Government policies and subsidies in both countries support oilseed production and processing, further solidifying North America's strong market position. Additionally, trade agreements such as the USMCA (United States-Mexico-Canada Agreement) facilitate cross-border trade, contributing to the region's market dominance.
Europe
Europe, with a market share of approximately 25%, is a significant player in the global Oilseed Market. Major producers include France, Germany, and Ukraine, with France being the largest producer of sunflower seeds in the region. The European Union's Common Agricultural Policy (CAP) plays a crucial role in supporting oilseed farmers through subsidies and sustainability initiatives. The EU’s stringent regulations on genetically modified organisms (GMOs) and pesticide residues impact the market, encouraging the adoption of organic and sustainable farming practices. The focus on environmental sustainability and reduced carbon footprints drives innovation in oilseed production and processing technologies. Additionally, European countries are increasingly investing in biofuel production, which supports the demand for oilseeds used in renewable energy applications.
Asia-Pacific
The Asia-Pacific region is expected to see the most substantial growth in the Oilseed Market, with a current market share of approximately 35%. Key countries in this region include China, India, Japan, and Australia. China is the largest importer of soybeans, primarily due to its significant demand for oilseeds in food products and animal feed. India, with its growing population and increasing meat consumption, is also expanding its oilseed production and processing capabilities. The region is experiencing rapid industrialization and urbanization, which boosts the demand for oilseeds in various applications. Government initiatives in countries like China and India aim to increase domestic oilseed production and reduce dependency on imports. Additionally, technological advancements and investments in agricultural research are expected to drive further growth in this region. The Asia-Pacific market is characterized by a rising middle class and changing dietary patterns, which are anticipated to sustain the demand for oilseeds in the coming years.
Key Player Analysis:
- BASF SE (Germany)
- Monsanto Company (US)
- Groupe Limagrain Holding (France)
- Syngenta (Switzerland)
- DuPont (US)
- Nuziveedu Seeds Ltd (India)
- Land O'Lakes Inc. (US)
- Cargill Incorporated (US)
- Seed Co Limited (South Africa)
- Mahyco Seeds Company Limited (India)
Competitive Analysis:
The Oilseed Market is characterized by a competitive landscape with several major players and a diverse range of smaller companies contributing to market dynamics. Key global players include Cargill, ADM (Archer Daniels Midland), and Bunge Limited, which dominate the market due to their extensive production capabilities, wide distribution networks, and significant investments in technology and innovation. These companies leverage advanced processing technologies and global supply chains to maintain a competitive edge. Regional players, particularly in Asia-Pacific and Latin America, also play a crucial role, contributing to the market's vibrancy and competitiveness. For example, companies such as Wilmar International in Asia and Louis Dreyfus Company in Latin America are significant regional influencers. The competitive environment is further shaped by ongoing technological advancements, including developments in genetically modified seeds and precision agriculture, which enhance yield and efficiency. Additionally, government policies and regulations, such as subsidies for sustainable farming and biofuel mandates, impact competition by influencing production costs and market access. Overall, the Oilseed Market is dynamic, with competition driven by technological innovation, regional demand, and regulatory frameworks, leading to a continually evolving landscape where companies must adapt to stay ahead.
Recent Developments:
- In October 2022, India-based agrochemical company Crystal Crop Protection Ltd acquired Bayer AG's seeds division for an undisclosed amount. This acquisition includes hybrid grain sorghum, cotton, mustard, and pearl millet seeds. Crystal Crop aims to position itself among the leading corporations in the seed industry with this purchase. Additionally, the acquisition is set to strengthen its field crop seed business and transform it into a major integrated Agri-Input player.
Market Concentration & Characteristics:
The Oilseed Market exhibits a moderate to high level of concentration, dominated by a few major multinational corporations alongside several influential regional players. The market is primarily led by global giants such as Cargill, ADM (Archer Daniels Midland), and Bunge Limited, which collectively hold a substantial share due to their extensive production capabilities, advanced technology, and well-established supply chains. These major players benefit from economies of scale and significant capital investments in infrastructure, allowing them to control a significant portion of the market and influence global pricing and trade dynamics. Alongside these global leaders, regional firms like Wilmar International in Asia and Louis Dreyfus Company in Latin America play critical roles in their respective markets, adding to the competitive landscape. The market characteristics include a high degree of vertical integration, where companies often manage the entire supply chain from farming to processing and distribution. This integration enhances efficiency and profitability but also leads to market concentration. Additionally, the Oilseed Market is influenced by fluctuations in commodity prices, government policies, and environmental regulations, which can impact production costs and market dynamics. Technological advancements in seed genetics and processing techniques are driving innovation and competitiveness, while sustainability concerns and regulatory requirements shape market strategies and operations. Overall, the Oilseed Market is characterized by a balance of concentration among large players and competitive dynamics driven by technological and regulatory factors.
Report Coverage:
This report provides a comprehensive analysis of the global Oilseed Market, encompassing various facets of the industry to deliver a detailed overview of current trends, opportunities, and challenges. It covers market dynamics, including key drivers and restraints, with insights into technological advancements and regulatory impacts. The report segments the market by type, technology, end-user, and region, offering a granular view of the landscape. Detailed analyses are presented for major regions, including North America, Europe, and Asia-Pacific, highlighting market shares, growth rates, and regional trends. Additionally, the report explores competitive dynamics by profiling major players and assessing market concentration and characteristics. It also includes forecasts and projections for market growth, considering factors such as technological developments, changing consumer preferences, and policy impacts. Data is supported by credible sources, including industry reports, government publications, and market research from reputable organizations. By providing a thorough understanding of the market’s structure and dynamics, this report serves as a valuable resource for stakeholders seeking to make informed decisions and strategize effectively in the evolving Oilseed Market.
Future Outlook:
- The global Oilseed Market is projected to continue expanding at a steady pace, with an anticipated growth over the next decade.
- Demand for oilseeds, particularly soybeans and canola, is expected to rise due to increasing consumption in food products and biofuels.
- Technological advancements in seed genetics and precision agriculture will drive improvements in yield and efficiency.
- The shift towards sustainable and organic farming practices will influence production methods and market dynamics.
- Asia-Pacific will remain a key growth region, with significant increases in demand driven by countries like China and India.
- Government policies and subsidies supporting renewable energy and sustainable agriculture will impact market trends.
- Market concentration is likely to remain high, with major players continuing to dominate through vertical integration and technological investment.
- Emerging economies will play a more prominent role as they enhance their oilseed production capabilities and infrastructure.
- Innovations in oilseed processing technologies will enhance product quality and create new applications.
- Regulatory developments and environmental concerns will shape industry practices, influencing market growth and investment opportunities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Global Demand for Edible Oils
Rising populations and higher disposable incomes, especially in emerging markets, are boosting the consumption of vegetable oils for food and cooking, directly increasing the demand for oilseeds as raw materials.
Growth in Biofuel Production
Government policies and incentives promoting renewable energy are driving up the use of oilseeds for biodiesel and other biofuels, leading to expanded cultivation and processing of oilseed crops.
Technological Advancements in Agriculture
Innovations such as genetically modified seeds, precision farming, and advanced processing technologies are improving oilseed yields, quality, and production efficiency, making oilseed farming more profitable and scalable.
Supportive Government Policies and Subsidies
Subsidies, financial incentives, and supportive policies from governments in major producing regions encourage oilseed cultivation and investment in processing infrastructure, stabilizing supply and supporting market growth.
Expansion of Plant-Based Food Products
The global shift toward plant-based diets is increasing the use of oilseeds in alternative protein products, dairy substitutes, and other plant-based foods, creating new demand streams and driving innovation in oilseed applications.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is driving the growth of the Oilseed Market?
Which regions are leading in oilseed production?
How do technological advancements impact the Oilseed Market?
What are the main challenges facing the Oilseed Market?
How are sustainability trends affecting the Oilseed Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Food and Beverage Industry
- 1.2.2 Animal Feed Industry
- 1.2.3 Biofuels Industry
- 1.2.4 Industrial Applications
- 1.3 By Technology
- 1.3.1 Conventional Farming Techniques
- 1.3.2 Genetically Modified (GM) Seeds
- 1.3.3 Precision Agriculture Technologies
- 1.3.4 Advanced Processing Technologies
- 1.4 By Product Type
- 1.4.1 Soybeans
- 1.4.2 Sunflower Seeds
- 1.4.3 Canola Seeds
- 1.4.4 Cotton Seeds
- 1.4.5 Other Oilseeds
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2032: USD 305.1 billion → Forecast year: USD 450.8 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2032
- 3.3 Forecast Market Size
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Oilseeds Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Oilseeds Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Oilseeds Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Oilseeds Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Oilseeds Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Oilseeds Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Oilseeds Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Oilseeds Market Outlook
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2032: USD 305.1 billion → Forecast year: USD 450.8 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2032
- 11.2 Market Forecast
- 11.2.1 Revenue Forecast
- 11.2.2 Volume Forecast
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Oilseeds Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2032
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast
- 12.3.4 Volume Forecast
- 12.3.5 Base-Year Market Share, 2032
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Food and Beverage Industry
- 12.3.7.2 Animal Feed Industry
- 12.3.7.3 Biofuels Industry
- 12.3.7.4 Industrial Applications
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast
- 12.4.4 Volume Forecast
- 12.4.5 Base-Year Market Share, 2032
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Conventional Farming Techniques
- 12.4.7.2 Genetically Modified (GM) Seeds
- 12.4.7.3 Precision Agriculture Technologies
- 12.4.7.4 Advanced Processing Technologies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast
- 12.5.4 Volume Forecast
- 12.5.5 Base-Year Market Share, 2032
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Soybeans
- 12.5.7.2 Sunflower Seeds
- 12.5.7.3 Canola Seeds
- 12.5.7.4 Cotton Seeds
- 12.5.7.5 Other Oilseeds
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Oilseeds End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Oilseeds Geographic Market Outlook
- 14.1 Regional Market Size and Share, 2032
- 14.2 Regional Market Forecast
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Oilseeds Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Oilseeds Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2032
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Cargill Incorporated
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Archer Daniels Midland (ADM)
- 18.4 Bunge Limited
- 18.5 Wilmar International
- 18.6 Louis Dreyfus Company
- 18.7 BASF SE
- 18.8 Syngenta
- 18.9 Monsanto Company
- 18.10 DuPont
- 18.11 Groupe Limagrain Holding
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

