
Market Overview:
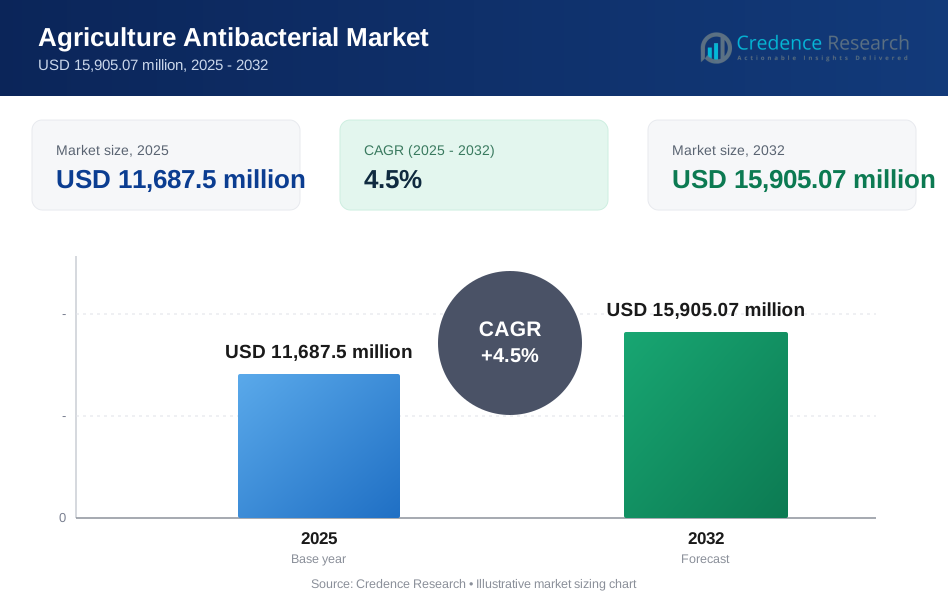
The Agricultural Antibacterials Market is projected to grow from USD 11,687.5 million in 2025 to an estimated USD 15,905.07 million by 2032, with a compound annual growth rate (CAGR) of 4.5% from 2025 to 2032.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2022 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Agriculture Antibacterial Market Size 2025 | USD 11,687.5 million |
| Agriculture Antibacterial Market, CAGR | 4.5% |
| Agriculture Antibacterial Market Size 2032 | USD 15,905.07 million |
Market drivers strengthen as growers seek tools that protect crops under shifting climate patterns and tighter residue rules. Rising bacterial resistance pushes farms to adopt new formulations that offer reliable control across multiple stages of crop growth. Biologicals gain momentum because farmers want safer options that support sustainable practices. Precision spraying, improved soil treatments, and enhanced seed applications expand usage across diversified farms. Higher quality standards from export markets also reinforce demand for effective antibacterial products.
Regional growth varies based on crop diversity, climate conditions, and adoption behavior. Asia Pacific leads due to high planting intensity and broad use across cereals, vegetables, and fruit crops. North America maintains strong demand through advanced farming systems and early adoption of improved formulations. Europe expands use of biological and copper-based solutions due to strict environmental rules. Latin America and the Middle East & Africa emerge as developing markets as farmers increase antibacterial use to protect export-driven crops and manage rising disease outbreaks.

Market Insights:
- The Agricultural Antibacterials Market is projected to rise from USD 11,687.5 million in 2025 to USD 15,905.07 million by 2032, supported by a 4.5% CAGR through the forecast period.
- Growing disease pressure, climate variability, and strict residue standards strengthen demand for advanced antibacterial tools across major crop groups.
- Rising resistance concerns and regulatory limits on certain chemistries create restraints that push growers toward safer and more efficient alternatives.
- Asia Pacific leads market adoption due to intensive cropping cycles, while North America and Europe grow through strong technology uptake and sustainability-driven product choices.
- Emerging regions such as Latin America and the Middle East & Africa increase usage as export crops expand and farms adopt preventive antibacterial programs.
Market Drivers
Rising Pressure To Protect Crop Quality And Reduce Bacterial Losses
The Agricultural Antibacterials Market grows due to rising pressure on farms to protect crop health. Farmers face severe yield loss when bacteria spread fast across fields. Climate shifts increase warm and humid conditions that favor bacterial growth. New bacterial strains challenge existing treatments and demand constant upgrades. Growers look for solutions that keep plants healthy through each growth stage. Strong demand comes from high-value crops that cannot afford disease-driven waste. Governments support safer farm practices that reduce harmful residues. This support raises adoption of trusted antibacterial tools across farms.
- For instance, Syngenta AG reported that its Orondis technology reduced disease severity by up to 75% in field trials, strengthening control programs for sensitive crops.
Expanding Use Of Advanced Antibacterial Modes With Higher Field Efficiency
New antibacterial modes support stronger field performance for the Agricultural Antibacterials Market. Modern formulas act faster on leaf surfaces and soil zones. These tools help farmers stop early infections before they move deeper into plant tissue. Stronger root protection helps crops stay firm during stress periods. Many growers choose products that combine fast action with longer soil persistence. These combinations help reduce frequent field visits and labor needs. Improved spray systems deliver even coverage across wide farms. This shift boosts interest in new antibacterial categories.
- For instance, trials from Corteva Agriscience showed that its targeted Zorvec active ingredient delivered up to 10-day residual control, raising efficiency in high-pressure conditions.
Greater Adoption Driven By Food Safety Rules And Export Compliance
Food safety rules raise the need for better disease control within the Agricultural Antibacterials Market. Exporting nations must meet strict quality standards for fruits and vegetables. Bacterial spots or blights raise rejection risks at checkpoints. Farmers respond by using stronger and cleaner antibacterial options. These tools help maintain shelf life during long transport cycles. Retailers also demand cleaner produce with fewer visible defects. Higher safety checks across supply chains push farmers to upgrade plant protection plans. These actions support steady growth across all farm sizes.
Growing Demand For Sustainable And Low-Residue Crop Protection Choices
Sustainable farming drives new product demand within the Agricultural Antibacterials Market. Growers look for options that support soil health and reduce heavy chemical load. Research teams work on antibacterial molecules that break down safely. Many farms shift to low-residue products to meet clean-label rules. These tools help protect plants without hurting helpful soil microbes. Better residue profiles support organic-leaning production plans. Increased training helps growers adopt responsible spray cycles. This shift builds long-term trust in newer antibacterial solutions.
Market Trends
Shift Toward Multi-Target Antibacterials With Wider Crop Coverage
The Agricultural Antibacterials Market sees growth in multi-target solutions that act on several bacterial groups. These options reduce crop loss linked to complex mixed infections. Wider coverage helps farmers protect diverse fields with fewer product types. Stronger leaf adhesion keeps sprays active through rain events. New blends improve both preventive and curative actions. Farmers choose versatile tools for large farms with mixed crops. Wider use reduces product storage needs on farms. This trend continues as growers seek simpler disease plans.
Rising Role Of Biological Antibacterial Products In Modern Farm Systems
Biological tools gain momentum within the Agricultural Antibacterials Market due to natural strain activity. Microbial products help block bacterial entry at plant surfaces. Many farmers choose them to support chemical reduction goals. These solutions help protect fruit crops that need softer treatments. Strong field trials build trust among growers who test biological tools. Bio-based sprays reduce resistance buildup in target bacteria. They also blend well with integrated pest programs. This shift expands choices across open-field and greenhouse farms.
- For instance, AMVAC’s distribution of BellaTrove® Companion Maxx® utilizes the Bacillus amyloliquefaciensstrain ENV603, which is EPA-registered to suppress over 25 different plant pathogens while establishing a 24-hour protective biofilm on the root and leaf surfaces.
Faster Adoption Of Precision-Based Spray And Application Technologies
Digital tools change application methods in the Agricultural Antibacterials Market. Smart sprayers use sensors to detect plant stress early. These systems guide growers to spray only affected zones. Focused application lowers waste and reduces product cost. Drones help reach large farms with uniform spray patterns. GPS-guided tools cut overlap during each pass. Better accuracy raises treatment success during early infection windows. This upgrade supports more reliable disease control.
- For instance, DJI Agriculture’s Agras T50 drone system utilizes a dual-atomization spraying mechanism to achieve a flow rate of 16 litres per minute, providing uniform droplet coverage across 21 hectares per hour while reducing chemical drift by 20% compared to traditional ground-based boom sprayers.
Growing Interest In Resistance-Management Programs Supported By New Rotation Plans
Resistance concerns shape new practices in the Agricultural Antibacterials Market. Farmers use rotation plans to slow resistance in bacteria. These plans mix chemical and biological tools through the season. Better training helps growers choose correct treatment windows. Rotation lowers the risk of losing key antibacterial products. Strong extension programs teach farmers how to track resistance markers. Many buyers now ask suppliers for rotation-ready antibacterial packs. This trend supports responsible long-term field management.
Market Segmentation Analysis:
By Product Type
The Agricultural Antibacterials Market expands through strong demand for antibiotics, antiseptics, and broad-use bactericides that support fast field action. Copper-based options hold steady use due to their wide disease coverage and easy field handling. Dithiocarbamates gain traction in large-acre crops where farmers seek preventive protection. Amides such as oxytetracycline serve targeted needs in fruit and vegetable systems. Biologicals and nano copper tools grow fast because many growers look for safer field profiles. Each product type supports disease control programs with different strengths that fit crop value, climate shifts, and residue rules.
- For instance, Nufarm’s Champ® WG utilizes a refined copper hydroxide formulation with a surface area of 30,000 square centimetres per gram, providing a high density of copper ions that achieve 98% control of bacterial speck in tomato field trials while requiring 25% less metallic copper per hectare than traditional powders.
By Crop Type
The Agricultural Antibacterials Market gains scale through high use in cereals, grains, and oilseeds where growers need strong protection against seedling and foliar infections. Fruits and vegetables use targeted solutions that help reduce visible defects. Commercial crops such as tobacco depend on stable protection during long production cycles. Turf and ornamentals use softer tools that maintain plant appearance. Greenhouse crops adopt precise treatments that support controlled environments. Each crop group drives unique product needs shaped by disease pressure and market quality demands.
By Form
The Agricultural Antibacterials Market benefits from liquid forms that support fast mixing and broad spray coverage. Liquid-dispersible granules offer cleaner handling and steady adoption across large farms. Wettable powders remain common where growers seek cost-effective options. Dust formats serve niche needs in crops that require dry application on sensitive surfaces. Each form supports diverse field methods and aligns with local spray habits.
- For instance, Bayer CropScience’s Serenade® ASO (Aqueous Suspension-Organic) is a liquid formulation containing Bacillus amyloliquefaciens strain QST 713 at a concentration of 1.0 x 10^9 CFU/g, which maintains a 2-year shelf life at 20°C and ensures 100% solubility in standard spray tanks to prevent nozzle clogging.
By Application / Mode
The Agricultural Antibacterials Market grows through strong use of foliar sprays that help stop early leaf infections. Soil treatments protect roots during early growth stages. Seed and transplant treatments help farmers reduce early-season disease loss. Soil injection supports deeper application in high-value crops. Drip-irrigation injection raises efficiency in water-managed systems. Post-harvest treatments help maintain quality during storage and transport. Each mode supports targeted deployment across varied farm systems.
Segmentation:
By Product Type
- Antibiotics
- Antiseptics
- Bactericides
- Copper-Based Antibacterials (copper hydroxide, copper oxychloride)
- Dithiocarbamates (mancozeb, maneb)
- Amides (oxytetracycline)
- Others (biologicals, nano copper)
By Crop Type
- Cereals & Grains (rice, wheat, corn)
- Oilseeds & Pulses (soybean, cotton)
- Fruits & Vegetables (citrus, tomatoes)
- Commercial Crops (tobacco)
- Turf & Ornamentals
- Greenhouse Crops
By Form
- Liquid
- Liquid-Dispersible Granules
- Wettable Powder
- Dust (Dry Flowable)
By Application / Mode
- Foliar Spray
- Soil Treatment
- Seed / Transplant Treatment
- Soil Injection
- Water-System / Drip-Irrigation Injection
- Post-Harvest Treatment
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America holds around 28% share of the Agricultural Antibacterials Market due to strong commercial farming, strict disease-control standards, and high use of copper-based and biological tools. Farmers in the United States adopt advanced sprays that support large-acre crops. Canada sees steady interest in low-residue options that align with export rules. Strong distribution networks help maintain consistent product reach across wide farm zones. Research bodies in the region help test new formulations. The region continues to influence global product design through strong regulatory alignment.
Europe accounts for nearly 25% share of the Agricultural Antibacterials Market, supported by high adoption of sustainable and bio-based solutions. It pushes strict residue limits that guide product selection. Growers depend on copper and biologicals for fruits, vegetables, and greenhouse crops. Southern Europe uses strong bactericides to limit disease pressure in citrus and tomato systems. Northern Europe prefers precise low-dose applications for controlled environments. The region drives strong demand for products that support eco-friendly farming standards.
Asia Pacific leads with nearly 35% share of the Agricultural Antibacterials Market due to high crop intensity and strong demand for preventive sprays. It supports diverse needs across rice, wheat, fruits, and vegetables. China and India drive strong consumption through large farming communities that seek cost-effective solutions. Southeast Asia depends on copper-based and dithiocarbamate products to handle humidity-driven outbreaks. Australia adopts advanced formulations for high-value crops. Latin America and Middle East & Africa share the remaining 12%, supported by citrus, soybean, greenhouse, and specialty crops.
Key Player Analysis:
- Bayer AG
- Syngenta AG
- Corteva Agriscience
- BASF SE
- FMC Corporation
- Nufarm Limited
- Adama Agricultural Solutions Ltd.
- Sumitomo Chemical Co.
- UPL Limited
- Nippon Soda Co.
Competitive Analysis:
The Agricultural Antibacterials Market features strong competition driven by global suppliers and regional players. It supports firms that offer wide portfolios covering copper compounds, biologicals, and synthetic molecules. Global companies invest in resistance-management tools that protect long-term product use. Regional manufacturers expand reach through cost-effective wettable powders and liquid forms. Many suppliers push research into biologicals to meet strict residue rules. Strategic alliances help firms improve distribution networks and crop-specific solutions. Leading brands strengthen training programs to support responsible field use and drive long-term customer loyalty.
Recent Developments:
- In April 2025, Koppert launched the next development phase of its AI-powered Digital Assistant, providing growers with continuous access to solutions for crop protection challenges, including bacterial diseases.
- In January 2025, AMVAC signed a regional distribution agreement with DPH Biologicals to expand its GreenSolutions portfolio with BellaTrove Companion Maxx, enhancing biocontrol options for U.S. specialty crop growers.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Crop Type, Form, and Application / Mode. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growth accelerates as farmers adopt wider antibacterial options that support disease control in high-pressure climates.
- Demand strengthens through rising focus on residue-safe tools that meet export rules and retail quality standards.
- Biological antibacterials gain wider use because growers seek safer profiles that align with sustainability mandates.
- Digital spray systems improve adoption by supporting precise field coverage and reducing product waste.
- New copper and nano-based innovations appear as companies work on stronger stability and improved uptake.
- High-value fruit and vegetable segments drive steady demand due to strict appearance and shelf-life needs.
- Large-acre crops remain key users as farmers rely on preventive action to protect yield under shifting weather cycles.
- Greenhouse systems adopt advanced formulations that support controlled environments with predictable performance.
- More companies invest in resistance-management programs that protect long-term product effectiveness.
- Regional expansion increases as suppliers strengthen distribution networks to reach emerging farming markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Agricultural Antibacterials Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Agricultural Antibacterials Market projected to grow between 2025 and 2032?
Which Agricultural Antibacterials Market segment held the largest share in 2025?
What are the primary factors fueling the growth of the Agricultural Antibacterials Market?
Who are the leading companies in the Agricultural Antibacterials Market?
Which region commanded the largest share of the Agricultural Antibacterials Market in 2025?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Agriculture Antibacterial Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2025; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Agriculture Antibacterial Market Snapshot
- 2.1.1 Market Size – Historical (2025) & Forecast (2025-2032) (2025: USD 11,687.5 million → 2032: USD 15,905.07 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Agriculture Antibacterial Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2025 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2025
- 2.3.2 Top 10 Players by Volume Share – 2025
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Agriculture Antibacterial Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Agriculture Antibacterial Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Agriculture Antibacterial Market Drivers
- 3.3 Agriculture Antibacterial Market Restraints & Challenges
- 3.4 Agriculture Antibacterial Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Agriculture Antibacterial Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Agriculture Antibacterial Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Agriculture Antibacterial category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Agriculture Antibacterial Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Agriculture Antibacterial Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2025)
- 5.1.2 Global Export Volume by Country (2025)
- 5.1.3 Global Import Value by Country (2025)
- 5.1.4 Global Import Volume by Country (2025)
- 5.1.5 Net Trade Balance by Country (2025)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2025)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Agriculture Antibacterial market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Agriculture Antibacterial Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2025
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Agriculture Antibacterial Market Share Analysis – 2025
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2025)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Agriculture Antibacterial Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Agriculture Antibacterial (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Agriculture Antibacterial Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Agriculture Antibacterial Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2025 & 2032)
- 7.1.2 Channel Mix Evolution (2025-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Agriculture Antibacterial Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Agriculture Antibacterial Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Agriculture Antibacterial Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Agriculture Antibacterial Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Agriculture Antibacterial Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Agriculture Antibacterial Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Agriculture Antibacterial Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
