
Payroll and HR Solutions and Services Market Overview:
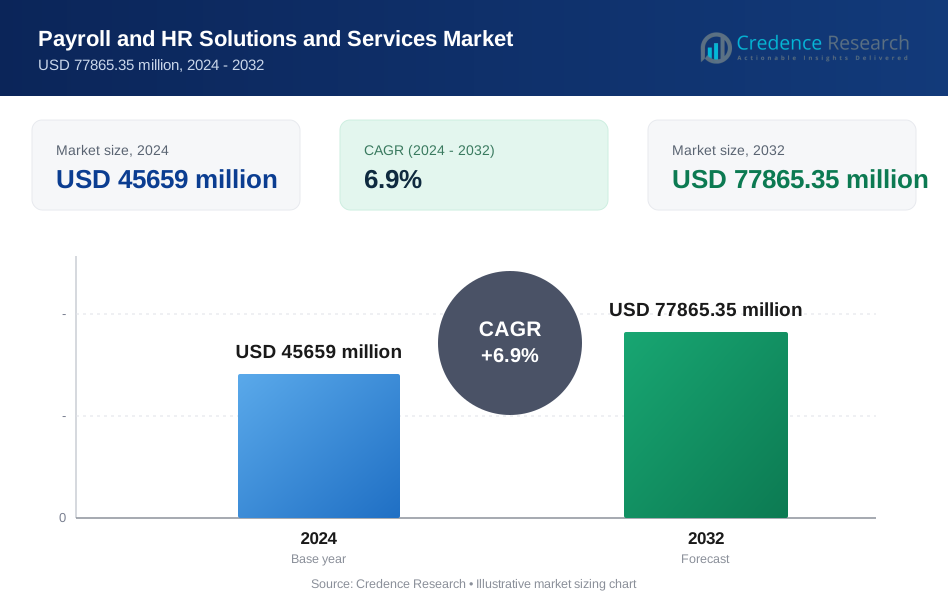
The payroll and HR solutions and services market was valued at USD 45659 million in 2024 and is projected to reach USD 77865.35 million by 2032, growing at a CAGR of 6.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Payroll and HR Solutions and Services Market Size 2024 | USD 45659 million |
| Payroll and HR Solutions and Services Market, CAGR | 6.9% |
| Payroll and HR Solutions and Services Market Size 2032 | USD 77865.35 million |
Payroll and HR Solutions and Services Market Insights
- Market growth is driven by workforce digitization, automation needs, and rising compliance complexity, with software leading the component segment at a market share of 61.8%.
- Key trends include cloud adoption, integrated HR platforms, and analytics-led workforce management, while cloud-based deployment dominates with a market share of 72.4%.
- Competitive intensity remains high as vendors focus on automation, compliance coverage, and scalable platforms, while data security risks and legacy system integration act as key restraints.
- North America leads with a market share of 37.6%, followed by Europe at 28.9% and Asia Pacific at 22.7%, supported by regulatory demand, enterprise adoption, and SME workforce expansion.

Payroll and HR Solutions and Services Market Segmentation Analysis:
By Component
By component, software dominates the payroll and HR solutions and services market with a market share of 61.8%. Organizations adopt software to automate payroll processing, compliance, and reporting. Integrated modules support time tracking, benefits, and tax management. Automation reduces errors and manual workload. Subscription models improve cost predictability. Analytics and dashboards support workforce decisions. Services follow, driven by implementation, consulting, and compliance support. Software leads due to scalability, recurring value, and continuous feature updates that address regulatory complexity and workforce growth across industries.
- For instance, ADP processes payroll for more than 40 million workers each pay cycle, while Workday supports integrated payroll, time, and benefits operations across more than 60 countries.
By Deployment Mode
By deployment mode, cloud-based solutions lead with a market share of 72.4%. Enterprises favor cloud platforms for scalability, remote access, and faster updates. Cloud deployment lowers infrastructure costs and improves security management. Seamless integrations support HR ecosystems and third-party tools. Rapid deployment benefits distributed workforces. On-premise solutions persist in data-sensitive environments but grow slower. Cloud leadership reflects demand for agility, subscription pricing, and real-time visibility across payroll and HR operations.
- For instance, SAP operates cloud payroll through SAP SuccessFactors for more than 100 million users globally, and Oracle delivers payroll rule updates across over 200 jurisdictions via Oracle Cloud HCM.
By Organization Size
By organization size, small and medium enterprises hold a market share of 56.9%. SMEs adopt HR and payroll tools to standardize processes with limited staff. Easy setup and affordability drive adoption. Compliance automation reduces risk and administrative burden. Cloud tools enable growth without heavy IT investment. Large enterprises follow, driven by complex workforce needs and global payroll. SMEs lead due to volume adoption, cost efficiency, and the need for streamlined people operations.
Key Growth Drivers
Rising Workforce Digitization and Process Automation
Organizations increasingly digitize payroll and HR operations to improve accuracy and efficiency. Manual payroll processing leads to calculation errors, delayed payments, and compliance risks. Automated solutions streamline salary processing, attendance tracking, and statutory reporting. Centralized platforms support real-time access to workforce data. Remote and hybrid work models further increase demand for digital HR systems. Automation reduces administrative workload for HR teams and improves employee experience. Integrated tools also support faster approvals and reporting. This driver continues to push enterprises toward modern payroll and HR platforms to improve productivity and operational control.
- For instance, ADP executes payroll processing for more than 40 million employees globally each pay cycle, enabling automated salary runs, attendance capture, and statutory filings.
Increasing Regulatory Complexity and Compliance Requirements
Payroll and HR regulations grow more complex across regions and industries. Organizations must comply with tax laws, labor regulations, and reporting standards that change frequently. Manual compliance tracking increases the risk of penalties and errors. Payroll and HR solutions automate regulatory updates and ensure accurate calculations. Built-in compliance features support audit readiness and reporting accuracy. Multinational companies require systems that manage country-specific rules. SMEs also adopt compliance-ready platforms to reduce legal risk. Regulatory pressure remains a strong driver for sustained investment in payroll and HR solutions.
- For instance, Oracle maintains payroll compliance coverage across more than 200 global jurisdictions through automated rule libraries and calculation engines.
Growth of Small and Medium Enterprises and Workforce Expansion
SMEs expand rapidly across sectors, increasing the need for structured HR processes. Growing employee numbers require reliable payroll management and record keeping. SMEs prefer scalable solutions that support growth without heavy IT investment. Cloud-based platforms offer affordability and easy deployment. Workforce expansion also increases demand for benefits administration and leave management. Payroll and HR tools help SMEs maintain compliance and operational efficiency. This driver supports strong adoption among emerging businesses seeking standardized people management systems.
Key Trends & Opportunities
Shift Toward Cloud-Based and Integrated HR Platforms
Cloud-based payroll and HR platforms continue to gain preference. Organizations value scalability, remote access, and lower infrastructure costs. Integrated platforms combine payroll, attendance, benefits, and performance management. This reduces reliance on multiple systems. Cloud deployment supports faster updates and compliance changes. Vendors offer modular solutions to meet diverse organizational needs. This trend creates opportunities for platform consolidation and long-term subscriptions. Integrated cloud platforms improve visibility and simplify workforce management across locations.
- For instance, Workday supports unified payroll and human capital management operations for more than 10,000 organizations worldwide on a single cloud platform.
Rising Demand for Analytics and Employee Experience Tools
Organizations focus more on workforce insights and employee engagement. HR analytics help identify trends in retention, productivity, and compensation. Dashboards support data-driven decision-making. Employee self-service portals improve transparency and reduce HR workload. Vendors embed analytics and experience tools into payroll platforms. This trend creates opportunities for advanced reporting and value-added services. Analytics-driven HR solutions support strategic workforce planning and long-term organizational performance.
- For instance, SAP enables real-time people analytics for more than 100 million users through SAP SuccessFactors dashboards and self-service tools.
Key Challenges
Data Security and Privacy Concerns
Payroll and HR platforms store sensitive employee information. Data breaches can cause financial and reputational damage. Organizations demand strong encryption and compliance with data protection laws. Security requirements increase implementation costs. Privacy regulations vary by region, adding complexity. Concerns around data misuse slow adoption in regulated sectors. Vendors must invest continuously in cybersecurity. Managing data protection remains a critical challenge for solution providers and users.
Integration Complexity with Legacy Systems
Many organizations rely on legacy payroll and HR systems. Integrating new solutions with existing infrastructure can be complex. Data migration issues delay deployment. Custom integrations increase costs and implementation time. Lack of standardization affects system compatibility. Organizations require skilled support during transition. This challenge slows adoption, especially in large enterprises with complex IT environments.
Regional Analysis
North America
North America holds a market share of 37.6% in the payroll and HR solutions and services market, driven by early technology adoption and complex regulatory frameworks. Enterprises actively invest in automated payroll and HR platforms to manage compliance, taxation, and large workforces. Cloud-based solutions see strong demand due to remote and hybrid work models. High presence of solution providers supports innovation in analytics and employee experience tools. The United States leads regional adoption due to large enterprise concentration, while Canada supports growth through rising SME digitization and strong focus on workforce compliance and operational efficiency.
Europe
Europe accounts for a market share of 28.9%, supported by strict labor regulations and growing digital transformation initiatives. Organizations adopt payroll and HR solutions to manage country-specific compliance and cross-border workforce operations. Cloud adoption continues to expand among SMEs, while large enterprises invest in integrated platforms. Countries such as Germany, the United Kingdom, and France lead regional demand. Employee data protection and reporting accuracy drive solution selection. Europe’s market growth benefits from regulatory complexity, structured HR practices, and increasing focus on standardized workforce management systems.
Asia Pacific
Asia Pacific holds a market share of 22.7%, reflecting rapid enterprise growth and workforce expansion. Rising SME formation and increasing formal employment drive demand for payroll and HR platforms. Cloud-based solutions attract cost-sensitive businesses seeking scalability. Countries such as China, India, Japan, and Australia contribute significantly. Organizations adopt solutions to manage payroll accuracy, attendance, and compliance. Government initiatives supporting digitalization further boost adoption. Asia Pacific remains a high-growth region due to expanding workforces, regulatory modernization, and increasing awareness of automated HR management benefits.
Rest of the World
The Rest of the World region accounts for a market share of 10.8%, supported by gradual adoption across Latin America, the Middle East, and Africa. Organizations focus on basic payroll automation and compliance management. Latin America shows growing demand due to labor law complexity. The Middle East benefits from enterprise modernization and workforce diversification. Africa remains at an early adoption stage but shows long-term potential. International vendors expand through partnerships. Although smaller in scale, the region offers steady growth driven by digital transformation and improving business formalization.
Payroll and HR Solutions and Services Market Segmentations:
By Component
- Software
- Services
By Deployment Mode
- Cloud-based
- On-premise
By Organization Size
- Small and medium enterprises
- Large enterprises
By End User Industry
- BFSI
- IT and telecom
- Healthcare
- Retail and manufacturing
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis highlights competition led by ADP, Workday, SAP, Oracle, and Paychex. Market leaders compete on platform breadth, compliance depth, and scalability. Vendors emphasize cloud-native architectures to support remote and hybrid workforces. Integrated payroll, HR, and workforce management capabilities drive differentiation. Advanced analytics and automation improve accuracy and decision support. Subscription pricing attracts SMEs, while modular suites serve large enterprises. Global compliance coverage strengthens appeal for multinational clients. Partnerships with benefits, accounting, and ERP providers expand ecosystems. Security certifications and data privacy features influence buying decisions. Mid-sized providers compete through ease of use and faster deployment. Overall competition remains intense, driven by regulatory complexity, workforce digitization, and demand for unified people operations platforms.
Key Player Analysis
Recent Developments
- In November 2025, Workday expanded Workday GO with global payroll integration, partner network support, and AI deployment tools for mid-size firms.
- In November 2025, Workday certified PathosLogos Combosite for Workday Global Payroll Connect, validating integration with third-party payroll tools.
- In October 2025, Workday launched a new AI-powered pay transparency solution to help employers meet EU rules and close pay gaps.
Report Coverage
The research report offers an in-depth analysis based on Component, Deployment Mode, Organization Size, End User Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Payroll and HR Solutions and Services market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Payroll and HR Solutions and Services market projected to grow between 2024 and 2032?
Which Payroll and HR Solutions and Services market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Payroll and HR Solutions and Services market?
Who are the leading companies in the Payroll and HR Solutions and Services market?
Which region commanded the largest share of the Payroll and HR Solutions and Services market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Payroll and HR Solutions and Services Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Payroll and HR Solutions and Services Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 45659 million → 2032: USD 77865.35 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Payroll and HR Solutions and Services Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Payroll and HR Solutions and Services Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Payroll and HR Solutions and Services Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Payroll and HR Solutions and Services Market Drivers
- 3.3 Payroll and HR Solutions and Services Market Restraints & Challenges
- 3.4 Payroll and HR Solutions and Services Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Payroll and HR Solutions and Services Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Payroll and HR Solutions and Services Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Payroll and HR Solutions and Services category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Payroll and HR Solutions and Services Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Payroll and HR Solutions and Services Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Payroll and HR Solutions and Services market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Payroll and HR Solutions and Services Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Payroll and HR Solutions and Services Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Payroll and HR Solutions and Services Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Payroll and HR Solutions and Services (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Payroll and HR Solutions and Services Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Payroll and HR Solutions and Services Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Payroll and HR Solutions and Services Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Payroll and HR Solutions and Services Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Payroll and HR Solutions and Services Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Payroll and HR Solutions and Services Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Payroll and HR Solutions and Services Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Payroll and HR Solutions and Services Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Payroll and HR Solutions and Services Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
