
Market Overview
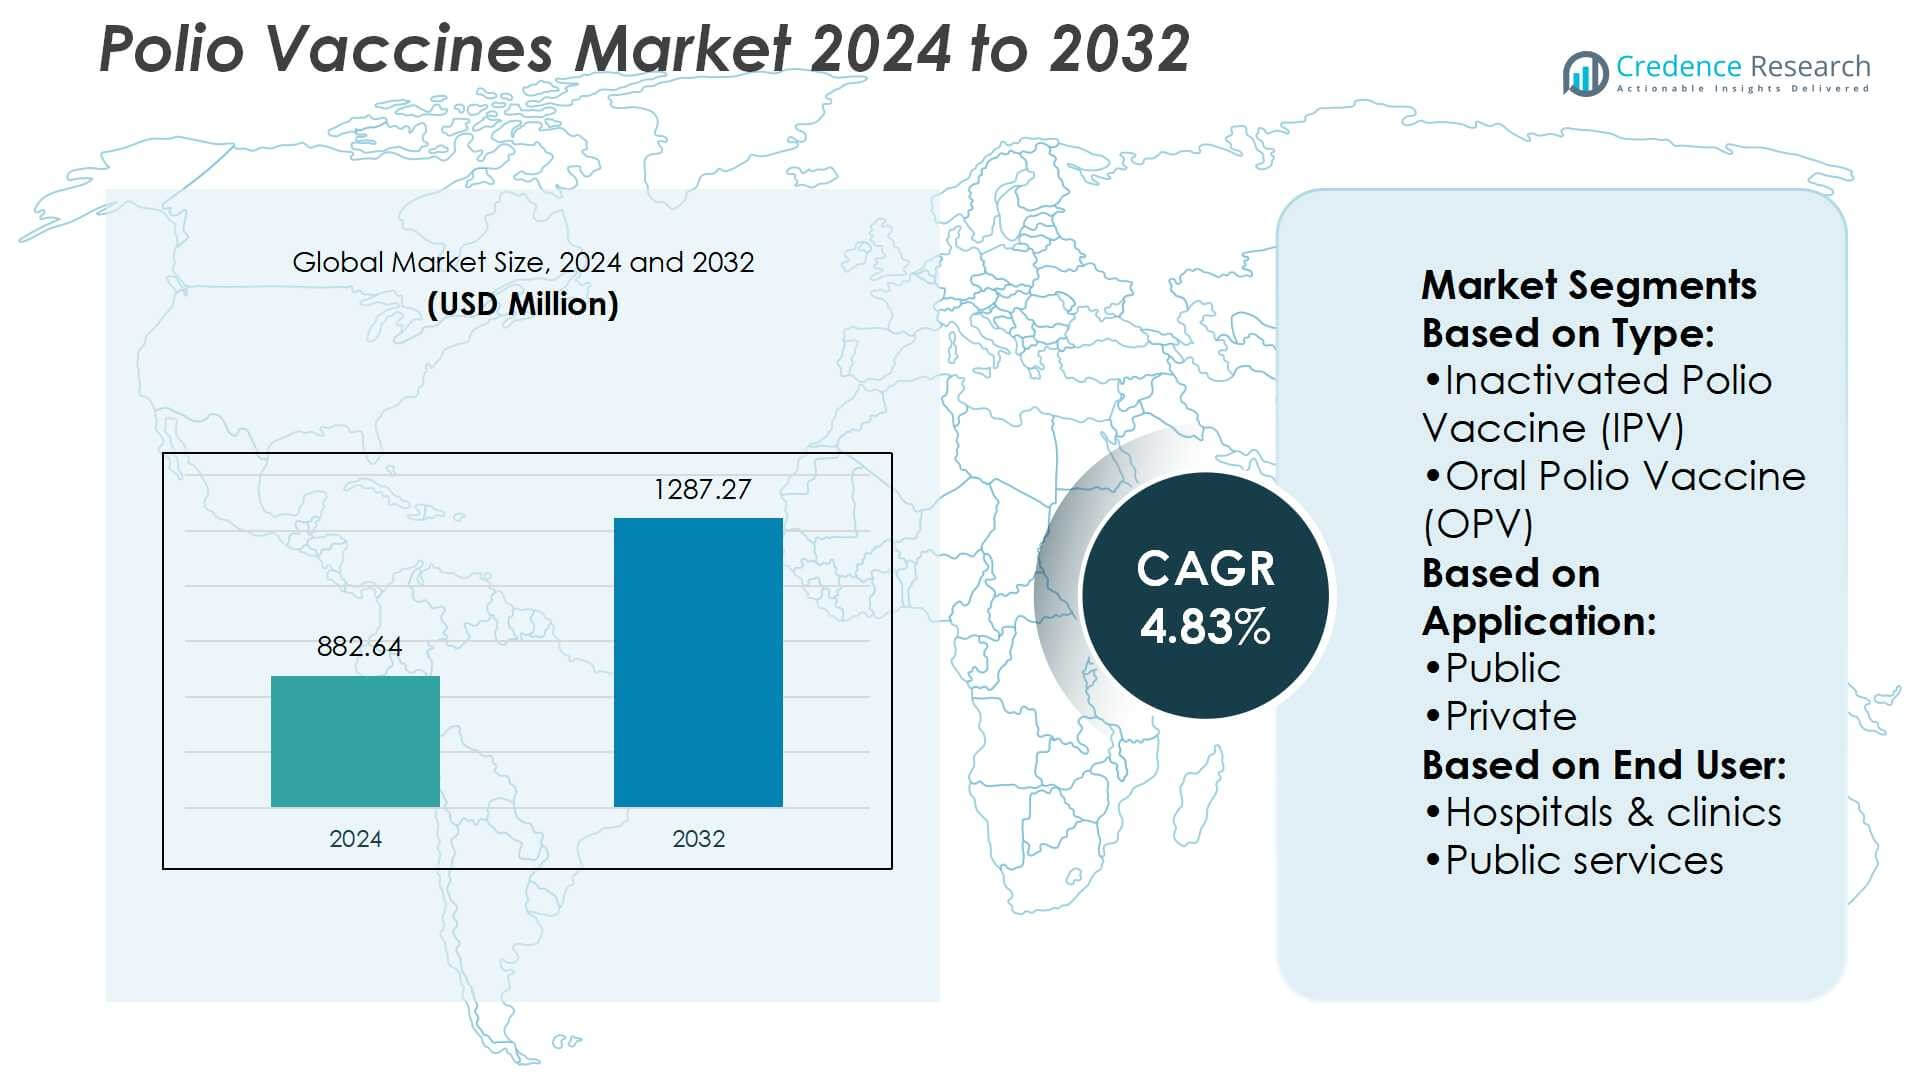
Polio Vaccines Market size was valued USD 882.64 million in 2024 and is anticipated to reach USD 1287.27 million by 2032, at a CAGR of 4.83% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Polio Vaccines Market Size 2024 | USD 882.64 Million |
| Polio Vaccines Market, CAGR | 4.83% |
| Polio Vaccines Market Size 2032 | USD 1287.27 Million |
The polio vaccines market is shaped by leading players such as Sanofi, GSK, Serum Institute, Panacea Biotec Ltd, Tiantan Biological, Bibcol, Bio-Med, IMBCA, and Halfkin Bio-Pharmaceuticals. These companies compete through large-scale manufacturing, government partnerships, and supply agreements with global health agencies to meet rising demand for IPV and OPV. Their strategies focus on expanding production capacity, ensuring regulatory compliance, and maintaining reliable distribution networks. Asia-Pacific emerges as the leading region, holding 42% market share, driven by its large population base, extensive government-led immunization programs, and strong support from international organizations to sustain eradication efforts.
 Market Insights
- The polio vaccines market was valued at USD 882.64 million in 2024 and is projected to reach USD 1287.27 million by 2032, registering a CAGR of 4.83% during the forecast period.
- Market growth is driven by government-led immunization campaigns, international funding, and the increasing global shift from OPV to IPV to ensure safer and more effective protection.
- A key trend is the integration of IPV into combination vaccines, reducing administration costs and improving compliance, while technological advancements in manufacturing strengthen production efficiency.
- The competitive landscape includes major players such as Sanofi, GSK, Serum Institute, Panacea Biotec Ltd, Tiantan Biological, Bibcol, Bio-Med, IMBCA, and Halfkin Bio-Pharmaceuticals, with strategies centered on capacity expansion, regulatory compliance, and global supply partnerships.
- Asia-Pacific leads with a 42% regional share, followed by North America at 22% and Europe at 20%, while the public application segment dominates with bulk procurement and wide-scale distribution through government and health agencies.
Market Segmentation Analysis:
By Type
The inactivated polio vaccine (IPV) dominates the segment, holding the largest market share due to its safety profile and effectiveness in eliminating risks of vaccine-derived poliovirus. Governments and health agencies increasingly recommend IPV over oral polio vaccines (OPV), driving higher adoption rates. Expanded immunization programs, especially in high-income and polio-free regions, further reinforce IPV’s market leadership. OPV still finds use in low- and middle-income countries due to its cost advantage and ease of administration, but global transition policies toward IPV ensure its long-term dominance.
- For instance, GSK has a global network of 37 medicines and vaccines manufacturing sites. Global vaccine supply chain: GSK's global supply chain is critical to manufacturing and supplying high-quality vaccines and medicines worldwide.
By Application
The public segment accounts for the dominant market share, supported by large-scale immunization campaigns led by governments and organizations such as WHO and UNICEF. Public procurement programs secure vaccines in bulk, ensuring affordability and wider access. These initiatives remain critical in both endemic and polio-free countries to sustain eradication efforts. The private segment grows steadily, driven by demand from urban populations seeking convenience and premium healthcare services. However, its share remains smaller compared to public distribution channels, which continue to anchor the market.
- For instance, Pfizer and BioNTech have distributed 5 billion doses globally of their mRNA COVID-19 vaccine, Comirnaty, leveraging lipid nanoparticle technology to scale production while retaining safety and efficacy.
By End-User
Hospitals and clinics represent the largest end-user segment, holding the majority market share due to their central role in vaccination programs and patient care. These facilities serve as primary vaccination points for both routine immunization and emergency response drives. Public services, including government-run vaccination centers and outreach programs, contribute significantly in rural and underserved regions, ensuring broad coverage. The “others” category, comprising NGOs and mobile health units, plays a supportive role, especially in remote areas. Strong hospital networks and government partnerships drive hospitals and clinics’ leadership position in this segment.
Key Growth Drivers
Government-Led Immunization Programs
Government-backed vaccination programs remain the strongest driver of the polio vaccines market. National health authorities, supported by WHO, UNICEF, and Gavi, purchase vaccines in bulk to sustain eradication initiatives. These programs ensure large-scale distribution through public healthcare systems and outreach campaigns. Mass immunization days and door-to-door programs enhance access, particularly in low-income and rural areas. Continued global financial commitments from donor countries and organizations guarantee stable demand, making government initiatives a cornerstone of market expansion and long-term sustainability.
- For instance, The combined BioNTech-Pfizer network had a goal of achieving an annual production capacity of up to 4 billion finished doses by the end of 2022, after reaching 3 billion finished doses.
Shift Toward Inactivated Polio Vaccine (IPV)
The increasing preference for IPV over OPV drives significant market growth. IPV eliminates the risk of vaccine-derived poliovirus, a major concern in global eradication efforts. Many countries are transitioning national schedules to IPV, supported by WHO recommendations and regulatory frameworks. Demand rises in high-income regions prioritizing safety and long-term immunity. Multinational manufacturers continue scaling production capacity to meet this shift, creating growth opportunities. The adoption of IPV as a global standard strengthens its market position while reducing reliance on OPV-based immunization campaigns.
- For instance, CureVac’s oncology therapeutic CVHNLC is being evaluated at dose levels between 100 µg and 400 µg in a dose-escalation study in metastatic squamous non-small cell lung cancer.
Rising Investments in Healthcare Infrastructure
Improved healthcare infrastructure in emerging economies supports higher vaccine penetration and market expansion. Governments across Asia-Pacific, Africa, and Latin America are strengthening immunization supply chains through cold storage facilities, logistics systems, and hospital capacity upgrades. Expanding access to routine immunization services ensures wider vaccine coverage in rural and underserved populations. Public-private partnerships also enable funding for vaccination drives, contributing to demand stability. With global efforts aimed at sustaining polio-free status, investments in infrastructure directly drive stronger vaccine distribution, reliability, and uptake worldwide.
Key Trends & Opportunities
Integration of Polio Vaccines with Routine Immunization
A key trend is the integration of polio vaccines into broader immunization schedules for infants and children. Combining IPV with other vaccines such as DTP (diphtheria, tetanus, and pertussis) reduces program costs and improves compliance. This approach boosts efficiency for healthcare systems while increasing uptake among parents. Pharmaceutical companies are developing combination vaccines that simplify administration, creating commercial opportunities. Such integration aligns with WHO recommendations and enhances long-term demand, positioning polio vaccines as part of universal health coverage frameworks globally.
- For instance, Merck’s V116-PCV, a 21-valent pneumococcal conjugate vaccine, has demonstrated the ability to elicit immune responses for its 21 serotypes in adult subjects during clinical trials.
Expansion in Emerging Economies
Emerging markets provide strong growth opportunities due to expanding healthcare access and rising birth rates. Governments in Asia-Pacific, Africa, and Latin America actively implement polio vaccination campaigns with international support. Growing middle-class populations demand better preventive healthcare services, increasing private segment uptake. International partnerships help fund large-scale procurement and distribution. As infrastructure strengthens, these regions are expected to become focal points for market growth, offering new opportunities for vaccine manufacturers and suppliers to capture untapped potential in large population bases.
- For instance, the World Health Organization (WHO) announced the allocation of 899,000 Mpox vaccine doses to the 9 African countries affected by the Mpox surge in Africa.
Key Challenges
Logistical and Distribution Barriers
One major challenge is maintaining effective cold chain systems in low-income and rural regions. Polio vaccines, especially IPV, require strict temperature control to preserve efficacy. Weak infrastructure in developing countries often leads to supply disruptions and wastage. Limited availability of trained personnel for handling and administering vaccines further complicates operations. These challenges delay immunization drives, creating risks for disease reemergence. Addressing cold chain inefficiencies requires sustained investments in storage, transport systems, and training programs to ensure consistent global vaccination coverage.
Vaccine Hesitancy and Misinformation
Vaccine hesitancy remains a growing obstacle to polio eradication efforts. Misinformation and mistrust in certain communities lead to refusal or delayed acceptance of vaccines. Cultural beliefs, religious influences, and fears of side effects often undermine public health campaigns. Social media amplifies misinformation, affecting parental decisions in both developed and developing countries. This resistance hampers herd immunity and forces governments to increase awareness and education campaigns. Overcoming hesitancy requires targeted communication strategies, community engagement, and transparent public health messaging to rebuild trust.
Regional Analysis
North America
North America holds 22% share of the polio vaccines market, driven by robust healthcare infrastructure and strong government funding. The U.S. dominates regional demand through mandatory immunization schedules, well-established cold chain systems, and continuous public health investments. Widespread adoption of IPV ensures safer immunization coverage, aligning with WHO recommendations. Canada contributes with comprehensive immunization programs and high vaccine compliance rates. Ongoing public awareness campaigns, efficient vaccine distribution, and stable private sector participation sustain demand. With consistent funding support and reliable healthcare frameworks, North America remains a stable and mature market for polio vaccines.
Europe
Europe accounts for 20% market share, supported by strict immunization policies and high healthcare standards. Countries such as Germany, France, and the UK mandate IPV in routine vaccination schedules, ensuring broad coverage. Strong government funding and EU-backed healthcare initiatives enhance access and sustain demand. Technological advances in vaccine production and distribution further strengthen supply reliability. Public awareness campaigns and healthcare professional engagement drive high compliance rates. With continued focus on safety and integration of IPV into combination vaccines, Europe maintains a leading role in sustaining eradication progress across developed nations.
Asia-Pacific
Asia-Pacific leads the global polio vaccines market with 42% share, driven by its large population base and extensive immunization campaigns. China and India account for a major portion of demand through government-led initiatives supported by WHO, UNICEF, and Gavi. Public programs ensure widespread access across rural and urban regions, though infrastructure disparities remain. Rising healthcare investments and growing adoption of IPV highlight progress in improving safety standards. Expanding birth rates and rapid urbanization further strengthen vaccine demand. Asia-Pacific’s dominant position reflects its role as both a high-demand region and a critical focus for eradication strategies.
Latin America
Latin America represents 8% of the global market, supported by government-led immunization programs and rising healthcare access. Countries such as Brazil and Mexico lead demand, with vaccination integrated into national schedules. Public procurement remains the largest contributor, ensuring widespread availability. International funding agencies support supply chains in low-income areas, reducing risks of outbreak resurgence. Expanding private healthcare networks and growing urban middle-class populations enhance uptake beyond public programs. Despite economic disparities, Latin America shows steady progress in sustaining polio-free status, making the region a consistent contributor to global vaccine demand.
Middle East & Africa
The Middle East & Africa region holds 8% share of the polio vaccines market, characterized by ongoing eradication efforts and reliance on international support. Nigeria and Pakistan remain key focus areas, requiring sustained immunization drives to prevent resurgence. WHO, Gavi, and UNICEF provide funding and logistical aid, strengthening distribution in conflict-prone and rural areas. Public services dominate vaccine administration, while infrastructure challenges and cold chain issues restrict full coverage. Despite barriers, rising government commitments and international partnerships are improving access, making the region a critical target for sustaining global eradication progress.
Market Segmentations:
By Type:
- Inactivated Polio Vaccine (IPV)
- Oral Polio Vaccine (OPV)
By Application:
- Public
- Private
By End User:
- Hospitals & clinics
- Public services
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Competitive Landscape
The Polio Vaccines Market players such as Panacea Biotec Ltd, GlaxoSmithKline, Serum Institute, IMBCA, Halfkin Bio-Pharmaceuticals, Bio-Med, Sanofi, Tiantan Biological, Bibcol, and GSK. The polio vaccines market features strong competition shaped by global supply networks, large-scale production, and long-term procurement agreements with governments and international health agencies. Manufacturers focus on scaling inactivated polio vaccine (IPV) output to meet rising safety standards while gradually phasing out oral polio vaccines (OPV). Strategic partnerships with organizations such as WHO, UNICEF, and Gavi ensure stable demand and widespread access, particularly in developing regions. Continuous investments in research, technology upgrades, and cold chain infrastructure enhance reliability and efficiency. Market players emphasize cost optimization, compliance with global immunization guidelines, and integration into routine vaccination schedules to strengthen their presence.
Key Player Analysis
- Panacea Biotec Ltd
- GlaxoSmithKline
- Serum Institute
- IMBCA
- Halfkin Bio-Pharmaceuticals
- Bio-Med
- Sanofi
- Tiantan Biological
- Bibcol
- GSK
Recent Developments
- In April 2025, Pfizer Inc. announced the amendment in the marketing authorization for ABRYSVO (RSV vaccine) that reported the extension of indication, including prevention of Lower Respiratory Tract Disease (LRTD) caused by RSV.
- In April 2025, GSK plc announced that the CDC’s Advisory Committee on Immunization Practices (ACIP) has voted to endorse the inclusion of Penmenvy (Meningococcal Groups A, B, C, W, and Y Vaccine) in the adolescent meningococcal vaccination schedule.
- In February 2025, Mass polio immunization campaign in Gaza immunized around 603,000 children with the new type 2 of the oral polio vaccine (nOPV2) to prevent poliovirus outbreak.
- In January 2025, Esphera Synbio, a well-known pre-clinical stage synthetic biology company, introduced a new project to develop and increase the efficacy of mRNA vaccines by using its proprietary technology to engineer mRNA vaccines.
- In May 2024, Novavax and Sanofi disclosed a co-exclusive licensing agreement to co-commercialize a COVID-19 vaccine and collaborate on developing novel combination vaccines for COVID-19 and influenza. This strategic partnership allows both companies to leverage their respective expertise and resources to bring innovative vaccine solutions to the market.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with increasing adoption of inactivated polio vaccines globally.
- Government funding will remain a primary driver of vaccine demand.
- Emerging economies will strengthen their role with rising immunization coverage.
- Combination vaccines will gain traction to improve compliance and reduce costs.
- International partnerships will ensure reliable supply across low-income countries.
- Cold chain infrastructure improvements will enhance vaccine distribution efficiency.
- Private healthcare networks will see gradual growth in vaccine administration.
- Public awareness programs will reduce vaccine hesitancy in key regions.
- Technological advancements will optimize large-scale vaccine production processes.
- Sustained eradication campaigns will continue to shape long-term market stability.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Government-Led Immunization Programs
National and international government-backed vaccination initiatives, supported by organizations like WHO, UNICEF, and Gavi, drive large-scale procurement and distribution of polio vaccines, ensuring high coverage and stable demand across both endemic and polio-free regions.
Shift Toward Inactivated Polio Vaccine (IPV)
The global transition from OPV to IPV, due to IPV's superior safety profile and elimination of vaccine-derived poliovirus risk, is accelerating market growth as more countries update immunization schedules and manufacturers scale up IPV production.
Rising Investments in Healthcare Infrastructure
Emerging economies are investing in cold chain logistics, healthcare facilities, and supply chain improvements, which expand vaccine reach, reduce wastage, and enable broader immunization coverage, especially in rural and underserved areas.
Integration with Routine Immunization and Combination Vaccines
The inclusion of polio vaccines in combination vaccines and routine immunization schedules reduces administration costs, improves compliance, and increases uptake, supporting sustained demand and operational efficiency for healthcare systems.
International Partnerships and Funding
Collaborations with global health agencies and donor organizations ensure reliable vaccine supply, funding for immunization campaigns, and technical support, particularly in low- and middle-income countries, stabilizing market growth and supporting eradication efforts.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Polio Vaccines Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Polio Vaccines Market projected to grow between 2025 and 2032?
Which Polio Vaccines Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Polio Vaccines Market?
Who are the leading companies in the Polio Vaccines Market?
Which region commanded the largest share of the Polio Vaccines Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Inactivated Polio Vaccine (IPV)
- 1.2.2 Oral Polio Vaccine (OPV)
- 1.3 By End User
- 1.3.1 Hospitals & clinics
- 1.3.2 Public services
- 1.3.3 Others (NGOs, mobile health units)
- 1.4 By Application
- 1.4.1 Public
- 1.4.2 Private
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 882.64 million → 2032: USD 1287.27 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Polio Vaccines Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Polio Vaccines Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Polio Vaccines Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Polio Vaccines Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Polio Vaccines Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Polio Vaccines Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Polio Vaccines Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Polio Vaccines Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 882.64 million → 2032: USD 1287.27 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Polio Vaccines Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Inactivated Polio Vaccine (IPV)
- 12.3.7.2 Oral Polio Vaccine (OPV)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals & clinics
- 12.4.7.2 Public services
- 12.4.7.3 Others (NGOs, mobile health units)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Public
- 12.5.7.2 Private
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Polio Vaccines End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Polio Vaccines Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Polio Vaccines Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Polio Vaccines Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Sanofi
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 GlaxoSmithKline (GSK)
- 18.4 Serum Institute
- 18.5 Panacea Biotec Ltd
- 18.6 Tiantan Biological
- 18.7 Bibcol
- 18.8 Bio-Med
- 18.9 IMBCA
- 18.10 Halfkin Bio-Pharmaceuticals
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

