
Market Overview
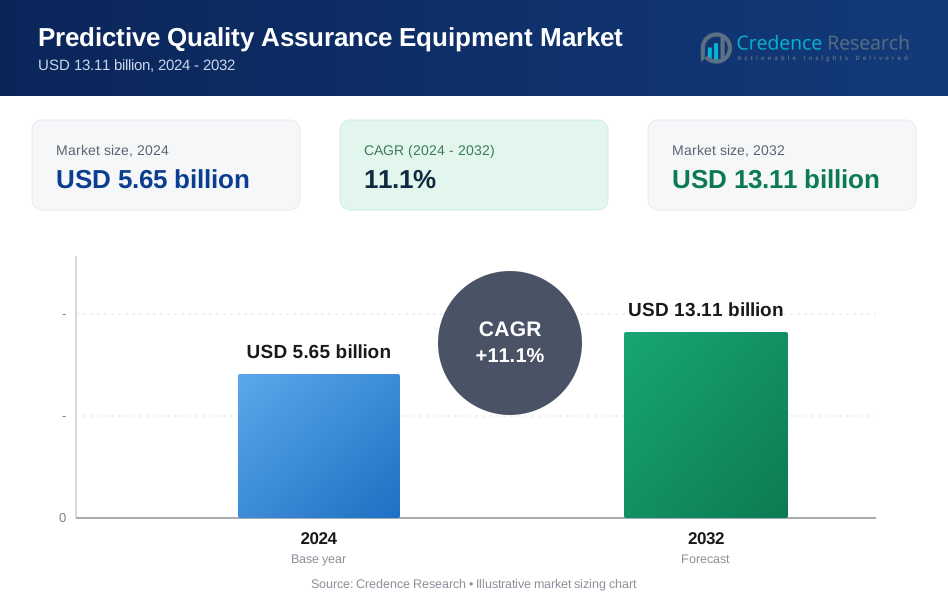
In the predictive quality assurance equipment market, revenue is expected to grow from USD 5.65 billion in 2024 to USD 13.11 billion by 2032, registering a robust CAGR of 11.1%.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Predictive Quality Assurance Equipment Market Size 2024 | USD 5.65 billion |
| Predictive Quality Assurance Equipment Market, CAGR | 11.1% |
| Predictive Quality Assurance Equipment Market Size 2032 | USD 13.11 billion |
The predictive quality assurance equipment market is driven by increasing demand for advanced manufacturing processes, rising adoption of Industry 4.0 technologies, and the need to minimize defects and production downtime. Companies are investing in real-time monitoring and predictive analytics to enhance product quality, reduce operational costs, and ensure regulatory compliance. Key trends include integration of artificial intelligence and machine learning for accurate defect prediction, growth of IoT-enabled quality inspection systems, and rising use of automated and non-destructive testing equipment. Additionally, the shift towards smart factories and data-driven decision-making is accelerating market expansion globally.
The predictive quality assurance equipment market demonstrates strong growth across North America, Europe, Asia Pacific, and the Rest of the World. North America leads with 35% market share, driven by advanced industrial infrastructure, while Europe holds 25%, supported by stringent quality standards and automation adoption. Asia Pacific captures 28%, fueled by rapid industrialization and smart factory expansion, and the Rest of the World accounts for 12%, led by emerging industrial sectors. Key players driving the market include Kistler Group, Fluke Corporation, Rockwell Automation, Bruel & Kjær, National Instruments, Honeywell International Inc., Pruftechnik, Meggitt PLC, General Electric (GE), Emerson Electric Co., and PCB Piezotronics.

Market Insights
- The predictive quality assurance equipment market is projected to grow from USD 5.65 billion in 2024 to USD 13.11 billion by 2032, achieving a CAGR of 11.1% driven by advanced manufacturing adoption.
- Rising demand for real-time monitoring and predictive analytics enhances product quality, reduces operational costs, and ensures regulatory compliance, fueling the growth of AI and IoT-enabled inspection systems globally.
- Vibration monitoring systems dominate with a 28% share, supported by thermal imaging, ultrasonic testing, laser alignment, acoustic emission detectors, and condition monitoring sensors, meeting the need for early fault detection and defect prevention.
- Artificial intelligence and machine learning lead the technology segment with 35% market share, followed by edge computing and digital twin technologies, enabling accurate defect prediction, process optimization, and data-driven decision-making.
- North America leads with 35% share due to industrial infrastructure and technology adoption, followed by Asia Pacific 28%, Europe 25%, and RoW 12%, with key players including Kistler Group, Fluke, Rockwell, and Honeywell.
Market Drivers
Rising Adoption of Industry 4.0 and Smart Manufacturing
The predictive quality assurance equipment market benefits from the rapid adoption of Industry 4.0 and smart manufacturing technologies. It enables manufacturers to implement real-time monitoring systems, improving process efficiency and reducing errors. Companies deploy advanced sensors, automation tools, and connected devices to identify potential defects early. It supports predictive maintenance and optimizes resource utilization, enhancing overall production performance. Growing demand for high-quality products drives investments in intelligent quality assurance solutions, ensuring consistent output across complex manufacturing lines.
- For instance, Siemens partnered with an automotive OEM to deploy predictive maintenance across 10,000 assets globally, resulting in a 12% reduction in unplanned downtime within 12 weeks by detecting issues early and preventing production delays.
Need to Reduce Operational Costs and Defects
Manufacturers increasingly prioritize reducing operational costs while maintaining high-quality standards, boosting the predictive quality assurance equipment market. It identifies process inefficiencies and predicts potential failures, minimizing waste and rework. Companies leverage data-driven insights to optimize production workflows and resource allocation. It also improves decision-making and reduces downtime, helping maintain competitive advantage. Rising pressure from stakeholders to deliver defect-free products motivates continuous investments in predictive quality assurance technologies.
- For instance, Volkswagen and Stellantis have deployed AI-powered platforms that monitor and predict quality issues in real time, reducing production time by up to 10% and enhancing efficiency on the production line.
Integration of Artificial Intelligence and Advanced Analytics
Artificial intelligence and advanced analytics fuel growth in the predictive quality assurance equipment market. It analyzes historical and real-time production data to anticipate defects and quality deviations accurately. Companies apply machine learning models to enhance predictive accuracy and streamline inspection processes. It reduces reliance on manual checks while increasing inspection speed and precision. Businesses embrace AI-driven quality assurance tools to improve productivity, maintain compliance, and enhance overall operational efficiency, supporting long-term market expansion.
Expansion of IoT-Enabled and Automated Inspection Systems
The market gains momentum from the widespread deployment of IoT-enabled and automated inspection systems. It connects machines, sensors, and analytics platforms to provide comprehensive monitoring of production lines. Companies utilize automated equipment to conduct non-destructive testing, ensuring consistent product quality. It allows real-time alerts, improving responsiveness and reducing the risk of failures. Rising demand for high-throughput and accurate inspection solutions drives investment in predictive quality assurance equipment globally, reinforcing its strategic role in modern manufacturing.
Market Trends
Integration of Artificial Intelligence and Machine Learning
The predictive quality assurance equipment market experiences strong growth due to the integration of artificial intelligence and machine learning technologies. It leverages historical and real-time data to identify defects, forecast failures, and optimize production quality. Companies implement AI-driven algorithms to enhance inspection accuracy and reduce manual intervention. It improves operational efficiency and ensures consistency in product output. Increasing adoption of intelligent analytics tools accelerates digital transformation in manufacturing environments, driving market expansion globally.
- For instance, Siemens’ MindSphere platform leverages ML algorithms to analyze sensor data from manufacturing lines, enabling predictive quality checks and reduced downtime.
Adoption of IoT-Enabled Quality Monitoring Systems
IoT-enabled quality monitoring systems drive trends in the predictive quality assurance equipment market. It connects sensors, devices, and analytics platforms to provide continuous monitoring of manufacturing processes. Companies use it to detect deviations in real time, enabling rapid corrective actions. It enhances visibility across production lines, reduces downtime, and supports predictive maintenance strategies. Growing reliance on connected industrial systems promotes data-driven decision-making and strengthens operational reliability, encouraging widespread adoption of predictive quality assurance equipment.
- For instance, RFID and barcode scanning technologies enable real-time tracking and authentication of components throughout production, preventing counterfeit parts and maintaining traceability.
Rise of Automated and Non-Destructive Testing Solutions
Automated and non-destructive testing solutions shape the trajectory of the predictive quality assurance equipment market. It allows manufacturers to conduct inspections without interrupting production, maintaining high throughput. Companies deploy automated systems for precision testing, defect detection, and process validation. It reduces human error and improves compliance with regulatory standards. Increasing demand for consistent product quality across complex manufacturing lines drives investment in advanced inspection technologies, reinforcing the market’s significance in modern industrial operations.
Shift Toward Smart Factories and Digital Transformation
The trend toward smart factories and digital transformation influences the predictive quality assurance equipment market. It integrates advanced monitoring, data analytics, and automation to optimize manufacturing workflows. Companies leverage smart systems to improve process efficiency, enhance product quality, and reduce operational risks. It supports predictive maintenance and real-time quality insights, fostering continuous improvement. Rising focus on digitalization in industrial operations encourages adoption of predictive quality assurance technologies, creating a sustainable growth trajectory for the market.
Market Challenges Analysis
High Initial Investment and Implementation Costs
The predictive quality assurance equipment market faces challenges due to high initial investment and implementation costs. It requires sophisticated sensors, advanced software, and integration with existing manufacturing systems, which can strain company budgets. Small and medium-sized enterprises often hesitate to adopt it due to limited financial resources. Companies must train staff and adapt workflows, increasing time and operational expenses. High upfront costs can slow market penetration, despite the long-term benefits of improved quality, efficiency, and defect reduction.
Data Management and Integration Complexities
Data management and integration complexities pose significant challenges in the predictive quality assurance equipment market. It generates large volumes of real-time production data that require secure storage, processing, and analysis. Companies encounter difficulties integrating new equipment with legacy systems and ensuring compatibility across multiple platforms. It demands skilled personnel to interpret analytics accurately and maintain system performance. Managing cybersecurity risks and ensuring data integrity adds additional operational burdens, potentially limiting adoption and slowing market growth.
Market Opportunities
Expansion into Emerging Economies and Industrial Sectors
The predictive quality assurance equipment market offers significant opportunities in emerging economies and diverse industrial sectors. It enables manufacturers to improve product quality, reduce defects, and enhance operational efficiency. Companies in automotive, electronics, pharmaceuticals, and aerospace sectors increasingly adopt it to maintain global competitiveness. Rising industrialization and government initiatives to promote advanced manufacturing technologies create a favorable environment for market growth. Expanding into underpenetrated regions allows companies to tap new revenue streams and establish long-term presence.
Advancements in AI, IoT, and Automation Technologies
Technological advancements in artificial intelligence, IoT, and automation present substantial opportunities in the predictive quality assurance equipment market. It supports real-time monitoring, predictive analytics, and automated inspections, enhancing process accuracy and consistency. Companies can leverage AI-driven solutions to reduce manual intervention and improve production throughput. IoT integration enables seamless data collection and analysis, fostering informed decision-making. Rapid innovation and digital transformation across industries drive demand, creating potential for market expansion and development of next-generation quality assurance solutions.
Market Segmentation Analysis:
By Equipment Type
In the predictive quality assurance equipment market, vibration monitoring systems lead the equipment segment with a 28% share, driven by their ability to detect early machinery faults and prevent downtime. Thermal imaging equipment holds 18%, supporting non-contact temperature monitoring. Ultrasonic testing devices account for 15%, while laser alignment tools represent 12%. Acoustic emission detectors capture 10%, condition monitoring sensors 9%, and other equipment 8%. Demand for real-time monitoring and defect prevention fuels growth across all sub-segments.
- For instance, Fluke's vibration monitoring sensors can detect slight bearing wear 12 to 18 months ahead of replacement needs, helping maintenance teams schedule timely interventions.
By Technology
Artificial intelligence and machine learning dominate the technology segment in the predictive quality assurance equipment market with a 35% share, enabling accurate defect detection and process optimization. Edge computing accounts for 25%, supporting real-time decision-making at production lines. Digital twin technology holds 20%, providing virtual simulation of processes to prevent faults. Other technologies, including cloud-based monitoring and advanced analytics, make up 20%. Growth is driven by efficiency, accuracy, and data-driven decision-making across industries.
- For instance, Cisco’s Edge Intelligence platform enables manufacturers to analyze sensor data directly on the factory floor, allowing immediate quality adjustments without latency issues.
By Operation Size
Large enterprises lead the operational segment in the predictive quality assurance equipment market with a 60% share, supported by higher budgets, advanced infrastructure, and extensive quality requirements. Small and medium enterprises (SMEs) hold 40%, gradually adopting predictive solutions to improve competitiveness. Large enterprises implement integrated monitoring systems, while SMEs focus on scalable, cost-effective solutions. Demand is fueled by the need to reduce defects, minimize downtime, and maintain compliance across diverse manufacturing operations.
Segments:
Based on Equipment Type
- Vibration Monitoring Systems
- Thermal Imaging Equipment
- Ultrasonic Testing Devices
- Laser Alignment Tools
- Acoustic Emission Detectors
- Condition Monitoring Sensors
- Others
Based on Technology
- Artificial Intelligence & Machine Learning
- Edge Computing
- Digital Twin Technology
- Others
Based on Operation Size
- Small & Medium Enterprises (SMEs)
- Large Enterprises
Based on Application
- Rotating Equipment Monitoring
- Gearbox & Bearing Fault Detection
- Tool Wear and Failure Prediction
- Production Line Quality Control
- Heat and Pressure Anomaly Detection
- Others
Based on End Use Industry
- Automotive
- Heavy Engineering & Construction Equipment
- Oil & Gas Machinery
- Aerospace & Defense Equipment Manufacturing
- Metal & Mining Equipment
- Power Generation Equipment
- Food & Beverage Processing Machinery
Based on Distribution channel
- Direct
- Indirect
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds 35% of the predictive quality assurance equipment market, driven by strong industrial infrastructure and early adoption of advanced manufacturing technologies. It benefits from widespread integration of AI, IoT, and automated monitoring systems in automotive, aerospace, and electronics sectors. Companies leverage predictive quality assurance to minimize production defects, enhance operational efficiency, and ensure regulatory compliance. Rising investments in smart factories and digitalization support market expansion. Continuous innovation and strong R&D activities maintain the region’s leadership.
Europe
Europe captures 25% of the predictive quality assurance equipment market due to high industrial automation and stringent quality standards. It integrates digital twin technologies, AI-based inspection tools, and condition monitoring systems across manufacturing lines. Companies adopt predictive quality assurance to reduce downtime, improve product reliability, and maintain competitive advantage. Government initiatives promoting Industry 4.0 adoption drive technology investments. The region benefits from strong automotive, pharmaceutical, and aerospace industries that prioritize precision and efficiency.
Asia Pacific
Asia Pacific holds 28% of the predictive quality assurance equipment market, reflecting rapid industrialization and growth of manufacturing hubs in China, Japan, and India. It supports high adoption of IoT-enabled monitoring systems and automated inspection equipment. Companies implement predictive quality assurance to enhance production quality, optimize resources, and meet rising consumer demand. Expansion of smart factories, increasing industrial investments, and growing awareness of defect reduction technologies boost market penetration. Competitive pricing and local manufacturing capacity accelerate adoption.
Rest of the World (RoW)
The Rest of the World accounts for 12% of the predictive quality assurance equipment market, driven by emerging industrial sectors in Latin America, the Middle East, and Africa. It enables manufacturers to improve process reliability, reduce operational risks, and ensure product consistency. Companies adopt predictive quality assurance solutions to meet international quality standards and enhance competitiveness. Growing interest in digital transformation and advanced manufacturing solutions supports market growth. Regional infrastructure development and technology collaborations further stimulate adoption of predictive quality assurance equipment.
Key Player Analysis
- Kistler Group
- Fluke Corporation
- Rockwell Automation
- Bruel & Kjær
- National Instruments
- Honeywell International Inc.
- Pruftechnik
- Meggitt PLC
- General Electric (GE)
- Emerson Electric Co.
- PCB Piezotronic
Competitive Analysis
The predictive quality assurance equipment market remains highly competitive, driven by continuous innovation and technological advancements. It features key players such as Kistler Group, Fluke Corporation, Rockwell Automation, Bruel & Kjær, National Instruments, Honeywell International Inc., Pruftechnik, Meggitt PLC, General Electric (GE), Emerson Electric Co., and PCB Piezotronics. These companies focus on developing advanced monitoring systems, AI-driven analytics, and IoT-enabled inspection solutions to enhance manufacturing efficiency and product quality. It experiences intense competition in pricing, product performance, and service offerings. Companies invest heavily in R&D to introduce innovative equipment, strengthen customer relationships, and expand market reach globally. Strategic collaborations, partnerships, and acquisitions remain common to gain technological capabilities and enter new regional markets. It also faces pressure to meet evolving industry standards and regulatory compliance requirements, prompting continuous improvement in solution accuracy and reliability. Market leaders maintain their positions by delivering integrated quality assurance systems, supporting predictive maintenance, and enabling real-time defect detection across multiple industries.
Recent Developments
- In July 2025, Critical Manufacturing acquired Convanit, an AI specialist in image-based analytics, enhancing its Manufacturing Execution System capabilities for improved precision and automation in smart manufacturing.
- In May 2025, RESA Power expanded its Florida operations by acquiring MP Predictive Technologies, a multiservice, NETA-accredited company specializing in predictive maintenance and asset management solutions.
- In February 2025, Paeonia Industries acquired the Savant Group, a Midland-based consortium focused on lubrication technology and equipment testing, strengthening Paeonia’s North American reach and resource capabilities.
- In March 2025, Minitab, a leader in data analysis and continuous process improvement, acquired Prolink Software. Prolink specializes in automating data collection from inspection equipment, enhancing statistical process control and quality analytics capabilities.
Market Concentration & Characteristics
The predictive quality assurance equipment market exhibits a moderately concentrated structure, with a few global leaders controlling significant market share while numerous regional and specialized players operate in niche segments. It features competition based on technology innovation, product performance, and service quality. Key players such as Kistler Group, Fluke Corporation, Rockwell Automation, Bruel & Kjær, National Instruments, Honeywell International Inc., Pruftechnik, Meggitt PLC, General Electric (GE), Emerson Electric Co., and PCB Piezotronics invest heavily in research and development to introduce advanced AI-driven, IoT-enabled, and automated quality assurance solutions. It experiences strategic partnerships, collaborations, and acquisitions to expand regional presence and enhance technological capabilities. Market participants emphasize real-time defect detection, predictive analytics, and operational efficiency to gain competitive advantage. It benefits from growing demand across automotive, electronics, aerospace, and pharmaceutical industries, driving continuous innovation, integration of emerging technologies, and expansion into underpenetrated regions.
Report Coverage
The research report offers an in-depth analysis based on Equipment Type, Technology, Operation Size, Application, End-Use Industry, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The predictive quality assurance equipment market will witness widespread adoption of AI and machine learning technologies for accurate defect detection.
- Integration of IoT-enabled sensors will enhance real-time monitoring across production lines.
- Digital twin technology will gain traction to simulate processes and prevent potential failures.
- Large enterprises will continue leading adoption, while SMEs will increasingly implement scalable solutions.
- Automated and non-destructive testing equipment will expand across high-precision industries.
- Smart factory initiatives will drive demand for connected and predictive quality systems.
- Companies will invest in advanced analytics to improve operational efficiency and product consistency.
- Regional growth will accelerate in Asia Pacific due to industrialization and manufacturing expansion.
- Strategic collaborations and partnerships will increase among key players to enhance technology offerings.
- Focus on regulatory compliance and defect reduction will shape innovation in predictive quality assurance solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for predictive quality assurance equipment market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the predictive quality assurance equipment market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the predictive quality assurance equipment market?
Who are the leading companies in the predictive quality assurance equipment market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Predictive Quality Assurance Equipment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Predictive Quality Assurance Equipment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5.65 billion → 2032: USD 13.11 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Predictive Quality Assurance Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Predictive Quality Assurance Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Predictive Quality Assurance Equipment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Predictive Quality Assurance Equipment Market Drivers
- 3.3 Predictive Quality Assurance Equipment Market Restraints & Challenges
- 3.4 Predictive Quality Assurance Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Predictive Quality Assurance Equipment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Predictive Quality Assurance Equipment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Predictive Quality Assurance Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Predictive Quality Assurance Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Predictive Quality Assurance Equipment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Predictive Quality Assurance Equipment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Predictive Quality Assurance Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Predictive Quality Assurance Equipment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Predictive Quality Assurance Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Predictive Quality Assurance Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Predictive Quality Assurance Equipment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Predictive Quality Assurance Equipment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Predictive Quality Assurance Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Predictive Quality Assurance Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Predictive Quality Assurance Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Predictive Quality Assurance Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Predictive Quality Assurance Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Predictive Quality Assurance Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Predictive Quality Assurance Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
