
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Professional Mobile Radio (PMR) Market Size 2024 | USD 26,252.96 Million |
| Professional Mobile Radio (PMR) Market, CAGR | 13.3% |
| Professional Mobile Radio (PMR) Market Size 2032 | USD 71,288.18 Million |
Market Overview:
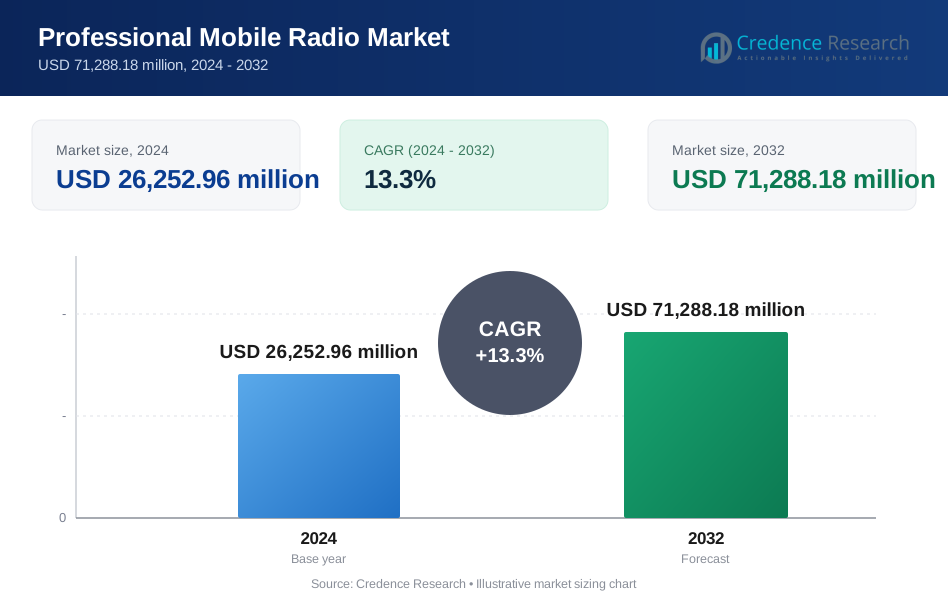
The Professional Mobile Radio (PMR) Market is projected to grow from USD 26,252.96 million in 2024 to an estimated USD 71,288.18 million by 2032, with a compound annual growth rate (CAGR) of 13.3% from 2024 to 2032.
Key drivers of the PMR market include the increasing demand for secure and reliable communication systems across industries such as public safety, transportation, utilities, and defence. The adoption of PMR solutions, particularly in mission-critical applications, is being fueled by the need for enhanced operational efficiency and safety. Government regulations mandating the use of PMR in emergency services, coupled with technological advancements in digital PMR systems (such as LTE and 5G integration), are further propelling market growth. Additionally, the growing trend of digital transformation and the need for real-time communication and data sharing in industries like manufacturing and logistics are also contributing to market expansion.
Regionally, North America and Europe are expected to lead the PMR market, driven by significant investments in public safety and defence sectors, along with strong regulatory frameworks supporting secure communication technologies. In North America, the United States is a key player, with its advanced infrastructure and increasing reliance on PMR for critical communications. Europe is also experiencing robust demand, especially in countries such as the UK, Germany, and France, where emergency services and industrial applications heavily rely on secure radio networks. In the Asia Pacific region, rapid urbanization, infrastructural developments, and increased investment in public safety are driving demand for PMR solutions. Countries like China, India, and Japan are expected to witness significant market growth, as governments and industries invest in smart city projects and enhanced communication networks for public safety. The Latin American and Middle Eastern regions are also witnessing growth in PMR adoption, particularly for sectors like oil and gas, utilities, and transportation, which require reliable communication networks for day-to-day operations.
Market Drivers:
Increasing Demand for Secure Communication in Public Safety and Emergency Services:
One of the most significant drivers for PMR adoption is the growing need for secure communication in public safety and emergency services. Governments across the globe require mission-critical communication solutions to ensure the safety of first responders and manage emergency situations effectively. For instance, in the U.S., the First Responder Network Authority (FirstNet), established by the federal government, is dedicated to providing a nationwide broadband network specifically for public safety agencies. By 2021, FirstNet had expanded its coverage to 99% of the U.S. population, ensuring that first responders can communicate securely in emergencies, especially in rural and underserved areas. Similarly, the UK Home Office has introduced a Digital Radio Service for Emergency Services that mandates the use of secure, interoperable digital communication systems for police, fire, and ambulance services across the country. The system aims to increase the interoperability between various emergency agencies, improving coordination during national emergencies.
Technological Advancements in Digital PMR Systems:
Advancements in digital PMR technology have significantly improved the capabilities of traditional radio communication systems. The integration of digital technologies like LTE and 5G has enhanced the performance of PMR systems, enabling real-time data transmission, video streaming, and GPS tracking. These technological improvements provide industries with high-speed data communication in addition to voice services, making PMR solutions even more versatile and essential. For instance, in 2020, the Federal Communications Commission (FCC) in the U.S. authorized the integration of 5G technology into mission-critical communications, allowing public safety agencies to benefit from faster data transmission speeds and reduced latency. The International Telecommunication Union (ITU) has also developed a set of standards for 5G communications for public safety, which are expected to be rolled out globally. This transition is expected to enable more efficient real-time decision-making in emergency situations, further promoting the adoption of digital PMR systems. In Germany, the government-backed BOS Digital Radio Network is utilizing digital PMR systems to provide secure communication for public safety agencies. The network, which began its nationwide rollout in 2017, is now operational in over 90% of the country and offers features like encrypted voice and data services, and seamless communication for emergency responders even in remote areas.
Regulatory Support and Government Initiatives:
Government regulations and initiatives play a crucial role in driving the adoption of PMR systems. Many countries have developed policies and frameworks that require the use of secure communication solutions for public safety and other critical industries, ensuring the deployment of mission-critical communication systems across their territories. For instance, in India, the Ministry of Home Affairs (MHA) launched the National Emergency Communication Plan (NECP) to enhance communication among emergency responders. The NECP aims to connect police, fire, and ambulance services across the country through digital radio networks. By 2023, the Indian government plans to have more than 50,000 public safety communication terminals installed as part of the Digital Police Project. Additionally, the European Union Agency for Cybersecurity (ENISA) has outlined security protocols for critical communication networks, emphasizing the need for PMR systems to meet strict cybersecurity standards in public safety operations. EU member states, such as France and Italy, are already aligning their national security frameworks with ENISA guidelines to improve the resilience of their communication infrastructure.
Growing Adoption of PMR in Commercial and Industrial Sectors:
PMR systems are no longer limited to public safety applications. The demand for secure and reliable communication systems is also expanding rapidly in commercial and industrial sectors, particularly in industries such as utilities, transportation, oil and gas, and manufacturing. These sectors require communication solutions that ensure operational safety, coordination, and efficiency across geographically dispersed teams. For instance, in the oil and gas sector, Shell has been deploying advanced PMR systems to ensure continuous communication in its offshore and remote onshore operations. These communication systems help Shell's teams coordinate activities, monitor safety, and respond quickly to emergencies. Shell uses a mix of TETRA-based PMR solutions and LTE technology for secure communications in its offshore oil rigs, with more than 50 sites globally. In the maritime sector, the International Maritime Organization (IMO) mandates the use of PMR systems in vessels for communication during distress situations. The IMO's Global Maritime Distress and Safety System (GMDSS) requires all ships to be equipped with reliable communication equipment, including digital radios, to ensure safety at sea. According to the IMO, as of 2020, over 25,000 commercial ships worldwide are now equipped with GMDSS-compliant communication systems.
Market Trends:
Integration of LTE and 5G Technologies with PMR Systems:
One of the most notable trends in the PMR market is the growing integration of Long-Term Evolution (LTE) and 5G technologies into professional radio systems. Traditional PMR solutions, such as TETRA and P25, have been reliable for mission-critical communications, but the adoption of LTE and 5G is significantly enhancing the capabilities of these systems, allowing for faster data transmission, higher bandwidth, and better coverage. For instance, in France, the government-backed TETRA and LTE hybrid network is being rolled out for public safety agencies, enabling both voice and data services through a single infrastructure. The system, which integrates TETRA's secure communication features with the high-speed data capabilities of LTE, was launched in Paris and other major cities, providing first responders with enhanced communication tools in emergencies. The French government is investing millions in expanding this network across the country, highlighting the increasing importance of high-speed, reliable data and voice communication for public safety. Similarly, in Japan, NTT Docomo, a leading telecommunications provider, has been working with government agencies to pilot 5G-based PMR systems for emergency management. These systems are designed to provide not only voice communication but also real-time video streaming, GPS data, and environmental sensors. As part of the Japan Ministry of Internal Affairs and Communications' initiative, the goal is to create a fully integrated 5G-enabled communications network for public safety by 2025.
Adoption of PMR Solutions in Smart Cities and Industrial Applications:
The rise of smart cities and the digital transformation of industrial sectors is another key trend accelerating the adoption of PMR systems. As urban centers around the world incorporate more connected technologies, secure communication solutions are becoming essential for managing everything from traffic systems to utilities and public safety. For instance, the Singapore Smart Nation initiative aims to implement a wide range of IoT and communication technologies to enhance urban living. As part of this initiative, the government has deployed PMR systems integrated with IoT sensors to monitor and manage city infrastructure, including traffic, water supply, and waste management. The goal is to create a fully integrated communication ecosystem where data from various sources is shared in real-time to improve decision-making and operational efficiency. This growing demand for secure, high-bandwidth communication solutions in smart cities is expected to drive further adoption of PMR systems in both urban and industrial environments. In the oil and gas sector, Royal Dutch Shell has been actively integrating PMR solutions into its operations in remote and offshore locations. Shell’s offshore oil platforms, for example, are equipped with secure PMR networks to ensure constant communication between teams onshore and at sea. These systems are critical for ensuring worker safety, coordinating emergency responses, and optimizing operations. As of 2020, Shell reported using digital PMR systems on over 50 offshore platforms globally, showcasing the growing reliance on these communication technologies in high-risk, high-stakes industries.
Market Challenge Analysis:
High Implementation Costs and Maintenance Challenges:
One of the primary challenges faced by the Professional Mobile Radio (PMR) market is the high initial investment required for the deployment and ongoing maintenance of these systems. PMR solutions, particularly those based on digital technologies like TETRA, DMR, and P25, often require substantial upfront capital for infrastructure, including radios, base stations, towers, and communication equipment. This is especially difficult for smaller organizations or those in developing economies, where budgets for public safety or industrial communication infrastructure may be limited. The shift towards hybrid systems combining legacy PMR with newer technologies like LTE or 5G further complicates the cost structure, as organizations must manage both old and new technologies. In addition to the high initial costs, maintenance and operational expenses can also be significant. PMR systems require regular updates, servicing, and compliance with security protocols, especially in industries like defence, public safety, and utilities. The complexity of maintaining a robust, secure network-especially as new technologies are integrated-can increase costs for organizations and governments. This is compounded by the need for specialized expertise in managing and operating mission-critical communication networks. For instance, in the United States, the FirstNet network, which connects first responders, has required extensive investment not just in infrastructure but also in ongoing operational and maintenance costs. These financial and operational barriers may discourage smaller organizations from adopting the latest PMR solutions, creating a challenge for the market’s growth.
Interoperability and Standardization Issues:
Another significant challenge for the PMR market is the issue of interoperability and the lack of universal standards across different regions and industries. While PMR systems like TETRA, P25, and DMR are widely used, they often face integration problems when attempting to communicate across different platforms, especially when devices and networks from different manufacturers are involved. In public safety sectors, where agencies may use a mix of analog and digital systems, ensuring seamless communication between different departments, jurisdictions, and even countries can be problematic. For example, in Europe, several countries have their own public safety communication systems that are not always compatible with each other, which can hinder coordinated responses during cross-border emergencies. Similarly, the integration of LTE and 5G technologies into existing PMR networks introduces new interoperability challenges. Many legacy systems were not designed to work with next-generation communication technologies, requiring additional software and hardware upgrades, which can create technical barriers and increase costs. This is particularly evident in regions like Asia Pacific and Latin America, where the adoption of 5G and digital PMR systems is uneven. While countries like South Korea and Japan are making strides in 5G-based PMR networks, others like India and Brazil face challenges in harmonizing new technologies with older infrastructure. The lack of global standards for PMR systems, coupled with varying regulatory requirements, further complicates interoperability, making it a persistent issue for the market’s long-term growth. These challenges highlight the need for stronger collaboration between industry stakeholders, including government agencies, technology providers, and end-users, to establish clear standards and protocols for interoperable communication networks.
Market Segmentation Analysis:
By Type
The Professional Mobile Radio (PMR) market can be segmented based on the type of communication system utilized. The major types are conventional PMR systems, trunked PMR systems, and digital PMR systems. Conventional PMR systems remain popular due to their reliability in basic communication setups. However, trunked PMR systems, which offer enhanced scalability and efficiency, are gaining traction, especially in industries requiring a large number of communication channels. Digital PMR systems, including those based on TETRA and DMR technologies, are increasingly preferred for their superior voice quality, encryption capabilities, and ability to transmit both voice and data. These systems are crucial in mission-critical applications where operational efficiency and security are paramount.
By Technology
In terms of technology, the PMR market is primarily divided into analog and digital systems. Analog PMR systems are still in use in some regions and industries due to their simplicity and lower cost. However, the shift toward digital PMR systems is accelerating. Digital PMR technologies like TETRA, DMR, and P25 are preferred for their ability to handle both voice and data, offer better coverage, and provide encryption for secure communications. Additionally, the integration of LTE and 5G technologies is expanding, enabling higher data speeds, lower latency, and improved communication features, such as real-time video streaming and GPS tracking, which is driving the digitalization of PMR networks.
By End-User
The end-user segmentation of the PMR market includes industries such as public safety, transportation, utilities, defence, and manufacturing. The public safety sector, including police, fire, and emergency medical services, is one of the largest consumers of PMR systems, as secure and reliable communication is critical for effective emergency response. The transportation industry, including aviation, maritime, and railways, also requires PMR systems for coordination and safety. The utilities sector relies on PMR for monitoring and managing infrastructure, while defence applications are increasingly adopting PMR for secure, encrypted communication in military operations. Manufacturing and industrial sectors, particularly those dealing with hazardous environments or requiring large-scale operations, are also rapidly adopting PMR solutions for communication and safety purposes.
Segmentation:
Based on Product Type:
- Conventional PMR Systems
- Trunked PMR Systems
- Digital PMR Systems (TETRA, DMR, P25)
- Hybrid PMR Systems
Based on Technology:
- Analog PMR Systems
- Digital PMR Systems (TETRA, DMR, P25)
- LTE-Integrated PMR Systems
- 5G-Integrated PMR Systems
Based on End-User:
- Public Safety (Police, Fire, Emergency Medical Services)
- Transportation (Aviation, Maritime, Railways)
- Utilities (Electricity, Water, Gas)
- Defence (Military and Security)
- Manufacturing and Industrial (Oil & Gas, Mining, Heavy Industries)
Based on Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America is one of the largest and most developed markets for Professional Mobile Radio (PMR) systems, accounting for a significant share of the global market. The region's dominance can be attributed to its advanced infrastructure, widespread adoption of secure communication technologies, and government initiatives supporting public safety and defence communication systems. The United States is the key player in the region, with its FirstNet network driving the demand for PMR solutions. FirstNet, the nationwide broadband network dedicated to first responders, has been pivotal in promoting the use of LTE-based PMR systems. The U.S. government continues to invest heavily in modernizing emergency communication infrastructure, which ensures that PMR systems remain a critical part of the nation’s public safety framework. In addition to public safety, sectors such as transportation, utilities, and defence also contribute significantly to the region’s PMR market share. The Federal Communications Commission (FCC) and other regulatory bodies have played a key role in creating a favorable environment for PMR adoption by enforcing strict security protocols and promoting the integration of digital technologies, such as 5G and LTE, in mission-critical communication networks. North America is expected to maintain a strong position in the market, with a market share of approximately 35-40% of the global PMR market. This is driven by continued investments in public safety communication and the growing demand for digital transformation across various industries.
Europe
Europe holds a substantial share of the global PMR market, with countries such as Germany, the United Kingdom, France, and Italy leading the way in PMR adoption. In Europe, the demand for PMR systems is primarily driven by the public safety and emergency services sector. The European Union has laid out specific regulations and standards for critical communications, including the European Commission’s Emergency Communications Framework, which mandates secure and interoperable communication networks for emergency responders. As a result, many European countries have implemented TETRA-based PMR systems and are now transitioning to LTE-integrated solutions to meet the demands of modern public safety operations. The BOS Digital Radio network in Germany and the ESMCP (Emergency Services Mobile Communications Programme) in the United Kingdom are prime examples of large-scale, government-backed PMR networks. The United Kingdom’s O2 has played a central role in deploying the Emergency Services Network (ESN), which will replace the legacy Airwave system. These initiatives are a part of Europe’s broader push to modernize emergency services and enhance communication capabilities during crises. The European market holds approximately 30-35% of the global PMR market share, with the region's continued investment in smart city projects, critical infrastructure, and defence sectors contributing to its growth.
Asia Pacific
The Asia Pacific (APAC) region is experiencing significant growth in the PMR market, driven by rapid urbanization, infrastructure development, and increasing investments in public safety and defence. Countries like China, India, Japan, and Australia are leading the adoption of advanced communication solutions. In China, the government’s focus on smart city development and infrastructure modernization is fueling the demand for secure, integrated PMR systems. The Chinese Ministry of Public Security has initiated projects to enhance public safety communication systems across the country, incorporating both TETRA and LTE technologies into new and existing networks. In India, the government has rolled out the National Emergency Communication Plan (NECP), which is expected to boost the demand for digital PMR systems across public safety agencies. Additionally, Japan is actively working to integrate 5G technology into its public safety networks, particularly for disaster management and emergency response systems. The Asia Pacific region is also seeing increasing adoption of PMR solutions in industrial sectors, particularly in oil & gas and mining, where reliable communication is crucial in hazardous environments. The region is projected to witness the highest growth in the coming years, with a market share of approximately 20-25% of the global PMR market. As governments and industries invest heavily in upgrading their communication infrastructures, APAC is expected to become a key player in the PMR market, especially with the ongoing development of next-generation technologies like 5G and the expansion of smart cities.
Key Player Analysis:
- Sepura PLC
- Motorola Solutions, Inc.
- Harris Corporation
- JVC Kenwood Corporation
- Tait Communications
- Codan Radio Communications
- Hytera Communications Corporation Limited
- Raytheon Company
- Airbus Group
- Thales
- Sepura
- Cartel Communication Systems
- EXACOM
- PowerTrunk
- Simoco
Competitive Analysis:
The competitive landscape of the Professional Mobile Radio (PMR) market is characterized by the presence of both established players and emerging companies that provide a wide range of communication solutions tailored for mission-critical applications. Leading companies in the PMR market include Motorola Solutions, Hytera Communications, Thales Group, Kenwood Corporation, and Sepura. These companies dominate the market by offering advanced PMR systems that integrate digital technologies, such as TETRA, DMR, and P25, along with the latest advancements in LTE and 5G connectivity. Motorola Solutions, for instance, is a key player, known for its digital PMR systems and secure communication solutions across public safety, utilities, and industrial sectors. Hytera is another major competitor, offering a comprehensive portfolio of digital radio communication products and LTE-based solutions that cater to a wide range of end users, from public safety to transportation. In addition to traditional PMR system providers, new entrants and telecom companies are pushing the market toward integrated LTE and 5G networks, challenging established companies to innovate and adapt. These developments are particularly relevant in regions like North America and Europe, where public safety agencies are increasingly shifting to next-generation communication systems. Regulatory frameworks and government contracts are key competitive factors, with companies vying for lucrative public safety contracts. To maintain a competitive edge, firms are increasingly focusing on R&D to develop hybrid systems, improve interoperability, and enhance the security of their communication networks, ensuring they can meet the evolving needs of mission-critical applications in an increasingly digital world.
Recent Developments:
- In May 2023, the TAIT AXIOM wearable device gained the ability to seamlessly integrate with Tait TeamPTT and ESChat solutions, enabling users to connect to any Land Mobile Radio (LMR) network. Originally launched in 2022 with support for DMR Tier 3, the device now also supports P25, DMR Tier 2, and analog networks. This expanded compatibility enhances the device’s functionality, allowing users to communicate across a wider range of radio networks, thereby improving flexibility and interoperability.
- In August 2022, Motorola Solutions strengthened its mission-critical radio communications capabilities and broadened its global footprint by acquiring Barrett Communications. Headquartered in Perth, Barrett Communications specializes in providing radio communications solutions to sectors such as civil security, border security, coastguards, government agencies, and the private sector. The financial details of the acquisition have not been disclosed.
Market Concentration & Characteristics:
The PMR market is moderately concentrated, with a few large players dominating the landscape, while numerous smaller regional and niche companies cater to specific market needs. Major players such as Motorola Solutions, Hytera Communications, Thales Group, and Kenwood Corporation hold a significant market share due to their established product portfolios, strong brand recognition, and extensive customer bases across public safety, defence, transportation, and industrial sectors. These companies benefit from economies of scale, substantial R&D investments, and a global reach, which enables them to offer comprehensive, integrated solutions that meet the diverse demands of mission-critical communication systems. However, competition is intensifying as new entrants, including telecommunications companies and tech startups, increasingly focus on next-generation communication technologies like 5G and LTE. These advancements are disrupting traditional PMR solutions by enabling faster, more reliable, and data-rich communication systems, pushing incumbents to innovate and expand their offerings. The regulatory environment also plays a crucial role in shaping market dynamics, as governments worldwide enforce stricter requirements for secure, interoperable, and resilient communication systems. In this context, interoperability and security have become key characteristics of the PMR market, with end-users demanding seamless communication across different platforms and technologies. Additionally, regional diversity in terms of infrastructure maturity and regulatory requirements influences market penetration, with North America and Europe leading adoption, while Asia Pacific is poised for rapid growth driven by urbanization and smart city initiatives. Overall, while the market is concentrated, the shift toward digital and hybrid PMR systems is opening opportunities for both established and new players to differentiate themselves through innovation and compliance with evolving standards.
Report Coverage:
This report provides a comprehensive analysis of the Professional Mobile Radio (PMR) market, offering detailed insights into key trends, drivers, challenges, and opportunities influencing the industry from 2024 to 2032. It covers market segmentation by product type, technology, end-user, and geography, providing a nuanced understanding of the different factors shaping the market’s growth. The report delves into the evolving landscape of PMR technologies, focusing on digital systems such as TETRA, DMR, and P25, along with the growing adoption of LTE and 5G-enabled solutions. It also highlights the key industries leveraging PMR systems, including public safety, transportation, utilities, defence, and manufacturing. The regional analysis covers North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, offering insights into regional market dynamics and growth potential. Special attention is given to emerging markets, particularly in Asia Pacific, where rapid urbanization and government investments in smart cities are driving demand for advanced communication systems. The report also evaluates the competitive landscape, detailing the market share and strategic initiatives of leading players like Motorola Solutions, Hytera, and Thales Group, as well as emerging companies that are capitalizing on technological advancements. Additionally, it explores key market challenges such as high implementation costs, interoperability issues, and the need for regulatory compliance. Overall, this report provides valuable data for stakeholders looking to understand market trends, make informed decisions, and capitalize on growth opportunities in the PMR sector.
Future Outlook:
- The PMR market will continue to see strong growth as industries increasingly prioritize secure, reliable communication for mission-critical operations.
- Integration of LTE and 5G technologies will enhance PMR systems, providing faster data transfer, reduced latency, and real-time video and sensor data capabilities.
- Governments worldwide will invest heavily in digital and hybrid PMR networks, focusing on public safety and emergency services.
- The expansion of smart cities will drive demand for advanced PMR systems that integrate with IoT and smart infrastructure for improved urban management.
- The adoption of PMR solutions in the industrial sector, especially in remote and hazardous environments like oil and gas, will increase significantly.
- The continued development of secure communication standards will ensure that PMR systems meet the growing cybersecurity needs of various sectors.
- Military and defence sectors will remain major consumers of PMR technology, with a focus on encrypted, interoperable communications for global operations.
- The trend toward digital transformation across sectors like logistics, manufacturing, and transportation will accelerate the uptake of PMR solutions.
- Collaborative efforts between telecommunications companies and government agencies will drive the deployment of next-generation PMR systems.
- Increasing regulatory pressures for secure and interoperable communication solutions will create a favorable environment for PMR market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Mandated Secure Communication for Public Safety
Government regulations and initiatives require the deployment of secure, interoperable PMR systems for emergency services, ensuring reliable communication for first responders and driving widespread adoption across public safety agencies.
Technological Advancements in Digital PMR
The integration of digital technologies such as LTE and 5G into PMR systems enables real-time data, video, and GPS capabilities, significantly enhancing operational efficiency and expanding the use of PMR beyond traditional voice communication.
Expansion of Smart Cities and Industrial Digitalization
The rise of smart cities and the digital transformation of industries like utilities, transportation, and manufacturing are increasing the need for robust, secure, and integrated communication networks, fueling demand for advanced PMR solutions.
Growing Need for Reliable Communication in Hazardous and Remote Environments
Industries such as oil & gas, mining, and maritime require dependable PMR systems to ensure safety, coordination, and rapid emergency response in challenging operational settings, driving market growth in these sectors.
Regulatory Support and Standardization Efforts
International and regional regulatory bodies are establishing standards and frameworks for mission-critical communications, encouraging investment in modern PMR infrastructure and ensuring market expansion through compliance and interoperability.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Professional Mobile Radio (PMR) market?
What are the key drivers of the PMR market?
Which regions are leading the PMR market?
How is the Asia Pacific region contributing to the PMR market growth?
Which industries are adopting PMR solutions?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Public Safety (Police, Fire, Emergency Medical Services)
- 1.2.2 Transportation (Aviation, Maritime, Railways)
- 1.2.3 Utilities (Electricity, Water, Gas)
- 1.2.4 Defence (Military and Security)
- 1.2.5 Manufacturing and Industrial (Oil & Gas, Mining, Heavy Industries)
- 1.3 By Technology
- 1.3.1 Analog PMR Systems
- 1.3.2 Digital PMR Systems (TETRA, DMR, P25)
- 1.3.3 LTE-Integrated PMR Systems
- 1.3.4 5G-Integrated PMR Systems
- 1.4 By Product Type
- 1.4.1 Conventional PMR Systems
- 1.4.2 Trunked PMR Systems
- 1.4.3 Digital PMR Systems (TETRA, DMR, P25)
- 1.4.4 Hybrid PMR Systems
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 26,252.96 million → 2032: USD 71,288.18 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Professional Mobile Radio Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Professional Mobile Radio Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Professional Mobile Radio Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Professional Mobile Radio Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Professional Mobile Radio Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Professional Mobile Radio Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Professional Mobile Radio Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Professional Mobile Radio Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 26,252.96 million → 2032: USD 71,288.18 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Professional Mobile Radio Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Public Safety (Police, Fire, Emergency Medical Services)
- 12.3.7.2 Transportation (Aviation, Maritime, Railways)
- 12.3.7.3 Utilities (Electricity, Water, Gas)
- 12.3.7.4 Defence (Military and Security)
- 12.3.7.5 Manufacturing and Industrial (Oil & Gas, Mining, Heavy Industries)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Analog PMR Systems
- 12.4.7.2 Digital PMR Systems (TETRA, DMR, P25)
- 12.4.7.3 LTE-Integrated PMR Systems
- 12.4.7.4 5G-Integrated PMR Systems
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Conventional PMR Systems
- 12.5.7.2 Trunked PMR Systems
- 12.5.7.3 Digital PMR Systems (TETRA, DMR, P25)
- 12.5.7.4 Hybrid PMR Systems
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Professional Mobile Radio End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Professional Mobile Radio Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Professional Mobile Radio Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Professional Mobile Radio Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Motorola Solutions, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Hytera Communications Corporation Limited
- 18.4 Thales Group
- 18.5 JVC Kenwood Corporation
- 18.6 Sepura PLC
- 18.7 Tait Communications
- 18.8 Codan Radio Communications
- 18.9 Raytheon Company
- 18.10 Airbus Group
- 18.11 Simoco
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

