
Market Overview
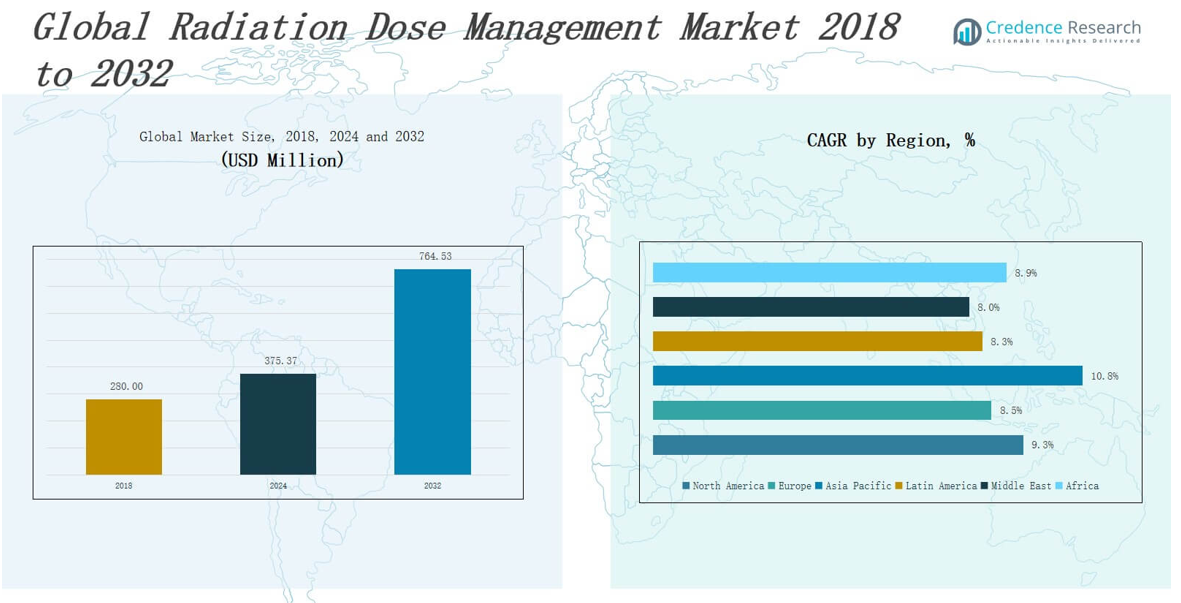
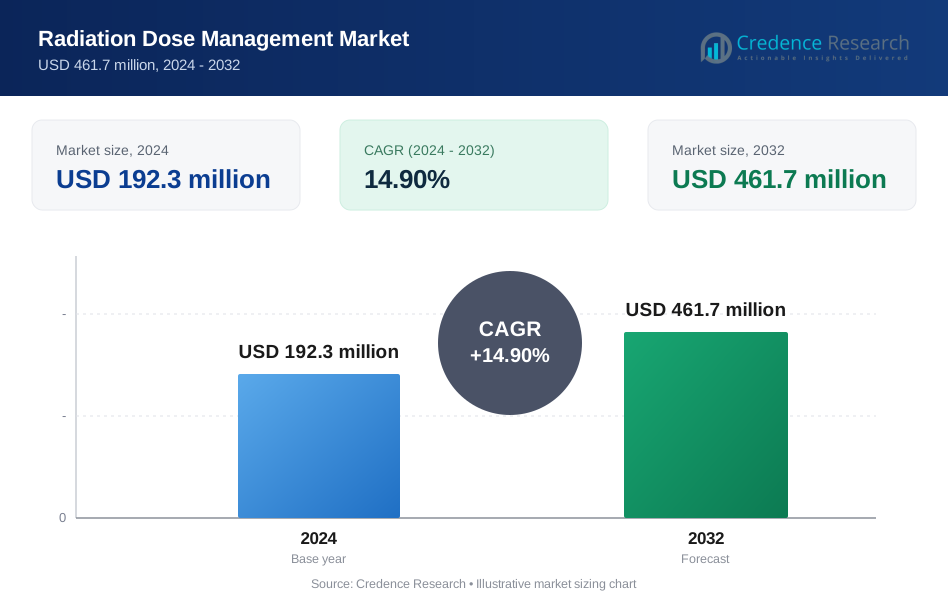
The Radiation Dose Management Market size was valued at USD 192.3 million in 2024 and is anticipated to reach USD 461.7 million by 2032, at a CAGR of 14.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Radiation Dose Management Market Size 2024 | USD 192.3 million |
| Radiation Dose Management Market, CAGR | 14.9% |
| Radiation Dose Management Market Size 2032 | USD 461.7 million |
The Radiation Dose Management Market is driven by increasing awareness of radiation-related health risks, stringent regulatory mandates, and the rising volume of diagnostic imaging procedures such as CT, PET, and fluoroscopy. Healthcare providers are adopting dose monitoring solutions to ensure patient safety, meet compliance requirements, and improve clinical outcomes. The shift toward value-based healthcare is encouraging the integration of advanced analytics and AI-powered platforms for real-time dose tracking and optimization. Growing emphasis on pediatric and cumulative dose management further boosts demand for sophisticated dose tracking systems. The market benefits from technological advancements in imaging modalities and software interfaces that support automated dose recording and reporting. Adoption is expanding in both developed and emerging markets as hospitals and imaging centers seek to enhance workflow efficiency, minimize liability risks, and adhere to accreditation standards. The integration of dose management tools with PACS and RIS platforms is a notable trend, facilitating seamless data interoperability and clinical decision support.
The Radiation Dose Management Market spans key regions including North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa. North America leads the market due to stringent regulations and advanced healthcare infrastructure, while Europe follows closely with strong compliance enforcement. Asia Pacific shows the fastest growth, driven by expanding diagnostic services and digital health investments. Latin America and the Middle East present moderate growth supported by modernization efforts, whereas Africa is gradually adopting dose monitoring through mobile and cloud-based solutions. Major players in the market include GE HealthCare, Siemens Healthineers, Philips Healthcare, Bayer AG, Fujifilm Holdings, Canon Medical Systems, Bracco Imaging, Qaelum NV, PACSHealth LLC, Agfa-Gevaert, and Radimetrics Inc. These companies compete on innovation, system integration, regulatory compliance, and service delivery across diverse healthcare ecosystems.
Market Insights
- The Radiation Dose Management Market is projected to grow from USD 192.3 million in 2024 to USD 461.7 million by 2032 in North America, driven by strict regulations, widespread CT and fluoroscopy usage, and rising demand for AI-powered and integrated software solutions.
- In Europe, valued at USD 158.9 million in 2024, the market is expanding to USD 379.2 million by 2032, supported by regulatory compliance, robust hospital infrastructure, and increasing adoption in Germany, France, and the UK.
- The Asia Pacific market, growing at the fastest CAGR of 10.29%, is fueled by healthcare digitization in China, India, and Japan, rising CT scan volumes, and growing demand for modular cloud-based systems in urban centers.
- Latin America is witnessing steady adoption, reaching USD 104.7 million by 2032, with Brazil and Mexico leading growth through regulatory mandates and increasing use of dose monitoring tools in academic hospitals.
- Middle East market growth is driven by expanding diagnostic services in Gulf countries, investments in health IT infrastructure, and strong demand for integrated platforms in tertiary care settings.
- Africa shows gradual progress, reaching USD 47.3 million by 2032, with growth centered in South Africa and Egypt, where mobile and cloud-based systems are being adopted to support basic safety protocols in radiography and CT.
- Major players include GE HealthCare, Siemens Healthineers, Philips Healthcare, Bayer AG, Canon Medical Systems, Bracco Imaging, Fujifilm Holdings, Qaelum NV, PACSHealth LLC, and Agfa-Gevaert, competing through innovation, AI capabilities, and regulatory-driven system integration.
Market Drivers
Rising Diagnostic Imaging Volumes and Patient Safety Concerns
The Radiation Dose Management Market is witnessing strong growth due to the increasing number of diagnostic imaging procedures such as CT scans, fluoroscopy, and nuclear medicine. These procedures, while essential, expose patients to ionizing radiation, raising concerns about long-term health effects. Hospitals and imaging centers are prioritizing radiation dose monitoring to enhance patient safety and reduce cumulative exposure risks. Regulatory agencies are reinforcing dose limits, prompting healthcare facilities to implement structured dose management protocols. It enables clinicians to make informed decisions by offering visibility into patient radiation histories and procedure trends. The market continues to expand with growing awareness among both clinicians and patients.
- For instance, Massachusetts General Hospital achieved a 40% reduction in pediatric CT scan doses after implementing real-time protocol adjustment tools, directly addressing concerns about cumulative radiation exposure in children.
Stringent Regulatory Mandates and Accreditation Requirements
The Radiation Dose Management Market is significantly influenced by regulatory frameworks established by organizations such as the Joint Commission, FDA, and European Commission. These bodies mandate dose recording, tracking, and reporting as part of compliance and patient safety initiatives. Healthcare institutions are under pressure to meet these requirements to maintain accreditation and avoid penalties. Dose management systems offer robust tools that support automated compliance documentation and audit readiness. Integration with electronic health records ensures seamless data capture and retrieval for inspections and clinical reviews. It helps streamline operational efficiency while maintaining transparency and accountability across radiology departments.
- For instance, GE Healthcare’s DoseWatch system enables hospitals to monitor and manage radiation and contrast exposure across all imaging devices, providing automated alerts and comprehensive analytics to ensure adherence to regulatory limits and facilitate audit readiness.
Technological Advancements in Dose Monitoring Solutions
Advances in software platforms and imaging technologies are transforming the capabilities of the Radiation Dose Management Market. AI-powered analytics, cloud-based dashboards, and automated alerts are enhancing the accuracy and responsiveness of dose tracking. These tools enable personalized radiation dose optimization based on patient demographics and procedural specifics. Vendors are innovating with modular systems that integrate with PACS, RIS, and modality equipment. The ability to deliver real-time feedback during procedures empowers radiologists to adjust protocols dynamically. It is driving adoption among high-volume imaging centers and multi-specialty hospitals aiming to balance diagnostic quality with radiation safety.
Growing Emphasis on Pediatric and Chronic Patient Monitoring
The Radiation Dose Management Market is increasingly focused on vulnerable populations, especially pediatric and chronically ill patients who require frequent imaging. Repeated exposure heightens the risk of radiation-induced complications, making dose monitoring essential in long-term care. Pediatric protocols demand customized solutions with lower thresholds and enhanced tracking sensitivity. Institutions are investing in systems that allow cumulative dose analysis across departments and timeframes. It supports more informed clinical decisions and long-term treatment planning. The trend aligns with precision medicine goals and is accelerating system-wide implementation of dose management platforms.
Market Trends
Integration of Dose Management with Enterprise Imaging Systems
The Radiation Dose Management Market is experiencing a growing trend toward integration with enterprise imaging systems such as PACS, RIS, and EHR platforms. Healthcare providers are seeking centralized solutions that streamline imaging workflows and ensure consistent radiation dose documentation across departments. Interoperable platforms allow seamless access to dose records, enhance audit readiness, and support clinical decision-making. This trend improves data accuracy and fosters collaboration between radiologists, technicians, and administrative staff. Vendors are prioritizing compatibility with multi-vendor imaging environments to expand market reach. It enables healthcare systems to standardize protocols and reduce data silos while improving efficiency.
- For instance, Sectra has integrated its dose management solution with both PACS and EHR systems, enabling reject analysis of high-dose images and giving referring physicians direct access to a patient’s dose history, which supports alternative diagnostic decisions for patients who have already received significant radiation exposure.
Shift Toward Cloud-Based and AI-Enabled Platforms
The market is witnessing increased adoption of cloud-based radiation dose management systems that offer scalability, remote access, and data analytics capabilities. Healthcare organizations are leveraging these platforms to track patient exposure in real time and across multiple sites. AI-enabled tools can detect outliers, recommend optimized scanning protocols, and generate automated alerts for abnormal doses. These technologies reduce manual intervention and enhance response times during critical procedures. The Radiation Dose Management Market benefits from the improved accuracy and predictive insights that cloud and AI solutions offer. It supports healthcare systems in achieving operational efficiency and regulatory compliance.
- For instance, Philips DoseWise Portal is a web-based solution that enables healthcare providers to monitor radiation doses across multiple imaging modalities, supporting personalized dosing and improved workflow documentation.
Personalized Dose Optimization Based on Patient-Specific Parameters
A key trend in the Radiation Dose Management Market is the emphasis on personalized dose optimization tailored to patient size, age, and medical history. Institutions are implementing smart protocols that adapt imaging parameters to reduce unnecessary exposure. Advanced systems now factor in previous imaging records to manage cumulative dose and guide future procedures. This approach aligns with precision medicine and elevates patient care standards. Vendors are enhancing their platforms with customizable dose reference levels. It allows clinicians to balance diagnostic quality with radiation safety in real-time, reducing long-term health risks.
Increased Focus on Pediatric and Geriatric Imaging Protocols
Healthcare providers are increasingly adopting specialized radiation dose management protocols for pediatric and geriatric populations, where exposure sensitivity is higher. These groups often require modified scanning techniques and rigorous monitoring to prevent adverse effects. Vendors are responding by offering dedicated features such as pediatric dose calculators and geriatric-specific safety thresholds. The Radiation Dose Management Market is adapting to demand for solutions that accommodate vulnerable populations. It drives innovation in dose reduction technologies and promotes safer diagnostic practices. This trend strengthens the market’s relevance in value-based care environments and multidisciplinary care pathways.
Market Challenges Analysis
High Implementation Costs and Infrastructure Limitations
The Radiation Dose Management Market faces challenges related to the high initial cost of system implementation, integration, and maintenance. Smaller healthcare facilities and diagnostic centers often struggle to justify the investment due to limited budgets and lower imaging volumes. The need for compatible hardware, software upgrades, and trained personnel further increases the financial burden. In developing regions, outdated imaging equipment and inadequate IT infrastructure hinder the adoption of dose management solutions. It limits market penetration despite increasing awareness of radiation safety. Vendors must address affordability and offer scalable models to broaden accessibility.
Data Integration and Workflow Compatibility Issues
Seamless integration of dose management platforms with existing hospital systems remains a significant challenge for the Radiation Dose Management Market. Variability in imaging equipment vendors and legacy software environments complicates interoperability. Inconsistent data formats and lack of standardized protocols create difficulties in real-time dose tracking and cross-department data sharing. Workflow disruptions during system deployment can delay clinical operations and reduce staff productivity. It requires tailored implementation strategies and ongoing technical support to ensure smooth adoption. Addressing these integration barriers is critical to realizing the full potential of dose management technologies.
Market Opportunities
Expansion in Emerging Markets and Rural Healthcare Networks
The Radiation Dose Management Market holds significant growth potential in emerging economies where diagnostic imaging volumes are rising steadily. Governments are investing in healthcare infrastructure and prioritizing patient safety, creating a favorable environment for dose management adoption. Rural healthcare networks are expanding access to imaging services, driving demand for affordable, scalable monitoring solutions. Vendors can capitalize on this opportunity by offering cloud-based platforms and modular systems tailored to resource-constrained settings. It enables broader market reach while addressing critical gaps in radiation safety compliance. Strategic partnerships with public health agencies and NGOs can accelerate market entry.
Rising Demand for AI-Driven Analytics and Decision Support Tools
Healthcare providers are increasingly seeking intelligent systems that go beyond dose recording to offer actionable insights and support clinical decisions. The Radiation Dose Management Market is well-positioned to benefit from AI-driven analytics that identify trends, predict high-risk scenarios, and guide protocol adjustments. Integration of machine learning tools can enhance workflow automation, reduce human error, and improve patient outcomes. Hospitals are willing to invest in advanced platforms that provide long-term clinical and operational value. It creates a strong incentive for vendors to develop feature-rich solutions with predictive and preventive capabilities. Demand for such tools will grow with the shift toward precision imaging and personalized care.
Market Segmentation Analysis:
By Component
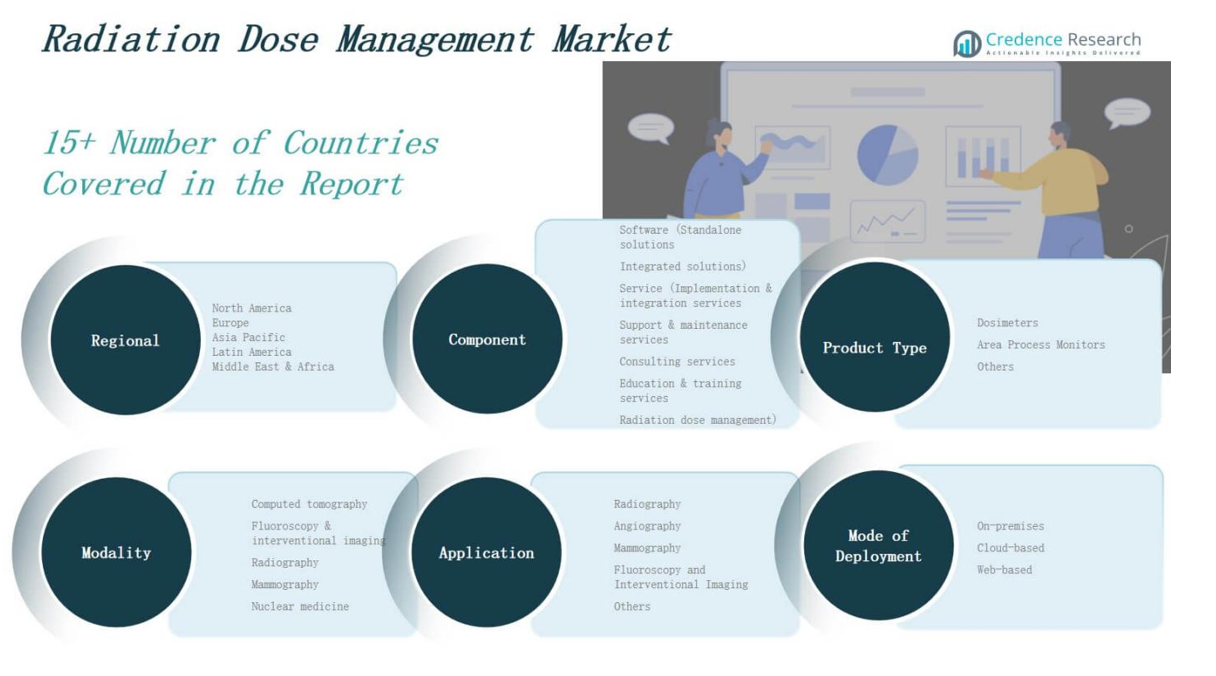
The Radiation Dose Management Market is segmented into software and services. The software segment includes standalone and integrated solutions, with integrated platforms gaining traction due to seamless workflow integration with PACS and RIS. Standalone systems are used in smaller facilities with limited integration needs. The service segment covers implementation & integration, support & maintenance, consulting, and education & training services. Demand for implementation and support services is rising as healthcare institutions prioritize efficient deployment and operational continuity.
- For instance, Epic’s partnership with Bayer’s Radimetrics embeds automated dose alerts into patient records, which helped UC San Diego Health reduce duplicate imaging by 18% within six months by triggering warnings when cumulative exposure nears 80% of annual thresholds.
By Product Type
The Radiation Dose Management Market includes dosimeters, area process monitors, and others. Dosimeters dominate the segment, driven by their critical role in tracking individual radiation exposure for patients and medical staff. Area process monitors are essential for maintaining safe radiation environments in diagnostic and interventional imaging zones. The others category comprises accessory tools and technologies that support radiation detection and monitoring functions. This segmentation reflects the growing demand for both personal and environmental radiation safety mechanisms.
- For instance, Siemens Healthineers provides electronic personal dosimeters widely used in hospitals to monitor real-time radiation exposure for radiology staff, ensuring compliance with safety regulations and minimizing occupational risks.
By Modality
Based on modality, the Radiation Dose Management Market covers computed tomography (CT), fluoroscopy & interventional imaging, radiography, mammography, and nuclear medicine. CT remains the leading segment due to its high radiation dose levels and widespread diagnostic use. Fluoroscopy and interventional imaging follow closely, requiring real-time dose tracking. Radiography and mammography emphasize safety in routine and screening procedures, while nuclear medicine is gaining importance in cumulative dose monitoring. It reflects a shift toward procedure-specific dose optimization across modalities.
Segments:
Based on Component
Software
- Standalone Solutions
- Integrated Solutions
Service
- Implementation & Integration Services
- Support & Maintenance Services
- Consulting Services
- Education & Training Services
Based on Product Type
- Dosimeters
- Area Process Monitors
- Others
Based on Modality
- Computed Tomography (CT)
- Fluoroscopy & Interventional Imaging
- Radiography
- Mammography
- Nuclear Medicine
Based on Application
- Radiography
- Angiography
- Mammography
- Fluoroscopy and Interventional Imaging
- Others
Based on Mode of Deployment
- On-premises
- Cloud-based
- Web-based
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
The North America Radiation Dose Management Market size was valued at USD 130.5 million in 2018 to USD 192.3 million in 2024 and is anticipated to reach USD 461.7 million by 2032, at a CAGR of 9.76% during the forecast period. North America holds the largest market share, driven by the high adoption of diagnostic imaging technologies, robust healthcare infrastructure, and stringent radiation safety regulations. The United States contributes the majority share due to government mandates from bodies like the FDA and The Joint Commission. Hospitals and imaging centers across the region are integrating dose management solutions into enterprise imaging systems. The software segment, particularly integrated solutions, leads adoption. CT and fluoroscopy remain dominant modalities in this region due to procedural volume. The Radiation Dose Management Market in North America continues to grow with expanding demand for cloud-based platforms and AI-enabled analytics.
Europe
The Europe Radiation Dose Management Market size was valued at USD 105.8 million in 2018 to USD 158.9 million in 2024 and is anticipated to reach USD 379.2 million by 2032, at a CAGR of 9.54% during the forecast period. Europe maintains a strong position in the market, supported by regulatory enforcement under the European Basic Safety Standards Directive. Countries like Germany, France, and the UK are leading adoption due to well-established radiology networks. Hospitals are investing in comprehensive dose monitoring systems to meet compliance and improve patient safety. The demand for consulting and integration services is also high across public and private institutions. CT and radiography are key modalities driving usage. The Radiation Dose Management Market in Europe benefits from cross-country research collaborations and harmonized safety initiatives.
Asia Pacific
The Asia Pacific Radiation Dose Management Market size was valued at USD 72.4 million in 2018 to USD 118.2 million in 2024 and is anticipated to reach USD 303.6 million by 2032, at a CAGR of 10.29% during the forecast period. Asia Pacific is the fastest-growing regional market, driven by rapid expansion of diagnostic imaging services and growing healthcare investments in countries like China, Japan, and India. Demand for cost-effective, cloud-based, and modular software solutions is rising, particularly in urban hospitals and diagnostic chains. CT remains the most widely used modality due to its diagnostic versatility, while mammography is growing in cancer screening programs. The service segment is expanding as healthcare institutions require support for integration and education. The Radiation Dose Management Market in Asia Pacific is gaining momentum with government-backed digital health initiatives and local vendor collaborations.
Latin America
The Latin America Radiation Dose Management Market size was valued at USD 28.6 million in 2018 to USD 44.3 million in 2024 and is anticipated to reach USD 104.7 million by 2032, at a CAGR of 9.53% during the forecast period. Latin America presents moderate growth, led by Brazil and Mexico, where public and private hospitals are gradually modernizing imaging practices. Regulatory pressure is increasing around dose documentation and reporting standards. Adoption of software remains limited to urban centers, with integrated solutions gaining traction in teaching hospitals. Dosimeters and area process monitors are critical in large healthcare networks and academic facilities. CT and fluoroscopy lead modality-based deployment. The Radiation Dose Management Market in Latin America is growing steadily with vendor-led training programs and telehealth expansion.
Middle East
The Middle East Radiation Dose Management Market size was valued at USD 21.3 million in 2018 to USD 33.8 million in 2024 and is anticipated to reach USD 79.1 million by 2032, at a CAGR of 9.87% during the forecast period. The Middle East market is expanding due to increased diagnostic imaging procedures in Gulf countries and investments in health IT infrastructure. Government health authorities are promoting radiation safety awareness and funding modern radiology departments. Integrated software systems are preferred in large multispecialty hospitals across the UAE and Saudi Arabia. Fluoroscopy and CT are the dominant modalities, often linked with cardiology and emergency care. Implementation services and user training programs are crucial to overcome technical skill gaps. The Radiation Dose Management Market in the Middle East is advancing with regional partnerships and hospital accreditation initiatives.
Africa
The Africa Radiation Dose Management Market size was valued at USD 13.4 million in 2018 to USD 20.5 million in 2024 and is anticipated to reach USD 47.3 million by 2032, at a CAGR of 9.15% during the forecast period. Africa shows emerging potential, though limited by underdeveloped healthcare infrastructure and low imaging penetration outside major cities. South Africa leads the regional market, followed by Egypt, where public hospitals are digitizing radiology workflows. Cloud-based dose management systems offer a viable path due to lower setup costs. The dosimeter segment dominates, focusing on basic patient and occupational safety. Radiography and CT are the most common imaging modalities. The Radiation Dose Management Market in Africa is evolving slowly but steadily with international aid programs and mobile imaging units supporting rural deployment.
Key Player Analysis
- Bayer AG(Germany)
- Sectra AB(Sweden)
- GE HealthCare(USA)
- Philips Healthcare(Netherlands)
- Siemens Healthineers(Germany)
- Fujifilm Holdings Corporation(Japan)
- Canon Medical Systems Corporation(Japan)
- Bracco Imaging S.p.A.(Italy)
- PACSHealth LLC(USA)
- Qaelum NV(Belgium)
- Radimetrics Inc.(Canada)
- Agfa-Gevaert Group(Belgium)
- MedicVision Imaging Solutions Ltd.(Israel)
- Infinitt Healthcare(South Korea)
- Novarad Corporation(USA)
- Imalogix, LLC(USA)
- L3Harris Technologies(USA)
- Thermo Fisher Scientific(USA)
- Lumen Technologies, Inc.(USA)
Competitive Analysis
The Radiation Dose Management Market features a competitive landscape marked by the presence of leading global players and emerging solution providers. Key companies such as GE HealthCare, Siemens Healthineers, Philips Healthcare, and Bayer AG focus on integrated platforms that combine dose tracking with enterprise imaging systems. These players invest heavily in AI-based analytics, cloud-based deployment models, and user-friendly interfaces. Niche vendors like Qaelum NV and PACSHealth LLC offer specialized solutions tailored to mid-sized hospitals and diagnostic centers. Partnerships with healthcare institutions and software integrations with PACS and RIS platforms form the foundation of most growth strategies. The market favors innovation, compliance support, and interoperability, placing emphasis on fast implementation and scalability. It rewards vendors that provide a combination of robust technical capabilities, regulatory support, and strong after-sales services. Competitive dynamics are shifting toward subscription-based models and regional customization to meet the evolving demands of healthcare providers across diverse markets.
Recent Developments
- In June 2025, Thermo Fisher Scientific secured a USD 94.5 million contract from the U.S. Department of Defense to deliver next-generation dosimetry systems and advanced radiation health database management software.
- In 2024, AstraZeneca announced the acquisition of Fusion Pharmaceuticals Inc., strengthening its position in the radiopharmaceutical and radiation dose management sector.
- In May 2025, Varian (a Siemens Healthineers company) and Siemens presented integrated MRI-in-radiotherapy solutions, including RapidArc Dynamic and AI-powered imaging workflows at ESTRO 2025.
Market Concentration & Characteristics
The Radiation Dose Management Market exhibits moderate to high market concentration, with a few global players dominating the competitive landscape. Companies such as GE HealthCare, Siemens Healthineers, Philips Healthcare, and Bayer AG lead the market through comprehensive product portfolios and strong integration capabilities. It is characterized by a growing preference for interoperable, AI-driven, and cloud-based systems that support regulatory compliance and workflow optimization. The market favors vendors offering scalable, modular solutions adaptable to different healthcare infrastructures. Innovation, regulatory expertise, and customer support remain key differentiators. The market also sees increasing collaboration between technology providers and healthcare institutions to enhance platform customization and deployment. Demand for real-time analytics, pediatric safety tools, and cumulative dose tracking is shaping product development strategies. While mature markets like North America and Europe are focused on platform enhancement, emerging regions present opportunities through affordable solutions and service-based models. It continues to evolve toward automation, integration, and clinical decision support.
Report Coverage
The research report offers an in-depth analysis based on Component, Product Type, Modality, Application, Mode of Deployment and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for integrated radiation dose management systems will rise as hospitals continue digitizing imaging workflows.
- AI and machine learning will play a greater role in real-time dose optimization and risk prediction.
- Cloud-based deployment models will become more common, offering scalability and cost-efficiency for mid-sized facilities.
- Pediatric and chronic patient monitoring will gain more focus, driving need for customized dose tracking protocols.
- Vendors will expand partnerships with PACS and RIS providers to enhance interoperability and workflow integration.
- Regulatory compliance will remain a key driver, influencing system upgrades and new installations.
- Emerging markets will present new opportunities due to healthcare infrastructure development and diagnostic expansion.
- Mobile and remote dose management solutions will gain traction in rural and under-resourced regions.
- Consulting and training services will grow as institutions seek help with implementation and compliance readiness.
- Innovation in user-friendly interfaces and automation will improve adoption across multi-specialty hospitals.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Radiation Dose Management Market?
What are the key segments within the Radiation Dose Management Market?
What are some challenges faced by the Radiation Dose Management Market?
Who are the major players in the Radiation Dose Management Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Radiation Dose Management Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Radiation Dose Management Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 192.3 million → 2032: USD 461.7 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Radiation Dose Management Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Radiation Dose Management Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Radiation Dose Management Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Radiation Dose Management Market Drivers
- 3.3 Radiation Dose Management Market Restraints & Challenges
- 3.4 Radiation Dose Management Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Radiation Dose Management Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Radiation Dose Management Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Radiation Dose Management category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Radiation Dose Management Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Radiation Dose Management Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Radiation Dose Management. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Radiation Dose Management Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Radiation Dose Management Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Radiation Dose Management Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Radiation Dose Management (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Radiation Dose Management
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Radiation Dose Management Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Radiation Dose Management Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Radiation Dose Management Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Radiation Dose Management Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Radiation Dose Management Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Radiation Dose Management Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Radiation Dose Management Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Radiation Dose Management Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
