
Market Overviews
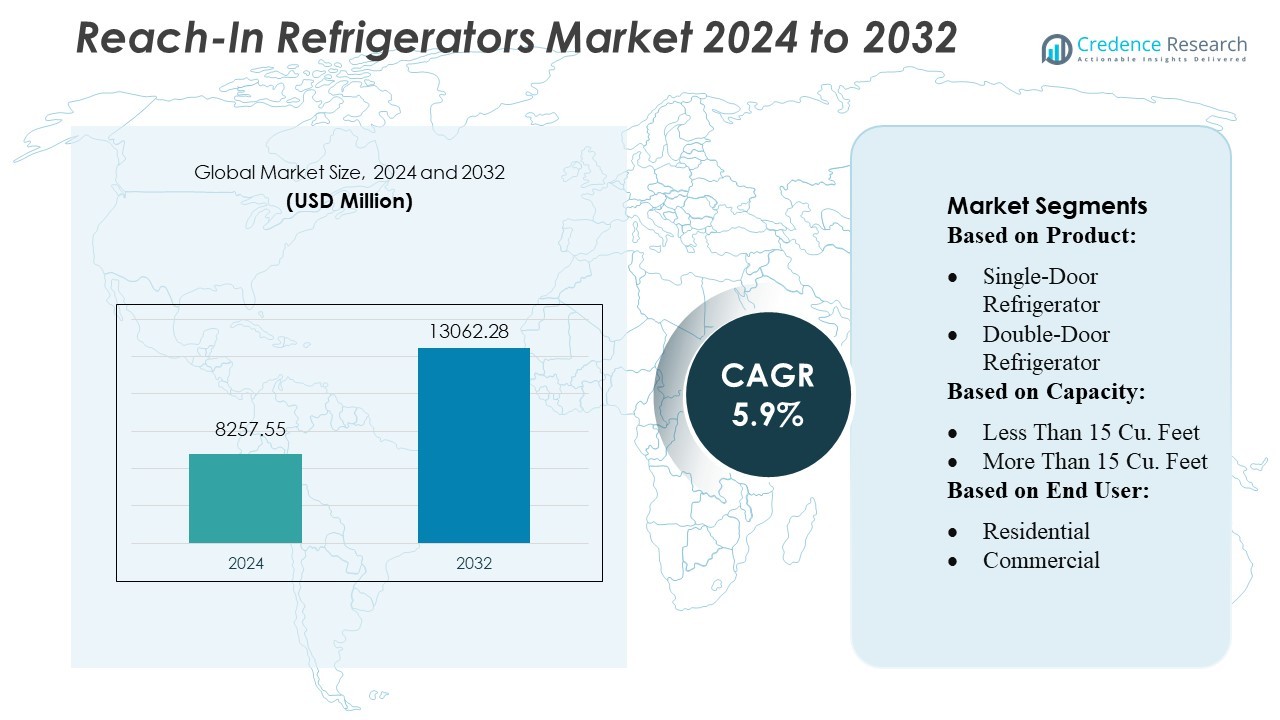
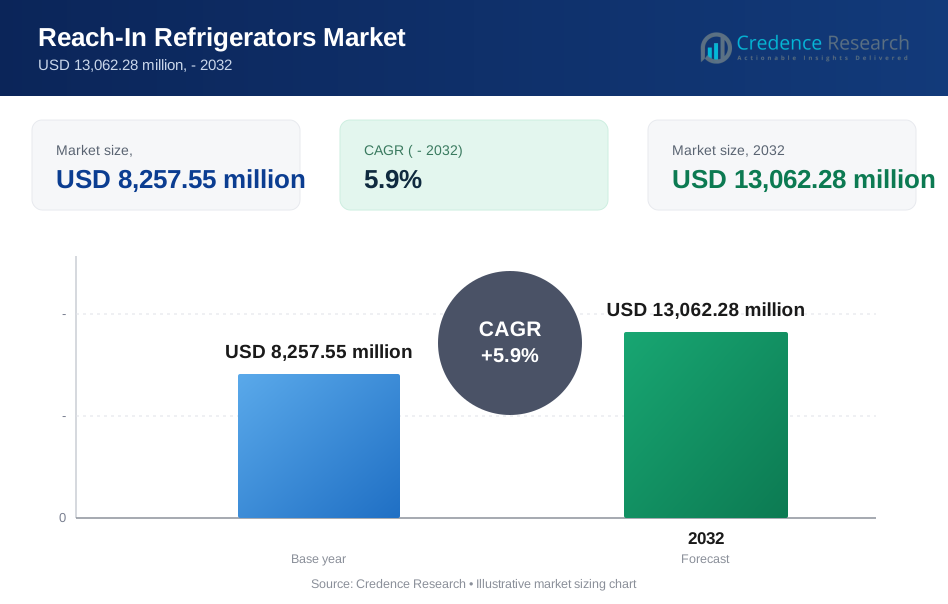
Reach‑In Refrigerators Market size was valued USD 8257.55 million in 2024 and is anticipated to reach USD 13062.28 million by 2032, at a CAGR of 5.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Reach‑In Refrigerators Market Size 2024 | USD 8257.55 Million |
| Reach‑In Refrigerators Market, CAGR | 5.9% |
| Reach‑In Refrigerators Market Size 2032 | USD 13062.28 Million |
The reach-in refrigerators market is dominated by a group of leading global manufacturers, including Illinois Tool Works Inc., Ali Group, Daikin Industries Ltd., Lennox International Inc., Carrier, Hussmann Corporation, Johnson Control, Dover Corporation, Electrolux AB, and AHT Cooling Systems GmbH. These companies compete aggressively across innovation, sustainability, and service excellence, offering energy-efficient compressors, smart connectivity, and modular designs. Geographically, North America emerges as the leading region, capturing approximately 35 % of the global market, driven by its developed foodservice infrastructure, stringent energy and safety standards, and high penetration of advanced refrigeration solutions.
Market Insights
- The Reach-In Refrigerators Market reached USD 8257.55 million in 2024 and is projected to reach USD 13062.28 million by 2032, expanding at a 5.9% CAGR, supported by increasing demand across foodservice, retail, and institutional applications.
- Rising focus on energy-efficient and smart refrigeration systems drives market growth as operators prioritize reduced operational costs, sustainability compliance, and real-time performance monitoring.
- Competitive intensity remains high, with global players advancing eco-friendly refrigerants, modular designs, and connected cooling technologies to strengthen product differentiation and service capabilities.
- High initial investment, maintenance costs, and regulatory compliance challenges act as restraints, particularly for small businesses and price-sensitive markets.
- Regionally, North America leads with around 35% share, supported by advanced foodservice infrastructure, while the commercial segment holds the largest application share, driven by strong demand from restaurants, hotels, and supermarkets.
Market Segmentation Analysis:
By Product
Single-door refrigerators dominate the reach-in refrigerator market, capturing the largest share due to their compact design, lower energy consumption, and suitability for small commercial kitchens and space-constrained retail environments. Demand remains strong as foodservice operators prioritize cost-efficient storage solutions that support frequent access and consistent cooling. Their widespread adoption is driven by ease of installation, reduced maintenance requirements, and compatibility with standardized kitchen layouts. Meanwhile, double-door and multi-door models gain traction in high-volume operations, yet single-door units remain the preferred choice for balancing capacity, efficiency, and operational flexibility.
- For instance, Ali Group, Beverage-Air and Victory Refrigeration transitioned their entire self-contained reach-in line to R290 refrigerant, eliminating HFCs in foam and refrigerant, while achieving up to 25% energy savings in their adaptive units.
By Capacity
The segment with more than 15 cu. feet holds the dominant market share, supported by the rising need for high-capacity cold storage in commercial foodservice, hospitality, and large retail establishments. Operators increasingly invest in larger units to minimize restocking frequency, maintain temperature stability, and support diversified product storage. These models also benefit from improved energy-efficient compressors and advanced insulation technologies that enhance performance without significantly raising operational costs. Although units below 15 cu. feet serve small businesses and residential needs, the higher-capacity category leads due to its ability to meet intensive, multi-product storage demands.
- For instance, Daikin’s multi-compressor racks (CM series) Capacities range from 9.5 kW to approximately 66 kW. Low-temperature applications: Capacities range from 3.5 kW to approximately 49 kW.
By End User
The commercial end-user segment accounts for the highest market share, fueled by expanding foodservice businesses, quick-service restaurants, and convenience stores that rely on reach-in refrigerators for reliable, high-volume cooling solutions. Commercial operators prioritize durability, larger storage capacity, and advanced temperature-control features that support continuous operation. Growth is further driven by stricter food safety regulations requiring stable refrigeration environments. While residential usage is increasing with premium kitchen upgrades and larger household storage preferences, the commercial sector remains dominant as businesses scale operations and require robust, long-lasting refrigeration systems.
Key Growth Drivers
- Rising Demand from Foodservice and Hospitality Sector
The rapid expansion of restaurants, quick-service chains, and cloud kitchens drives strong adoption of reach-in refrigerators. Operators prioritize equipment that ensures food safety, enables faster food preparation, and supports continuous cooling in high-volume environments. Energy-efficient models with digital temperature control and enhanced storage flexibility strengthen purchasing decisions. The growing presence of international hospitality brands and increased catering activities further accelerate installations. As commercial kitchens scale their operations, they increasingly rely on durable and high-capacity reach-in units to maintain consistent cooling performance and reduce inventory spoilage.
- For instance, Lennox’s refrigeration division — Heatcraft, a part of Lennox International — is developing commercial refrigeration equipment using Honeywell Solstice L40X (R-455A), a low-GWP refrigerant with a GWP below 150, as confirmed in a Lennox-Heatcraft / Honeywell press release.
- Advancements in Energy-Efficient Refrigeration Technologies
Manufacturers are integrating improved insulation, variable-speed compressors, and advanced refrigerants to reduce operational costs and meet regulatory energy standards. These innovations enhance cooling uniformity while lowering overall energy consumption, making modern units more attractive for both commercial and residential buyers. Smart sensors, adaptive defrost systems, and intelligent diagnostics further optimize performance. With stricter sustainability mandates and rising electricity prices, businesses increasingly upgrade to energy-efficient reach-in refrigerators to achieve long-term savings, reduce carbon footprints, and enhance equipment reliability across diverse operating conditions.
- For instance, Carrier Commercial Refrigeration’s CO₂OLtec® CO₂ efficiency booster skid can reduce energy consumption by up to 10 % compared to conventional CO₂ booster systems, according to Carrier’s own press release.
- Growth of Packaged Food, Cold-Chain Expansion, and Urban Retail
The increasing consumption of packaged foods, ready-to-serve meals, and perishable items fuels demand for efficient refrigeration across supermarkets, convenience stores, and specialty food outlets. Urbanization and modernization of retail infrastructure strengthen requirements for advanced cooling storage solutions. Concurrently, expanding cold-chain networks create more touchpoints for equipment deployment across distribution hubs and retail formats. As retailers focus on maintaining product quality and minimizing waste, reach-in refrigerators become essential for standardized temperature control, product visibility, and efficient inventory management.
Key Trends & Opportunities
1. Growing Adoption of Smart and Connected Refrigeration
IoT-enabled reach-in refrigerators with remote monitoring, predictive maintenance alerts, and real-time temperature tracking are gaining momentum. Operators benefit from improved asset management, reduced downtime, and enhanced food safety compliance. Cloud-based platforms allow multi-site businesses to centralize performance oversight, enabling data-driven decisions for energy optimization and maintenance scheduling. As digital transformation accelerates across foodservice and retail industries, connected refrigeration presents significant opportunities for manufacturers to differentiate offerings and develop value-added service models.
- For instance, Hussmann’s StoreConnect® IoT platform collects continuous data via embedded analytics running 24/7/365 across connected racks and cases. According to Hussmann, this system uses predictive insights on defrost cycles, superheat, refrigerant leaks.
2. Rising Use of Eco-Friendly Refrigerants and Sustainable Materials
Increasing environmental regulations encourage broader replacement of traditional refrigerants with low-GWP alternatives such as R290. This transition drives manufacturers to redesign systems with improved heat-exchange efficiency and eco-friendly insulation materials. Opportunities emerge for brands offering sustainable, recyclable components and reduced-emission production processes. As buyers prioritize green procurement standards, suppliers capable of demonstrating environmental compliance and sustainability certifications gain a competitive advantage. This trend also supports the introduction of long-lifespan equipment designed to minimize environmental impact throughout its lifecycle.
- For instance, Johnson Controls has selected R-454B, a lower-global-warming-potential (GWP) refrigerant, to replace R-410A in its ducted residential and commercial unitary products; R-454B has a GWP of 466, which is only one-fifth that of R-410A.
3. Growing Penetration of Reach-In Refrigerators in Residential Use
Premium households increasingly adopt reach-in refrigerators for their large storage capacity, advanced temperature management, and superior durability compared to traditional household units. The rise of home-based catering, bulk food storage, and organized home kitchens further stimulates residential demand. Stylish designs, quiet operation, and features such as dual-zone temperature control make these units appealing to high-income consumers. Manufacturers can tap into this emerging segment by offering compact, aesthetically refined models that blend commercial durability with residential convenience.
Key Challenges
1. High Initial Investment and Maintenance Costs
Despite strong functionality, high acquisition costs and ongoing maintenance expenses remain a major barrier for small restaurants, local retailers, and household buyers. Advanced components, specialized refrigerants, and strict installation requirements increase total ownership costs. Frequent servicing, especially for heavy-duty commercial use, adds further financial pressure. Budget-constrained operators often delay equipment upgrades or opt for lower-cost alternatives, limiting market penetration. Manufacturers need to focus on cost-optimized models and flexible financing solutions to broaden adoption.
2. Compliance with Stringent Energy and Environmental Regulations
Regulations governing energy efficiency, refrigerant usage, and emission control require manufacturers to continuously upgrade product designs, which increases development costs and slows time-to-market. Adapting to shifting global, regional, and national policies adds operational complexity, especially for companies with extensive distribution networks. Ensuring compliance while maintaining performance and durability can be technically challenging. These regulatory pressures may also increase product prices, affecting customer purchase decisions. Companies must invest in R&D and modular designs to navigate ongoing regulatory transitions.
Regional Analysis
North America
North America holds about 35% of the reach-in refrigerators market, supported by a well-developed foodservice industry and strict food-safety standards. Restaurants, supermarkets, and institutional kitchens drive consistent demand for energy-efficient and high-capacity units. The region also leads in adopting smart, connected refrigeration systems used for remote monitoring and maintenance. Frequent equipment upgrades and strong preference for sustainable refrigerants further strengthen market penetration. The U.S. remains the largest contributor, followed by Canada, with both markets benefiting from strong distribution networks and high commercial kitchen investments.
Asia Pacific
Asia Pacific accounts for roughly 32% of the market and continues to grow rapidly due to urbanization, rising incomes, and expansion of foodservice chains. Countries like China, India, and Japan see increasing demand driven by modern retail, cloud kitchens, and cold-chain improvements. The region also benefits from local manufacturing, which makes products more accessible and cost-efficient. Adoption of energy-saving models is rising as governments promote environmentally responsible refrigeration. Asia Pacific remains the most dynamic region, offering strong opportunities for both international and domestic suppliers.
Europe
Europe captures about 24% of the global reach-in refrigerators market, driven by strong regulations that encourage use of energy-efficient and low-emission refrigeration. Foodservice chains, hotels, and retail outlets across Germany, France, the UK, and Italy are major adopters. The region prioritizes sustainable cooling technologies and equipment that supports connected monitoring. Demand is also supported by the hospitality sector’s focus on reducing electricity consumption and meeting environmental compliance requirements. Europe's preference for durable and high-quality equipment continues to drive stable market growth.
Latin America
Latin America holds about 5% of the market, with growth supported by the expansion of supermarkets, convenience stores, and quick-service restaurants. Countries such as Brazil and Mexico drive most of the demand, though economic fluctuations and cost sensitivity limit rapid adoption. Modernization of food retail and improvements in cold-chain infrastructure are gradually increasing demand for reach-in refrigerators. Manufacturers focusing on affordable, durable, and energy-efficient models find strong opportunities in this region.
Middle East & Africa
The Middle East & Africa region accounts for roughly 4% of the market, supported by growing hospitality networks, rising retail development, and increasing investments in healthcare facilities. GCC countries, especially the UAE and Saudi Arabia, lead demand due to expanding hotels and foodservice establishments. Harsh climatic conditions make reliable refrigeration essential, while energy-efficient models gain popularity to reduce operating costs. Despite logistical challenges and import dependency, the region shows steady adoption of commercial reach-in units.
Market Segmentations:
By Product:
- Single-Door Refrigerator
- Double-Door Refrigerator
By Capacity:
- Less Than 15 Cu. Feet
- More Than 15 Cu. Feet
By End User:
- Residential
- Commercial
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The reach-in refrigerators market features a competitive landscape led by major global companies such as Illinois Tool Works Inc., Ali Group, Daikin Industries Ltd., Lennox International Inc., Carrier, Hussmann Corporation, Johnson Control, Dover Corporation, Electrolux AB, and AHT Cooling Systems GmbH. The reach-in refrigerators market is shaped by global manufacturers that focus on technological innovation, energy efficiency, and sustainability-driven product development. Companies compete by expanding their portfolios with smart, connected cooling systems that offer precise temperature control, predictive maintenance, and improved operational reliability. The market also sees strong emphasis on eco-friendly refrigerants, advanced compressor technologies, and durable materials that reduce lifecycle costs. Strategic initiatives such as product line diversification, regional expansion, and enhanced after-sales service capabilities strengthen market positioning. As foodservice, retail, and institutional sectors modernize, competition intensifies around performance optimization, design flexibility, and regulatory compliance.
Key Player Analysis
- Illinois Tool Works Inc.
- Ali Group
- Daikin Industries Ltd.
- Lennox International Inc.
- Carrier
- Hussmann Corporation
- Johnson Control
- Dover Corporation
- Electrolux AB
- AHT Cooling Systems GmbH
Recent Developments
- In May 2025, AHT Cooling Systems GmbH introduced SPI CIRCUMPOLAR, a patented modular pump station for semi-plug-in water-loop refrigeration systems. This innovation enhances flexibility, scalability, and integration in the commercial refrigeration equipment industry, driving sustainability and efficiency improvements.
- In May 2025, Hussmann Corporation signed an exclusive distribution partnership with Lithuanian manufacturer Refra to offer transcritical CO₂ racks and R290 heat pump solutions across Australia and New Zealand, expanding its natural‑refrigerant portfolio.
- In March 2025, Phoenix Energy Technologies and Hussmann Corporation announced a strategic partnership to launch Refrigeration IQ, an AI-driven solution to improve the efficiency of refrigeration systems. The partnership combines Phoenix's AI platform with Hussmann's automated leak detection to monitor asset health and reduce refrigerant leaks in facilities like grocery stores.
- In February 2025, Daikin launched the Pro‑C CRAH range, new computer room air handlers delivering 30-210 kW cooling, optimized controls, and modular architecture to boost efficiency in data center refrigeration applications.
Report Coverage
The research report offers an in-depth analysis based on Product, Capacity, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue advancing energy-efficient technologies as regulations tighten and customers prioritize reduced operating costs.
- Adoption of smart, connected refrigeration systems will rise as operators seek real-time monitoring and predictive maintenance.
- Demand for eco-friendly refrigerants will grow as manufacturers transition toward low-GWP alternatives to meet sustainability goals.
- Foodservice expansion, including cloud kitchens and quick-service chains, will drive steady installations of high-capacity reach-in units.
- Retail modernization and growth in packaged food consumption will strengthen demand for reliable commercial refrigeration.
- Manufacturers will increasingly design modular and service-friendly units to reduce downtime and extend equipment life cycles.
- Residential adoption of premium reach-in units will rise as consumers seek larger storage and professional-grade performance.
- Cold-chain development in emerging markets will expand opportunities for commercial refrigeration suppliers.
- The market will see greater integration of IoT analytics to optimize energy usage and improve operational visibility.
- Competitive differentiation will focus on sustainability, product durability, and advanced temperature-control features.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Reach-In Refrigerators Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Reach-In Refrigerators Market projected to grow between 2025 and 2032?
Which Reach-In Refrigerators Market segment held the largest share in 2024?
Which Freezer segment governs the demand for Reach-in Refrigerators in the world?
Who are the leading companies in the Reach-In Refrigerators Market?
Which region commanded the largest share of the Reach-In Refrigerators Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Reach-In Refrigerators Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Reach-In Refrigerators Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (2032) (base year: USD 8,257.55 million → 2032: USD 13,062.28 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Reach-In Refrigerators Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Reach-In Refrigerators Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Reach-In Refrigerators Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Reach-In Refrigerators Market Drivers
- 3.3 Reach-In Refrigerators Market Restraints & Challenges
- 3.4 Reach-In Refrigerators Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Reach-In Refrigerators Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Reach-In Refrigerators Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Reach-In Refrigerators category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Reach-In Refrigerators Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Reach-In Refrigerators Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Reach-In Refrigerators market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Reach-In Refrigerators Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Reach-In Refrigerators Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Reach-In Refrigerators Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Reach-In Refrigerators (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Reach-In Refrigerators Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Reach-In Refrigerators Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & 2032)
- 7.1.2 Channel Mix Evolution (2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Reach-In Refrigerators Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Reach-In Refrigerators Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Reach-In Refrigerators Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Reach-In Refrigerators Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Reach-In Refrigerators Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Reach-In Refrigerators Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Reach-In Refrigerators Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
