
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
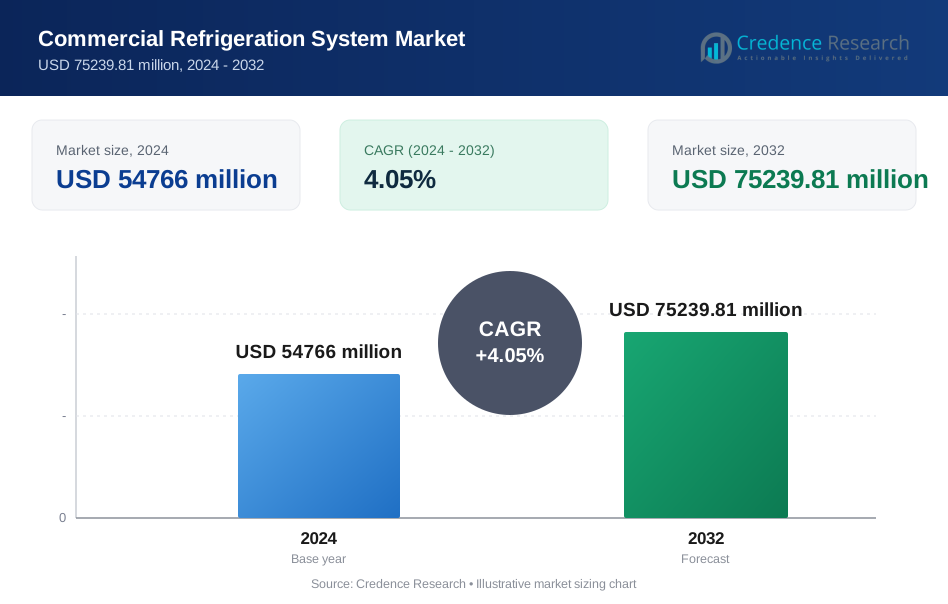
| Commercial Refrigeration system Market Size 2024 | USD 54766 million |
| Commercial Refrigeration System Market, CAGR | 4.05% |
| Commercial Refrigeration System Market Size 2032 | USD 75239.81 million |
Market Overview:
The Global Commercial Refrigeration system is projected to grow from USD 54766 million in 2024 to USD 75239.81 million by 2032, expanding at a CAGR of 4.05% from 2024 to 2032.
This growth trajectory is propelled by several key factors that are reshaping the industry landscape. The expanding food and beverage sector, coupled with increasing consumer demand for frozen and chilled products, serves as a primary driver for market expansion. Stringent food safety regulations across various regions further necessitate advanced refrigeration solutions, pushing businesses to invest in modern, compliant systems. Technological advancements play a crucial role in market development, with a focus on energy-efficient compressors and eco-friendly refrigerants. These innovations not only reduce operational costs but also address growing environmental concerns, aligning with global sustainability initiatives. The proliferation of supermarket and hypermarket chains, along with the burgeoning trend of online grocery shopping, amplifies the need for sophisticated refrigeration infrastructure. This trend is particularly evident in emerging markets, where the development of reliable cold storage and transportation networks is catalyzing market growth and fostering innovation among key players.
Regionally, North America leads the market, driven by strict food safety standards and high consumption of frozen and chilled products. The region's advanced retail sector and early adoption of innovative technologies contribute to its market dominance. Europe follows closely, with its market growth fuelled by sustainability-focused regulations and continuous advancements in refrigeration technology. The Asia-Pacific region demonstrates robust growth potential, propelled by rapid urbanization, an expanding middle class, and significant investments in food retail infrastructure.
Key players such as Carrier Global Corporation, Danfoss, and Emerson Electric Co. are at the forefront of market expansion, driving innovation in energy-efficient and environmentally friendly refrigeration solutions. These companies are investing heavily in research and development to meet evolving customer needs and regulatory requirements. Emerging markets in Latin America and Africa present promising opportunities for market growth, driven by increasing industrialization, improving cold chain logistics, and rising consumer demand for perishable goods. As these regions develop their food retail and distribution networks, the demand for commercial refrigeration systems is expected to surge.
The market is also witnessing a shift towards smart refrigeration systems, incorporating IoT technology for remote monitoring and predictive maintenance. This trend is expected to gain momentum, offering enhanced operational efficiency and reduced downtime for businesses across various sectors, from food retail to healthcare and pharmaceuticals.
As the industry evolves, manufacturers are focusing on developing modular and customizable refrigeration solutions to cater to diverse business needs, further driving market expansion and innovation in the coming years.
Market Drivers:
Expanding Food and Beverage Industry:
The expanding food and beverage industry stand as a primary driver, projected to account for approximately 40% of the market by 2024. This sector's growth is fueled by increasing consumption of frozen and chilled products, as well as the rapid expansion of supermarket and hypermarket chains. For instance, the rise of convenience foods and ready-to-eat meals has led to a surge in demand for advanced refrigeration systems capable of maintaining optimal temperature conditions for a diverse range of products. Supermarkets are increasingly investing in sophisticated refrigeration solutions to ensure product freshness and extend shelf life, thereby reducing food waste and improving profitability.
Technological Advancements in Refrigeration:
Technological advancements in refrigeration are another crucial factor, expected to constitute about 25% of the market by 2024. Innovations such as energy-efficient compressors, smart refrigeration systems, and the adoption of eco-friendly refrigerants are revolutionizing the industry. For instance, the development of CO2-based refrigeration systems offers a more environmentally friendly alternative to traditional HFC refrigerants, aligning with global sustainability goals. Additionally, the integration of IoT technology in refrigeration systems allows for real-time monitoring and predictive maintenance, significantly enhancing operational efficiency and reducing downtime for businesses across various sectors.
Rise of Online Grocery Shopping:
The rise of online grocery shopping is set to drive around 20% of the market by 2024, reflecting the growing need for reliable cold storage and transportation solutions in e-commerce logistics. For instance, major online retailers are investing heavily in refrigerated warehouses and delivery vehicles equipped with advanced cooling systems to ensure the integrity of perishable goods throughout the supply chain. This trend has accelerated the development of modular and flexible refrigeration solutions that can adapt to the dynamic needs of e-commerce fulfilment centres.
Growth in Hospitality and Healthcare Sectors:
Growth in the hospitality and healthcare sectors is projected to contribute approximately 15% of the market demand by 2024. These sectors require specialized refrigeration solutions for various applications. For instance, hotels and restaurants are adopting energy-efficient refrigeration systems to store ingredients and prepared foods, while also showcasing products in visually appealing display cases. In the healthcare sector, hospitals and pharmaceutical companies rely on precise temperature-controlled environments for storing sensitive medications and biological samples. For example, the development of ultra-low temperature freezers capable of maintaining temperatures as low as -86°C has become crucial for storing COVID-19 vaccines, highlighting the critical role of advanced refrigeration technology in public health initiatives. As these drivers continue to shape the commercial refrigeration system market, manufacturers and businesses are adapting to meet evolving demands. The industry is witnessing a shift towards more sustainable, efficient, and technologically advanced refrigeration solutions that cater to the specific needs of various sectors while addressing environmental concerns and regulatory requirements.
Market Trends:
Emphasis on Energy Efficiency and Eco-Friendly Refrigerants:
The global commercial refrigeration system market is experiencing a significant shift towards energy efficiency and eco-friendly refrigerants, with this trend expected to account for approximately 35% of the market by 2024. This transformation is driven by stringent regulatory policies aimed at reducing greenhouse gas emissions and increasing environmental consciousness among consumers and businesses alike. For instance, the European Union's F-Gas Regulation and the U.S. Environmental Protection Agency's Significant New Alternatives Policy (SNAP) program are pushing manufacturers to develop systems that utilize natural refrigerants such as CO2, ammonia, and hydrocarbons. These refrigerants have substantially lower global warming potential compared to traditional hydrofluorocarbons (HFCs). Industry leaders like Danfoss and Emerson Electric Co. are at the forefront of this trend, introducing cutting-edge compressors and refrigeration technologies that not only comply with environmental regulations but also offer significant energy savings. For example, Danfoss' CO2 adaptive liquid management (CALM) solution has demonstrated energy savings of up to 10% in supermarket refrigeration systems. Similarly, Emerson's Copeland Scroll™ compressors for CO2 applications have shown efficiency improvements of up to 30% compared to traditional systems.
Growth of the Cold Chain Logistics Sector:
The growth of the cold chain logistics sector is another major trend driving the commercial refrigeration system market, projected to represent about 25% of the market by 2024. This expansion is fuelled by the increasing global demand for perishable goods, including food, pharmaceuticals, and biologics, which require consistent temperature control throughout the supply chain. This trend is particularly pronounced in emerging economies where improvements in logistics infrastructure are critical to meet the growing consumption of fresh and frozen products. For example, in India, the government has launched the Integrated Cold Chain and Value Addition Infrastructure scheme to reduce post-harvest losses and improve the supply chain for perishable goods. This initiative is expected to drive significant investments in cold storage facilities and refrigerated transportation.
Market Segmentation Analysis:
By Product Type
The commercial refrigeration system market can be segmented based on product types into refrigerators and freezers, transportation refrigeration, display cases, beverage refrigeration, and walk-in coolers. Refrigerators and freezers are essential in food service, supermarkets, and convenience stores for preserving perishable goods. The growing trend towards fresh and frozen food consumption significantly drives this segment. Transportation refrigeration systems are crucial for maintaining the integrity of temperature-sensitive products during transit, vital for the food and pharmaceutical industries. Display cases, widely used in retail environments, enhance product visibility and appeal, promoting sales of chilled products. Beverage refrigeration, including coolers and dispensers, is indispensable in the hospitality and retail sectors, ensuring beverages are served at optimal temperatures. Walk-in coolers provide large-scale, customizable cooling solutions for warehouses, restaurants, and large retailers, meeting the demand for high-volume, efficient storage.
By Refrigerant Type
The commercial refrigeration system market is also segmented based on refrigerant types, including traditional refrigerants such as hydrofluorocarbons (HFCs) and natural refrigerants like carbon dioxide (CO2), ammonia (NH3), and hydrocarbons (HCs). Traditional refrigerants have been widely used due to their effective cooling properties; however, their high global warming potential (GWP) has led to increasing regulatory pressures and a shift towards more sustainable alternatives. Natural refrigerants are gaining traction due to their lower environmental impact and compliance with stringent environmental regulations. CO2-based systems, known for their efficiency and safety, are becoming more popular in supermarkets and large-scale refrigeration applications. Ammonia is favoured in industrial applications for its excellent thermodynamic properties, while hydrocarbons like propane and isobutane are used in smaller systems and new generation refrigeration units due to their low GWP and high efficiency. This shift towards natural refrigerants is driven by both regulatory mandates and growing corporate responsibility towards environmental sustainability.
Segmentation:
Based on Product Type
- Refrigerator & Freezer
- Transportation Refrigeration
- Refrigerated Display Cases
- Beverage Refrigeration
- Ice Cream Merchandiser
- Refrigerated Vending Machine
Based on Refrigerant Type
- Fluorocarbons
- Hydrocarbons
- Inorganics
Based on Application
- Hotels & Restaurants
- Supermarkets & Hypermarkets
- Convenience
Based on Region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America
In North America, the commercial refrigeration system market is experiencing significant growth driven by increasing demand from the food and beverage industry. The United States leads this market due to its advanced technological infrastructure and the presence of major market players. Retail giants such as Walmart and Costco are investing heavily in energy-efficient refrigeration solutions to meet stringent environmental regulations and reduce operational costs. The trend towards sustainable and eco-friendly refrigeration systems is prominent in this region. The introduction of new refrigerants with lower Global Warming Potential (GWP) and the implementation of advanced cooling technologies, such as CO2 transcritical systems, are gaining traction. Government incentives and policies aimed at reducing carbon footprints are further accelerating the adoption of these innovative refrigeration solutions.
Asia-Pacific
The Asia-Pacific region is witnessing rapid expansion in the commercial refrigeration system market, primarily fuelled by the burgeoning retail and hospitality sectors in emerging economies such as China and India. The rise in disposable incomes, urbanization, and the growth of organized retail chains contribute significantly to this demand. Supermarkets and hypermarkets are expanding their presence, necessitating the installation of sophisticated refrigeration systems to preserve perishable goods. Technological advancements and the adoption of smart refrigeration systems are also notable trends in this region. IoT-enabled refrigeration units that allow for remote monitoring and predictive maintenance are becoming increasingly popular. This technological shift not only improves operational efficiency but also reduces energy consumption and maintenance costs. Additionally, local manufacturers are focusing on developing cost-effective and energy-efficient refrigeration solutions to cater to the diverse needs of the region’s rapidly growing market.
Key Players:
- Daikin
- Johnson Controls
- Carrier
- Dover
- Baltimore Aircoil Company
- Blue Star Limited
- De Rigo Refrigeration
- Fogel
- Hussmann
- Imbera
Competitive Analysis:
The global commercial refrigeration system market is characterized by intense competition among key players such as Carrier, Daikin, Panasonic (Hussmann Corporation), Danfoss, and Epta Group. These companies are engaged in strategic initiatives to enhance their market positions, including investments in research and development to introduce energy-efficient and environmentally friendly systems. Mergers and acquisitions are common, enabling players to expand their product portfolios and global reach. Additionally, companies focus on improving distribution networks and after-sales services to enhance customer experience. Technological advancements, such as the integration of IoT for monitoring and control, are driving innovation in the market to meet stringent environmental regulations and changing customer demands. The competitive landscape is dynamic, with players vying to offer custom refrigeration solutions tailored to specific industry needs, reflecting a shift towards specialized and efficient systems.
Recent Developments:
- November 2023: Whirlpool Corporationintroduced SlimTech insulation, a vacuum-insulated structure (VIS) technology, in their refrigerators. According to the company, this technology represents a significant transformation in refrigeration technologies.
- September 2023: Carrierpartnered with Relayr, Inc., an industrial Internet of Things (IIoT) technology company, to offer an innovative Refrigeration-as-a-Service (RaaS) solution for customers. This collaboration aims to help food retailers avoid the upfront investment required for refrigeration equipment and infrastructure.
- March 2023: Carrierlaunched the Transicold EverFRESH active controlled atmosphere system for refrigerated containers. This software development enables transporters to carry a wide range of perishable goods, including high-value products.
- February 2023: Carrierintroduced a Carbon Air Purifier with UV in their Healthy Homes portfolio. This product provides air purification to help reduce unwanted odors, volatile organic compounds, and common household gases from indoor air.
- January 2023: Daikin Industries, Ltd.invested in Atomis Co., Ltd., a company originating from Kyoto University. Atomis is involved in developing innovative functional materials using “metal-organic frameworks (MOFs).” This investment by Daikin aims to develop next-generation refrigerants and environmentally friendly equipment.
Market Concentration & Characteristics:
The commercial refrigeration system market exhibits moderate market concentration, with prominent players such as Carrier, Daikin, and Emerson Electric holding substantial market shares. These industry leaders drive innovation through the development of energy-efficient, IoT-enabled, and environmentally friendly refrigeration solutions. The market is characterized by stringent environmental regulations, a strong focus on sustainability, and the adoption of advanced technologies to enhance system efficiency and reliability. Strategic partnerships, technological advancements, and a growing demand for customizable and modular refrigeration systems further define the competitive landscape, reflecting the market's adaptability to changing regulatory and consumer demands.
Report Coverage:
The research report offers an in-depth analysis based on Product type, Refrigerant type, Applications and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increased adoption of energy-efficient and environmentally friendly refrigeration systems to meet stringent regulations and reduce operational costs.
- Growing integration of IoT and smart technologies for remote monitoring, predictive maintenance, and optimized performance of refrigeration units.
- Rising demand for modular and customizable refrigeration solutions to accommodate diverse business needs and space constraints.
- Expansion of cold chain logistics to support e-commerce growth and increased demand for fresh and frozen food products.
- Continued shift towards natural refrigerants like CO2, ammonia, and hydrocarbons to minimize environmental impact.
- Enhanced focus on food safety and quality, driving innovations in temperature control and monitoring systems.
- Increased implementation of advanced insulation materials and design techniques to improve energy efficiency and reduce heat loss.
- Growing demand for refrigeration systems with lower noise levels and compact designs, especially in urban areas.
- Rise in retrofitting and upgrading of existing refrigeration systems to improve efficiency and comply with new regulations.
- Emergence of AI-powered refrigeration management systems for optimized energy consumption and inventory control.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expanding Food and Beverage Industry
The rapid growth of the food and beverage sector, including supermarkets, hypermarkets, and convenience food outlets, is driving demand for advanced commercial refrigeration systems to ensure product freshness, safety, and extended shelf life.
Stringent Food Safety and Environmental Regulations
Increasingly strict regulations regarding food safety and the reduction of greenhouse gas emissions are compelling businesses to invest in modern, compliant refrigeration solutions that utilize eco-friendly refrigerants and energy-efficient technologies.
Technological Advancements and Smart Refrigeration
Innovations such as IoT-enabled monitoring, energy-efficient compressors, and the adoption of natural refrigerants are transforming the market, enabling predictive maintenance, reduced operational costs, and improved system reliability.
Growth of Cold Chain Logistics and E-Commerce
The surge in online grocery shopping and the need for reliable cold storage and transportation solutions are fueling investments in modular and flexible refrigeration infrastructure, particularly to support the integrity of perishable goods throughout the supply chain.
Expansion in Hospitality and Healthcare Sectors
Hotels, restaurants, and healthcare facilities are increasingly adopting specialized refrigeration systems to meet diverse storage needs, from food ingredients to pharmaceuticals, further boosting market demand.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Commercial Refrigeration system?
What factors are driving the growth of the Commercial Refrigeration system?
What are the key segments within the Commercial Refrigeration system?
Who are the major players in the Commercial Refrigeration system?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Hotels & Restaurants
- 1.2.2 Supermarkets & Hypermarkets
- 1.2.3 Convenience Stores
- 1.3 By Product Type
- 1.3.1 Refrigerator & Freezer
- 1.3.2 Transportation Refrigeration
- 1.3.3 Refrigerated Display Cases
- 1.3.4 Beverage Refrigeration
- 1.3.5 Ice Cream Merchandiser
- 1.3.6 Refrigerated Vending Machine
- 1.4 By Refrigerant Type
- 1.4.1 Fluorocarbons
- 1.4.2 Hydrocarbons
- 1.4.3 Inorganics
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 54766 million → 2032: USD 75239.81 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Commercial Refrigeration System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Commercial Refrigeration System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Commercial Refrigeration System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Commercial Refrigeration System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Commercial Refrigeration System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Commercial Refrigeration System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Commercial Refrigeration System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Commercial Refrigeration System Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 54766 million → 2032: USD 75239.81 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Commercial Refrigeration System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hotels & Restaurants
- 12.3.7.2 Supermarkets & Hypermarkets
- 12.3.7.3 Convenience Stores
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Refrigerator & Freezer
- 12.4.7.2 Transportation Refrigeration
- 12.4.7.3 Refrigerated Display Cases
- 12.4.7.4 Beverage Refrigeration
- 12.4.7.5 Ice Cream Merchandiser
- 12.4.7.6 Refrigerated Vending Machine
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Refrigerant Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Fluorocarbons
- 12.5.7.2 Hydrocarbons
- 12.5.7.3 Inorganics
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Commercial Refrigeration System End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Commercial Refrigeration System Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Commercial Refrigeration System Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Commercial Refrigeration System Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Carrier Global Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Daikin Industries, Ltd.
- 18.4 Johnson Controls
- 18.5 Danfoss
- 18.6 Emerson Electric Co.
- 18.7 Dover Corporation
- 18.8 Baltimore Aircoil Company
- 18.9 Blue Star Limited
- 18.10 Hussmann Corporation (Panasonic)
- 18.11 Epta Group
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

