
Market Overview
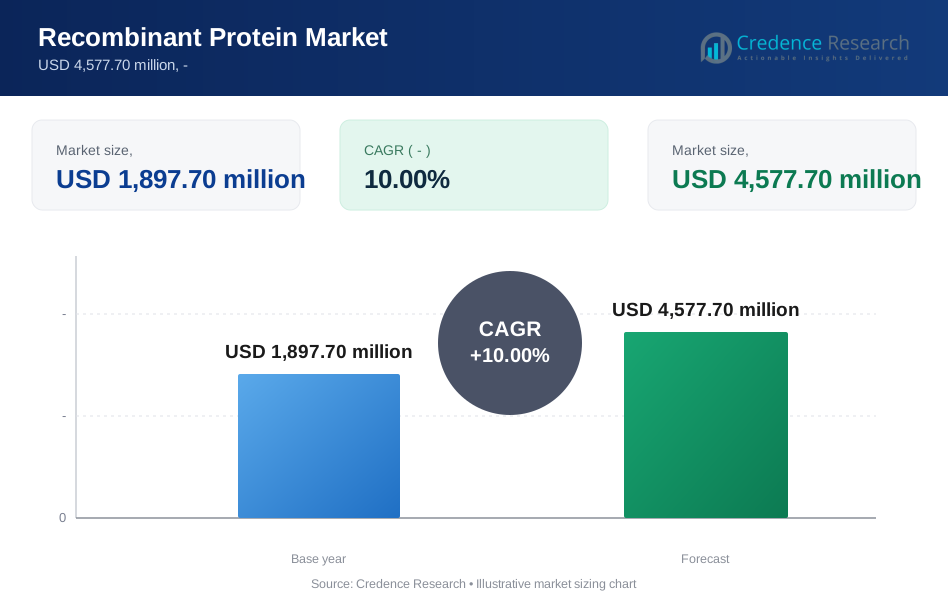
The global market for recombinant protein has seen remarkable growth in recent years, reaching a value of $1,897.70 million USD in 2023 and projected to surge to $4,577.70 million USD by 2032, with a steady Compound Annual Growth Rate (CAGR) of 10%. This growth is primarily fueled by advancements in biotechnology and increasing demand across various industries, including pharmaceuticals and biotechnology.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Recombinant Protein Market Size 2023 | USD 1,897.70 Million |
| Recombinant Protein Market, CAGR | 10% |
| Recombinant Protein Market Size 2032 | USD 4,577.70 Million |
One of the main drivers behind this growth is the rising demand for biopharmaceuticals, where recombinant proteins play a vital role. These proteins are essential for producing biologic drugs, offering advantages such as higher efficacy and fewer side effects compared to traditional medications. Moreover, ongoing technological advancements are improving the efficiency and scalability of recombinant protein production, making these therapies more accessible and cost-effective.
While North America currently leads the market, with a strong biopharmaceutical industry and research infrastructure, the Asia-Pacific region is poised for significant growth. Factors such as increasing investments in healthcare infrastructure and a growing biotechnology sector contribute to this potential. Overall, the future of the
Market Drivers
Growing Demand for Biopharmaceuticals
The market for recombinant proteins is being primarily driven by the increasing demand for biopharmaceuticals across various therapeutic areas. Biopharmaceuticals, including recombinant proteins, offer significant advantages over traditional small molecule drugs, such as higher specificity, reduced side effects, and enhanced efficacy. With advancements in biotechnology and genetic engineering techniques, the production of recombinant proteins has become more efficient and cost-effective. This growing demand for biopharmaceuticals is fueling the expansion of the recombinant protein market, as pharmaceutical companies invest in research and development to meet the needs of patients worldwide.
Technological Advancements in Protein Engineering
Technological advancements in protein engineering have revolutionized the production and customization of recombinant proteins, further propelling market growth. Novel techniques, such as gene editing tools like CRISPR-Cas9, have facilitated precise modifications to protein structures, enabling the development of therapeutically relevant proteins with improved functionalities. Additionally, innovations in expression systems and protein purification technologies have streamlined the manufacturing process, resulting in higher yields and purity of recombinant proteins. These advancements have expanded the scope of applications for recombinant proteins beyond traditional pharmaceuticals, into areas such as diagnostics, research reagents, and industrial enzymes.
Rising Incidence of Chronic Diseases
The escalating prevalence of chronic diseases, including cancer, diabetes, and autoimmune disorders, is driving the demand for innovative therapeutic solutions, thus stimulating the growth of the recombinant protein market. Recombinant proteins play a crucial role in the treatment of various chronic conditions by targeting specific disease pathways and modulating biological processes. As the global burden of chronic diseases continues to rise, there is a growing need for biologics-based therapies, driving pharmaceutical companies to invest in the development of recombinant protein therapeutics to address unmet medical needs and improve patient outcomes.
Increasing Investments in Biotechnology Research and Development
The growing investments in biotechnology research and development by both public and private sectors are significantly contributing to the expansion of the recombinant protein market. Government initiatives aimed at fostering innovation in biotechnology and providing funding support for biopharmaceutical research have created a favorable environment for the development of novel recombinant protein therapeutics. Moreover, collaborations between academic institutions, research organizations, and pharmaceutical companies are facilitating knowledge exchange and technology transfer, accelerating the discovery and development of new recombinant protein-based drugs.
Expanding Applications in Personalized Medicine
Advancements in genomic medicine and personalized therapies are driving the adoption of recombinant proteins in the field of personalized medicine, further stimulating market growth. Recombinant proteins can be engineered to target specific molecular pathways associated with individual genetic profiles, allowing for tailored treatment approaches based on patients' unique characteristics. This personalized approach enhances treatment efficacy and reduces adverse effects, leading to improved clinical outcomes. With the increasing emphasis on precision medicine and the integration of biomarker-driven therapies into clinical practice, the demand for customized recombinant protein therapeutics is expected to continue to rise, driving further expansion of the market.
Key Segmentation
By Product:
- Therapeutic Proteins
- Monoclonal Antibodies
- Cytokines
- Growth Factors
- Hormones
- Enzymes
- Fusion Proteins
- Industrial Proteins
- Enzymes (for industrial processes)
- Biofuels
- Biopolymers
- Others
- Research Proteins
- GFP (Green Fluorescent Protein)
- Histidine-Tagged Proteins
- Others
By Users:
- Pharmaceutical & Biotechnology Companies
- Academic & Research Institutions
- Contract Research Organizations (CROs)
- Contract Manufacturing Organizations (CMOs)
- Others
By Application:
- Therapeutics
- Oncology
- Autoimmune Diseases
- Infectious Diseases
- Metabolic Disorders
- Others
By Research
- Drug Discovery & Development
- Genomics & Proteomics
- Cell Culture
- Others
By Industrial
- Food & Beverages
- Agriculture
- Environmental
- Others
By Region:
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- Saudi Arabia
- South Africa
- Rest of Middle East & Africa
Market Trends
Advancements in Gene Editing Technologies:
The emergence of CRISPR-Cas9 and other gene editing technologies has significantly enhanced the precision and efficiency of recombinant protein production. These tools enable targeted modifications in host cell lines to optimize protein expression levels, improve product quality, and facilitate the production of complex proteins with post-translational modifications.
Cell-Free Protein Synthesis Systems:
Cell-free protein synthesis (CFPS) systems offer an alternative approach to traditional cell-based expression systems. CFPS systems utilize cellular machinery extracted from cells to synthesize proteins outside of living cells. This trend is gaining momentum due to its flexibility, scalability, and ability to produce toxic or membrane-bound proteins. Additionally, CFPS systems allow rapid prototyping and facilitate the production of proteins in non-traditional hosts.
Integration of Artificial Intelligence (AI) and Machine Learning (ML):
AI and ML algorithms are increasingly being employed to optimize recombinant protein production processes. These technologies analyze vast datasets to predict protein expression levels, identify optimal expression conditions, and design synthetic genes for enhanced protein yield and functionality. Integration of AI and ML streamlines the protein engineering workflow, accelerates process development, and reduces production costs.
Expansion of Novel Expression Hosts:
Traditional expression hosts such as Escherichia coli, yeast, and mammalian cells continue to dominate recombinant protein production. However, there is a growing interest in exploring novel expression hosts, including insect cells, algae, and plant-based systems. These alternative hosts offer unique advantages such as enhanced protein folding, assembly of complex protein structures, and the ability to produce glycosylated proteins, widening the scope of recombinant protein applications.
Multi-Modal Purification Strategies:
Purification of recombinant proteins remains a critical bottleneck in the production process. To address this challenge, multi-modal purification strategies combining affinity chromatography, ion exchange chromatography, and size exclusion chromatography are gaining traction. These integrated purification platforms offer higher purity, yield, and process robustness, thereby reducing production costs and accelerating time-to-market for recombinant protein therapeutics.
Focus on Sustainable Production Practices:
With increasing emphasis on sustainability and environmental stewardship, there is a growing demand for sustainable recombinant protein production practices. This includes the use of renewable feedstocks, optimization of fermentation processes to minimize energy consumption and waste generation, and implementation of green bioprocessing technologies. Sustainable production practices not only reduce the ecological footprint of recombinant protein production but also align with corporate social responsibility goals.
Restraints and Challenges
- The market for recombinant proteins, driven by their widespread applications in therapeutics, diagnostics, and research, faces several significant restraints and challenges. Understanding and addressing these hurdles are crucial for stakeholders to navigate the evolving landscape effectively.
- One of the foremost challenges in the market pertains to the complexities associated with protein expression and purification. Recombinant protein production often involves intricate processes, including selecting suitable expression systems, optimizing culture conditions, and purifying the desired protein. These procedures can be time-consuming, resource-intensive, and prone to variability, posing obstacles to achieving consistent product quality and scalability.
- Furthermore, the inherent heterogeneity of recombinant proteins presents a notable restraint. Variability in post-translational modifications, such as glycosylation, phosphorylation, and disulfide bond formation, can influence protein structure, stability, and function. Ensuring uniformity in these attributes across production batches remains a persistent challenge, impacting product efficacy and regulatory compliance.
- Another critical restraint lies in the regulatory landscape governing recombinant protein therapeutics. Stringent regulatory requirements, particularly in terms of safety, efficacy, and manufacturing standards, impose rigorous hurdles for product development and commercialization. Navigating the complex regulatory pathways demands substantial investments of time, resources, and expertise, thereby prolonging the time-to-market and increasing development costs.
- Moreover, the market for recombinant proteins is susceptible to competitive pressures stemming from alternative technologies and products. Emerging platforms, such as cell-free protein synthesis and gene editing techniques, offer potential advantages in terms of speed, flexibility, and cost-effectiveness. Additionally, biosimilar competition poses a significant threat, especially for established recombinant protein therapeutics nearing patent expiry, exerting downward pressure on prices and market share.
- Supply chain vulnerabilities represent another notable challenge for the recombinant protein market. Reliance on intricate bioprocessing infrastructure, including fermentation facilities and purification technologies, exposes the supply chain to disruptions, such as equipment failures, raw material shortages, and logistical issues. Ensuring robustness and resilience in the supply chain is imperative to mitigate risks of product shortages and meet market demand reliably.
- Furthermore, economic considerations, including pricing pressures and reimbursement challenges, hinder market growth and profitability. Healthcare systems worldwide face escalating costs and budgetary constraints, prompting payers to exert pressure on drug pricing and reimbursement policies. Achieving a balance between affordability and profitability poses a delicate balancing act for manufacturers, necessitating strategic pricing strategies and value-based reimbursement models.
Regional Analysis
- In the North American region, the United States commands the lion's share of the market, holding approximately 35% of the global market share for recombinant proteins. Canada contributes around 5% to the North American market share, indicating its significant but relatively smaller presence in comparison to its southern neighbor.
- Turning to Europe, Germany leads with approximately 15% of the global market share for recombinant proteins. Switzerland closely follows, holding around 10% of the market share. The United Kingdom contributes around 5%, adding to the region's overall influence in the global market. Collectively, these European countries hold a substantial 30% share of the global recombinant protein market.
Recent Developments
Key players
- Thermo Fisher Scientific
- Merck & Co., Inc.
- Novo Nordisk
- Lonza Group
- Bio-Rad Laboratories
- Abcam
- CellGenix GmbH
- ProSpec-Tany TechnoGene Ltd.
- R&D Systems (a Bio-Techne brand)
Future Outlook
- Market Expansion: The global recombinant protein market is expected to witness a steady climb, with estimates suggesting a CAGR (Compound Annual Growth Rate) ranging from 4.6% to 12% by 2030 [1, 3].
- Therapeutic Revolution: Recombinant proteins will continue to play a pivotal role in developing targeted therapies for various diseases, including cancer, autoimmune disorders, and infectious diseases.
- Precision Medicine: Advancements in protein engineering will pave the way for personalized medicine, allowing for the creation of customized protein-based treatments tailored to individual patients' needs.
- Novel Production Platforms: Researchers are exploring alternative hosts beyond the traditional E. coli for protein production. This will lead to increased efficiency, better yields, and the ability to produce complex proteins.
- Continuous Processing: The adoption of continuous processing techniques will streamline production, ensure consistent quality, and reduce manufacturing costs.
- Improved Protein Functionality: Advancements in protein design and engineering will enable the creation of proteins with enhanced functionality and stability, leading to more effective therapies.
- Biosimilars Boom: The market for biosimilars, which are similar but not identical versions of existing recombinant protein drugs, is expected to flourish, offering patients more affordable treatment options.
- Global Reach: As research and development efforts intensify in regions like Asia Pacific, the global market for recombinant proteins will witness significant geographical expansion.
- Convergence with Other Technologies: Recombinant proteins will be increasingly integrated with other technologies like gene editing and nanomedicine, leading to the development of even more powerful therapeutic tools.
- Ethical Considerations: As the field progresses, robust ethical frameworks will be crucial for ensuring the responsible development, production, and application of recombinant proteins.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Demand for Biopharmaceuticals
The increasing use of recombinant proteins in biologic drugs, which offer higher efficacy and fewer side effects than traditional medications, is driving market growth as pharmaceutical companies expand their biologics pipelines.
Technological Advancements in Protein Engineering
Innovations such as CRISPR-Cas9 gene editing and improved expression systems have made recombinant protein production more efficient, scalable, and customizable, enabling broader applications and faster development cycles.
Rising Incidence of Chronic Diseases
The global rise in chronic conditions like cancer, diabetes, and autoimmune disorders is fueling demand for targeted biologic therapies, many of which rely on recombinant proteins for their mechanism of action.
Increasing Investments in Biotechnology R&D
Public and private sector investments in biotechnology research are accelerating the discovery and commercialization of novel recombinant protein therapeutics, supported by government initiatives and industry-academic collaborations.
Expanding Applications in Personalized Medicine
Advances in genomics and biomarker-driven therapies are enabling the development of recombinant proteins tailored to individual patient profiles, enhancing treatment efficacy and supporting the growth of precision medicine.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What are the challenges associated with recombinant protein production?
How can we ensure the safety and efficacy of recombinant protein therapies?
What are the implications of recombinant proteins for personalized medicine?
How will advancements in protein engineering impact the future of recombinant proteins?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Therapeutic Proteins
- 1.2.2 Monoclonal Antibodies
- 1.2.3 Enzymes
- 1.2.4 Growth Factors
- 1.2.5 Research Proteins
- 1.2.6 Industrial Proteins
- 1.3 By End User
- 1.3.1 Pharmaceutical & Biotechnology Companies
- 1.3.2 Academic & Research Institutions
- 1.3.3 Contract Research Organizations (CROs)
- 1.3.4 Contract Manufacturing Organizations (CMOs)
- 1.4 By Application
- 1.4.1 Therapeutics
- 1.4.2 Drug Discovery & Development
- 1.4.3 Diagnostics
- 1.4.4 Industrial Processes
- 1.4.5 Research
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 1,897.70 million → 2032: USD 4,577.70 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Recombinant Protein Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Recombinant Protein Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Recombinant Protein Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Recombinant Protein Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Recombinant Protein Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Recombinant Protein Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Recombinant Protein Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Recombinant Protein Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 1,897.70 million → 2032: USD 4,577.70 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Recombinant Protein Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Therapeutic Proteins
- 12.3.7.2 Monoclonal Antibodies
- 12.3.7.3 Enzymes
- 12.3.7.4 Growth Factors
- 12.3.7.5 Research Proteins
- 12.3.7.6 Industrial Proteins
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Pharmaceutical & Biotechnology Companies
- 12.4.7.2 Academic & Research Institutions
- 12.4.7.3 Contract Research Organizations (CROs)
- 12.4.7.4 Contract Manufacturing Organizations (CMOs)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Therapeutics
- 12.5.7.2 Drug Discovery & Development
- 12.5.7.3 Diagnostics
- 12.5.7.4 Industrial Processes
- 12.5.7.5 Research
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Recombinant Protein End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Recombinant Protein Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Recombinant Protein Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Recombinant Protein Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Thermo Fisher Scientific
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Merck & Co., Inc.
- 18.4 Novo Nordisk
- 18.5 Lonza Group
- 18.6 Bio-Rad Laboratories
- 18.7 Abcam
- 18.8 CellGenix GmbH
- 18.9 ProSpec-Tany TechnoGene Ltd.
- 18.10 R&D Systems (Bio-Techne)
- 18.11 GenScript
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

