
Market Overview:
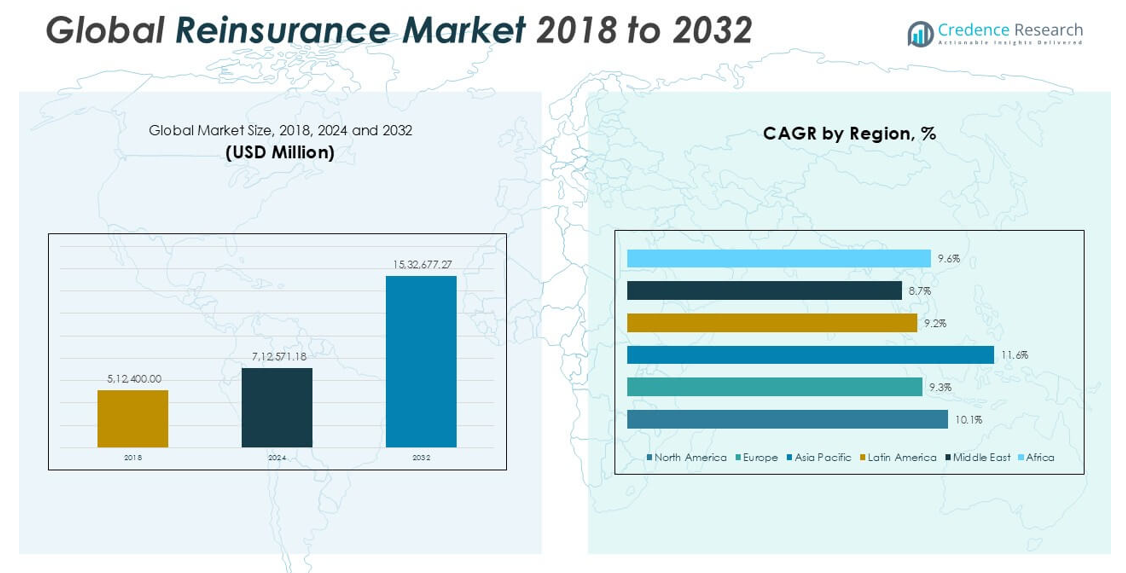
The reinsurance market size was valued at USD 512,400.00 million in 2018 and increased to USD 712,571.18 million in 2024. It is anticipated to reach USD 1,532,677.27 million by 2032, growing at a CAGR of 10.14% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Reinsurance Market Size 2024 | USD 712,571.18 million |
| Reinsurance Market, CAGR | 10.14% |
| Reinsurance Market Size 2032 | USD 1,532,677.27 million |
The global reinsurance market is led by prominent players such as Munich Re, Swiss Re, Hannover Re, SCOR SE, Berkshire Hathaway Reinsurance Group, Everest Re, and Lloyd’s of London. These companies dominate due to their strong capital base, global underwriting capabilities, and diversified risk portfolios. North America emerged as the leading regional market in 2024, capturing 42.34% of the global market share, driven by high insurance penetration, regulatory maturity, and frequent natural catastrophe exposure. Europe and Asia Pacific followed, supported by robust infrastructure, technological adoption, and growing insurance markets. Competitive strategies among key players include expanding digital capabilities, leveraging alternative capital, and strengthening risk analytics to address increasing climate-related and cyber risks.
Market Insights
- The global reinsurance market was valued at USD 712,571.18 million in 2024 and is projected to reach USD 1,532,677.27 million by 2032, growing at a CAGR of 10.14% during the forecast period.
- The market is primarily driven by the rising frequency of natural disasters and stricter regulatory capital requirements, which are prompting insurers to seek risk mitigation through reinsurance solutions.
- A growing trend in the market is the adoption of digital technologies and insurtech platforms that enhance underwriting efficiency, pricing accuracy, and claims management.
- The market is highly competitive, with major players such as Munich Re, Swiss Re, and Hannover Re focusing on innovation, global expansion, and ESG-compliant offerings, while alternative capital continues to increase pressure on traditional pricing models.
- Regionally, North America led with a 42.34% share in 2024, followed by Europe (23.30%) and Asia Pacific (21.45%); by type, treaty reinsurance held the largest segment share.
Market Segmentation Analysis:
By Type
In the reinsurance market, the treaty reinsurance segment holds the dominant position, accounting for a significant market share in 2024. This dominance is driven by its efficiency in covering a portfolio of risks without the need for individual underwriting, making it a preferred choice for insurers seeking long-term risk mitigation. Treaty reinsurance offers greater stability, operational ease, and predictability in claims, which has contributed to its widespread adoption. Additionally, the increasing complexity of insurance products and the rising frequency of catastrophic events have accelerated demand for structured and comprehensive reinsurance agreements.
- For instance, Hannover Re underwrote over 67.3 billion euros in gross written premiums in 2023, of which more than 85% came from treaty reinsurance agreements, reinforcing its focus on this model for scalable risk coverage.
By Application
The property & casualty reinsurance segment emerged as the leading application in the global market, capturing the largest revenue share in 2024. This growth is fueled by the increasing occurrence of natural disasters, climate-related risks, and industrial accidents, which have significantly raised the demand for risk transfer solutions among primary insurers. Furthermore, regulatory pressures and capital requirements have compelled insurers to seek additional protection through reinsurance, particularly in high-risk geographies. The rising global infrastructure development and urbanization further amplify exposure to property risks, reinforcing the segment's dominance.
- For instance, Swiss Re reported property & casualty reinsurance premiums of USD 24.6 billion in 2023, supported by over 100 active P&C reinsurance treaties across disaster-prone regions like the U.S. Gulf Coast and Southeast Asia.
By Mode
The offline segment continues to dominate the reinsurance market by mode, holding the largest market share in 2024. This is primarily due to the traditional reliance on personalized brokerage services and direct negotiations, which remain critical in managing complex and high-value reinsurance contracts. While digital platforms are gaining traction, the offline mode maintains an edge through its ability to offer tailored solutions, in-depth risk assessment, and stronger client relationships. However, the market is gradually witnessing a shift as online platforms grow, driven by digitalization, cost-efficiency, and faster transaction capabilities.
Market Overview
Rising Frequency of Natural Disasters
The increasing incidence of natural catastrophes-such as hurricanes, wildfires, and floods-has significantly boosted the demand for reinsurance. As insurers face escalating claims due to climate-related events, they are increasingly turning to reinsurers to share risk and maintain financial stability. This trend is particularly evident in regions vulnerable to severe weather conditions, where primary insurers seek reinsurance to reduce capital exposure. As climate volatility continues, the reinsurance market is poised to benefit from growing demand for catastrophe risk coverage.
- For instance, Munich Re paid out USD 10.2 billion in natural catastrophe claims in 2023 alone, including USD 3.3 billion for Hurricane Ian-related losses, demonstrating its central role in absorbing climate-driven insurance shocks.
Expansion of Insurance Penetration in Emerging Markets
Emerging economies in Asia-Pacific, Latin America, and Africa are witnessing a steady rise in insurance penetration driven by improving economic conditions, regulatory reforms, and increased awareness. As primary insurance markets expand in these regions, the need for reinsurance grows in tandem to support capital management and solvency requirements. Reinsurers are capitalizing on this opportunity by forming strategic alliances and tailoring products for these high-growth markets, fueling overall industry expansion.
- For instance, SCOR SE reported a 12.4% growth in premiums from Asia-Pacific in 2023, with more than 40 new treaty agreements signed in India and Southeast Asia to support local insurance growth.
Stringent Regulatory Capital Requirements
Global regulatory frameworks such as Solvency II in Europe and Risk-Based Capital (RBC) standards in the U.S. and Asia are encouraging insurers to hold adequate capital buffers. Reinsurance serves as a vital tool in helping insurers manage risk exposure and maintain regulatory compliance. By transferring a portion of liabilities to reinsurers, insurance companies can optimize their capital structure and improve solvency ratios, driving the increased adoption of reinsurance solutions across the globe.
Key Trends & Opportunities
Digital Transformation and Insurtech Integration
The integration of advanced technologies such as artificial intelligence, predictive analytics, and blockchain is transforming reinsurance operations. Digital platforms are improving underwriting accuracy, accelerating claims processing, and enhancing risk modeling. The adoption of insurtech solutions allows reinsurers to reduce operational costs and offer personalized solutions. As more players invest in digital capabilities, the market is expected to become more agile, data-driven, and customer-centric, unlocking new growth avenues.
- For instance, Reinsurance Group of America (RGA) processed over 90 million automated underwriting decisions in 2023 through its digital underwriting platform AURA, significantly increasing underwriting speed and accuracy across global markets.
Growth in Alternative Capital and Insurance-Linked Securities (ILS)
Reinsurers are increasingly leveraging alternative capital sources such as insurance-linked securities, catastrophe bonds, and sidecars to diversify risk and improve capital efficiency. These instruments attract institutional investors seeking non-correlated returns and provide reinsurers with greater flexibility in managing catastrophic exposure. The continued growth of ILS enhances market capacity and opens up new opportunities for innovative risk transfer mechanisms, especially in the face of increasing climate risks.
- For instance, Everest Re facilitated over USD 2.3 billion in insurance-linked securities transactions in 2023, including five catastrophe bond issuances across North America and the Caribbean to spread peak peril risks.
Key Challenges
Volatility in Catastrophic Losses
The unpredictable nature of catastrophic events poses a major challenge for reinsurers. A single large-scale disaster can lead to substantial financial losses, impacting profitability and reserve adequacy. With climate change intensifying the severity and frequency of such events, reinsurers must navigate heightened risk and increased pricing pressure. Managing exposure through diversified portfolios and advanced risk modeling remains critical, but volatility continues to test market resilience.
Intensifying Market Competition and Pricing Pressure
The reinsurance industry is experiencing growing competition from both traditional players and alternative capital providers. This influx of capital and capacity has led to downward pressure on premium rates, especially in non-catastrophe lines. As clients seek better terms and pricing, reinsurers face challenges in maintaining underwriting discipline and profitability. The pressure to innovate while preserving margins is driving a shift toward value-added services and data analytics capabilities.
Regulatory and Compliance Complexities
Navigating a fragmented regulatory landscape presents ongoing challenges for global reinsurers. Differing compliance requirements across regions, especially in emerging markets, complicate operations and increase administrative costs. In addition, evolving regulatory expectations regarding solvency, risk management, and ESG (Environmental, Social, Governance) standards require continuous adaptation. Reinsurers must invest in regulatory intelligence and compliance frameworks to mitigate legal risks and ensure sustainable business practices.
Regional Analysis
North America
North America held the largest share in the reinsurance market in 2024, accounting for approximately 42.34% of the global revenue. The market grew from USD 219,307.20 million in 2018 to USD 301,840.87 million in 2024, and is projected to reach USD 647,387.55 million by 2032, registering a CAGR of 10.1% during the forecast period. The region’s dominance is attributed to a highly developed insurance ecosystem, the presence of major reinsurers, and high exposure to catastrophic risks such as hurricanes and wildfires. Regulatory reforms and demand for advanced risk transfer solutions further fuel regional growth.
Europe
Europe accounted for around 23.30% of the global reinsurance market in 2024. The regional market grew from USD 124,615.68 million in 2018 to USD 166,009.60 million in 2024, and is expected to reach USD 335,583.77 million by 2032, expanding at a CAGR of 9.3%. Market growth in Europe is driven by robust regulatory frameworks like Solvency II, mature insurance markets, and growing climate-related risks. Major European reinsurers continue to expand their global footprint, while digital innovation and increased demand for specialty lines such as cyber and health reinsurance also contribute to sustained growth.
Asia Pacific
Asia Pacific held approximately 21.45% of the global reinsurance market share in 2024. The market expanded from USD 104,324.64 million in 2018 to USD 152,807.90 million in 2024, and is projected to reach USD 365,572.34 million by 2032, growing at the fastest CAGR of 11.6%. The region’s growth is propelled by increasing insurance penetration in emerging economies, rapid urbanization, and rising awareness of risk management. Countries such as China, India, and Southeast Asian nations are witnessing significant demand for property, health, and catastrophe reinsurance, making Asia Pacific a key focus area for global reinsurers.
Latin America
Latin America represented about 6.42% of the global reinsurance market in 2024. The market size grew from USD 33,203.52 million in 2018 to USD 45,739.94 million in 2024, and is projected to reach USD 91,454.84 million by 2032, at a CAGR of 9.2%. The growth is supported by economic recovery, regulatory improvements, and increasing demand for coverage in sectors such as agriculture, infrastructure, and health. Reinsurers are leveraging localized expertise to expand in the region, while greater awareness of disaster preparedness and risk transfer tools is gradually enhancing the market landscape.
Middle East
The Middle East contributed around 3.34% of the global reinsurance market in 2024. From USD 18,343.92 million in 2018, the market reached USD 23,795.25 million in 2024, and is expected to hit USD 45,835.48 million by 2032, with a CAGR of 8.7%. Market growth is driven by the rising demand for reinsurance in property, health, and construction sectors, supported by economic diversification and infrastructure development across the Gulf Cooperation Council (GCC) countries. While the region is relatively underpenetrated, ongoing insurance reforms and increased participation of global reinsurers are expected to improve market maturity.
Africa
Africa held approximately 3.14% of the reinsurance market share in 2024. The market expanded from USD 12,605.04 million in 2018 to USD 22,377.62 million in 2024, and is projected to reach USD 46,843.29 million by 2032, registering a CAGR of 9.6%. The region’s growth is fueled by efforts to increase insurance inclusion, strengthen regulatory frameworks, and develop financial resilience against natural disasters and climate risks. Countries such as South Africa, Nigeria, and Kenya are emerging as key hubs for insurance and reinsurance development, though infrastructural and economic challenges continue to impact rapid market scaling.
Market Segmentations:
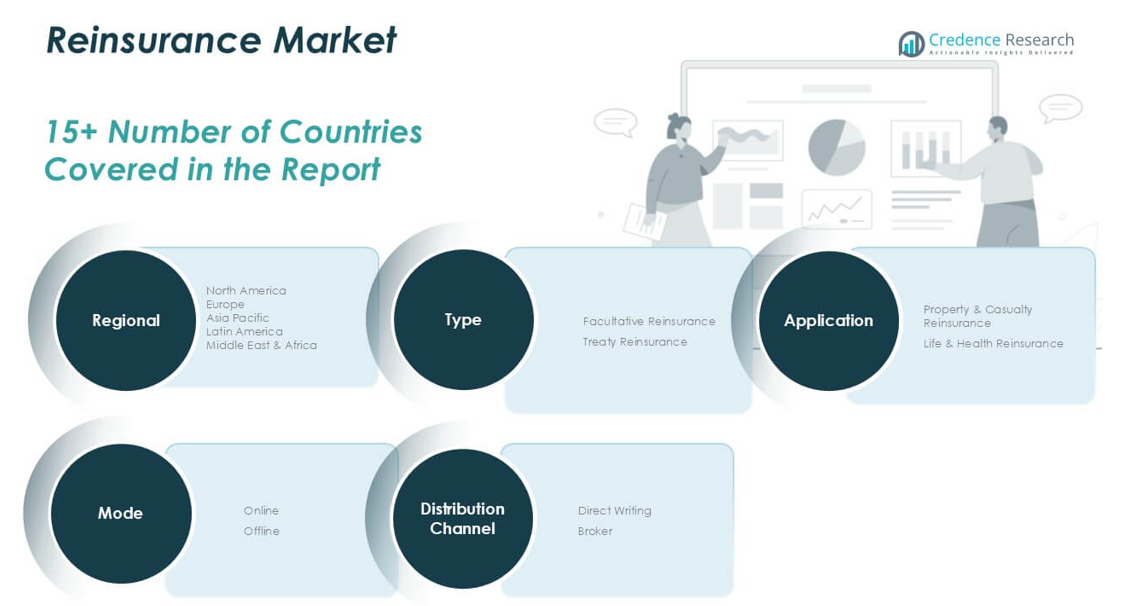
By Type
- Facultative Reinsurance
- Treaty Reinsurance
By Application
- Property & Casualty Reinsurance
- Life & Health Reinsurance
By Mode
- Online
- Offline
By Distribution Channel
- Direct Writing
- Broker
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The global reinsurance market is highly competitive and dominated by a mix of well-established multinational players and specialized reinsurers. Leading companies such as Munich Re, Swiss Re, Hannover Re, and SCOR SE hold substantial market shares, leveraging their global presence, diversified portfolios, and advanced risk modeling capabilities. These players continuously invest in digital technologies, predictive analytics, and innovative reinsurance solutions to strengthen underwriting accuracy and operational efficiency. The market also features significant activity from firms like Everest Re, Lloyd’s of London, and Berkshire Hathaway Reinsurance Group, which focus on strategic partnerships and alternative capital instruments such as catastrophe bonds. Intense competition is prompting reinsurers to differentiate through customized offerings, regional expansions, and ESG-aligned practices. Moreover, rising climate-related risks and evolving regulatory landscapes are compelling players to enhance resilience and transparency. As the market evolves, companies that integrate technology, risk diversification, and capital strength will sustain long-term competitive advantages.
Key Player Analysis
- Munich Re Group (Münchener Rückversicherungs-Gesellschaft)
- Swiss Re Group (Swiss Reinsurance Company Ltd.)
- Hannover Re (Hannover Rück SE)
- SCOR SE
- RGA Reinsurance Company
- Lloyd's of London
- Everest Re Group, Ltd.
- Berkshire Hathaway Reinsurance Group
- PartnerRe Ltd.
- TransRe (Transatlantic Holdings, Inc.)
- Arch Capital Group Ltd.
- Axis Capital Holdings Limited
- Reinsurance Group of America, Incorporated (RGA)
- XL Catlin
- Mapfre Re
Recent Developments
- In February 2025, Fortitude Re and Unum Group have completed a significant reinsurance transaction valued at USD 3.4 billion, aimed at enhancing Unum's financial flexibility. The deal covers approximately 19% of Unum’s long-term care reserves, transferring associated risks to Fortitude Re.
- In February 2025, RGA reinsured USD 32 billion of life policies from Equitable. It deployed USD 1.5 billion of capital to support the transaction.
- In 2025, Munich Re reported a net result of €1.1 billion, despite high major-loss expenditure, and reaffirmed its full-year net result guidance of €6 billion. This strong performance comes after a 2024 with €60.8 billion in insurance revenue and a €5.7 billion net result. Munich Re continues to focus on new and emerging risks, including cyber and AI.
- In April 2023, Swiss Re Reinsurance and Des Moines Insurtech Benekiva formed a strategic alliance to develop an Integrated Claims Management platform. This collaboration integrates Swiss Re's Claims Automated Rules Engine and extensive risk management expertise with Benekiva's innovative claims management system.
- In 2022, Reinsurance Group of America has agreed with Taiyo Life, a subsidiary of T&D Holdings, Inc., to reinsure USD 1,170 million of statutory reserves through coinsurance. Taiyo Life will maintain its service provision under the insurance contract following this arrangement.
- In 2022, Berkshire Hathaway successfully acquired Alleghany, a corporation with operating subsidiaries and a significant focus on property and casualty reinsurance. The transaction, valued at USD 11.6 billion, includes the acquisition of all equities of Alleghany, aligning with Berkshire's diverse business activities in insurance and reinsurance.
Market Concentration & Characteristics
The Reinsurance Market exhibits a high level of market concentration, with a few dominant players such as Munich Re, Swiss Re, and Hannover Re controlling a significant share of global revenues. These companies benefit from extensive capital reserves, global underwriting networks, and advanced risk modeling capabilities, which enable them to handle complex and high-value risks. It operates under long-term contracts, making market entry difficult for smaller firms and new entrants. The industry is capital-intensive and cyclical, driven by macroeconomic trends, regulatory changes, and the frequency of catastrophic events. It also relies heavily on trust, risk assessment accuracy, and financial strength, reinforcing the competitive edge of established firms. The market is characterized by a growing need for innovation in risk transfer, especially in areas such as climate risk, cyber risk, and pandemic-related coverage. Technological integration is gradually transforming underwriting and claims management, while regulatory compliance and capital adequacy continue to shape operational strategies. Despite alternative capital inflows through instruments like catastrophe bonds, traditional reinsurers maintain dominance by offering tailored solutions and maintaining long-standing relationships with primary insurers.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Mode, Distribution Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The reinsurance market will continue to grow steadily driven by rising demand for risk transfer solutions across global insurance sectors.
- Climate change and increasing natural catastrophe frequency will drive higher uptake of property and casualty reinsurance.
- Emerging markets in Asia Pacific, Africa, and Latin America will see stronger reinsurance demand due to improving insurance penetration.
- Digital transformation will streamline underwriting, pricing, and claims management processes across the reinsurance value chain.
- The use of alternative capital such as catastrophe bonds and insurance-linked securities will expand to support capacity and flexibility.
- Regulatory developments will push reinsurers to strengthen solvency margins, risk governance, and capital adequacy standards.
- Demand for specialty reinsurance in areas like cyber risk, health, and agriculture will increase significantly.
- Leading reinsurers will focus on geographic expansion, innovation, and ESG integration to maintain competitive advantage.
- Broker-driven channels and digital distribution platforms will enhance market accessibility and transparency.
- Consolidation through mergers and acquisitions will reshape the competitive landscape and improve operational efficiency.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Frequency of Natural Disasters
The increasing incidence of catastrophic events such as hurricanes, floods, and wildfires is driving insurers to seek reinsurance to manage escalating claims and maintain financial stability, particularly in high-risk regions.
Stringent Regulatory Capital Requirements
Global regulatory frameworks like Solvency II and RBC standards require insurers to hold higher capital reserves, prompting greater reliance on reinsurance to optimize capital structure and ensure compliance.
Expansion of Insurance Penetration in Emerging Markets
Economic growth, regulatory reforms, and rising risk awareness in Asia Pacific, Latin America, and Africa are boosting primary insurance uptake, which in turn increases demand for reinsurance solutions to support solvency and risk management.
Digital Transformation and Insurtech Integration
The adoption of digital platforms, AI, and advanced analytics is enhancing underwriting, pricing, and claims management efficiency, making reinsurance more accessible and attractive to insurers seeking operational improvements.
Growth in Alternative Capital and Insurance-Linked Securities (ILS)
The increasing use of catastrophe bonds and ILS is expanding market capacity and providing reinsurers with new tools to diversify risk and attract institutional investors, especially in the face of rising climate-related exposures.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the reinsurance market from 2024 to 2032?
What are the key factors driving the growth of the reinsurance market?
How is digital transformation impacting the reinsurance market?
Which regions are expected to dominate the reinsurance market?
Why is there growing demand for reinsurance in emerging markets like China and India?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Mode
- 1.2.1 Online
- 1.2.2 Offline
- 1.3 By Type
- 1.3.1 Facultative Reinsurance
- 1.3.2 Treaty Reinsurance
- 1.4 By Application
- 1.4.1 Property & Casualty Reinsurance
- 1.4.2 Life & Health Reinsurance
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 712,571.18 million → 2032: USD 1,532,677.27 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Reinsurance Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Reinsurance Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Reinsurance Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Reinsurance Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Reinsurance Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Reinsurance Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Reinsurance Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Reinsurance Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 712,571.18 million → 2032: USD 1,532,677.27 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Reinsurance Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Mode - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Online
- 12.3.6.2 Offline
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Facultative Reinsurance
- 12.4.6.2 Treaty Reinsurance
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Property & Casualty Reinsurance
- 12.5.6.2 Life & Health Reinsurance
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Reinsurance End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Reinsurance Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Reinsurance Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Reinsurance Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Munich Re Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Swiss Re Group
- 18.4 Hannover Re
- 18.5 SCOR SE
- 18.6 RGA Reinsurance Company
- 18.7 Lloyd's of London
- 18.8 Everest Re Group, Ltd.
- 18.9 Berkshire Hathaway Reinsurance Group
- 18.10 PartnerRe Ltd.
- 18.11 TransRe
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

