
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
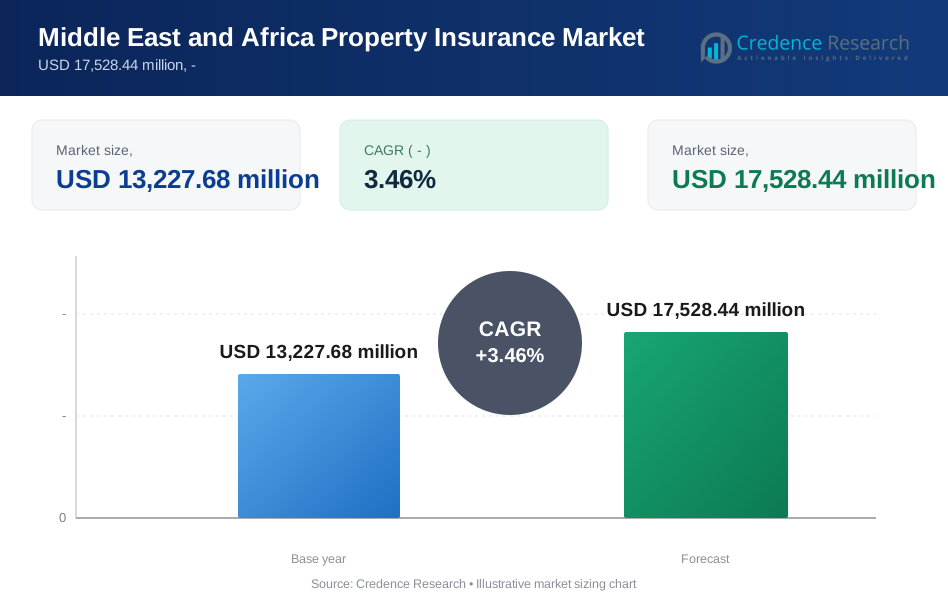
| Middle East and Africa Property Insurance Market Size 2023 | USD 13,227.68 Million |
| Middle East and Africa Property Insurance Market, CAGR | 3.46% |
| Middle East and Africa Property Insurance Market Size 2032 | USD 17,528.44 Million |
Market Overview
The Middle East and Africa property insurance market is projected to witness significant growth, with its value expected to rise from USD 13,227.68 million in 2023 to USD 17,528.44 million by 2032, representing a compound annual growth rate of 3.46%. The Middle East and Africa (MEA) property insurance market stands as a dynamic sector within the broader insurance industry, propelled by factors such as economic growth, urbanization, and an escalating awareness of risk management. As one of the world's fastest-growing regions, the MEA presents both significant opportunities and formidable challenges for insurers active in the property insurance segment.
The economic landscape of the MEA region is characterized by a multitude of factors that influence property insurance dynamics. A burgeoning middle class and rising disposable incomes are fueling a heightened demand for residential and commercial properties across urban centers. Additionally, infrastructure development initiatives, particularly in emerging markets such as the Gulf Cooperation Council (GCC) countries, are driving construction activities, thereby broadening the insurable property base within the region.
The regulatory frameworks governing the insurance sector in the MEA region exhibit considerable diversity across countries, reflecting variations in legal structures and regulatory bodies. While some countries boast well-established insurance regulatory authorities ensuring compliance and consumer protection, others are in the process of fortifying their regulatory frameworks to foster market stability and confidence. Adherence to regulatory requirements is imperative for insurers operating in the MEA property insurance market to uphold operational integrity and engender trust among stakeholders.
Several key trends are reshaping the landscape of the MEA property insurance market. Technological innovation, exemplified by the adoption of advanced tools like artificial intelligence (AI), big data analytics, and Internet of Things (IoT) devices, is revolutionizing risk assessment, underwriting processes, and claims management. Insurers harnessing these technologies gain a competitive edge by amplifying operational efficiency, fine-tuning pricing strategies, and offering tailored insurance solutions.
Segmentation Analysis
By Type:
In dissecting the Middle East and Africa (MEA) property insurance market by coverage, several distinct segments emerge, each catering to specific risk profiles and insurance needs. Fire and theft insurance remains a foundational aspect, safeguarding properties against the perils of fire outbreaks and theft incidents, which are perennial concerns for property owners and insurers alike. House damage coverage extends protection against structural damages arising from various causes, such as accidents, natural disasters, or malicious acts, ensuring comprehensive coverage for property owners. Flood and earthquake insurance addresses the region's susceptibility to natural catastrophes, offering financial protection against the devastating consequences of floods, earthquakes, and other geological events.
By Application:
When examining the MEA property insurance market by application, the segmentation reveals divergent insurance needs across personal and enterprise spheres. Personal property insurance caters to individual homeowners and renters, offering tailored coverage for residential properties and personal belongings. This segment underscores the importance of protecting personal assets and ensuring financial security for individuals and families against unforeseen events. Conversely, enterprise property insurance targets businesses and commercial entities, addressing the unique risk exposures inherent in commercial properties and operations.
By End User:
Segmenting the MEA property insurance market by end user sheds light on the diverse stakeholders seeking insurance protection for their properties. Landlords constitute a significant end-user segment, encompassing property owners who lease or rent out residential or commercial properties. For landlords, property insurance serves as a safeguard against potential risks associated with property ownership and rental activities, ensuring financial protection and mitigating liability exposures. Homeowners represent another pivotal end-user group, comprising individuals or families who own residential properties. Property insurance for homeowners encompasses various coverage elements, ranging from structural protection to personal belongings coverage, tailored to address the unique needs of homeownership. Additionally, renters emerge as a distinct end-user segment, encompassing individuals or households that lease residential properties. Renters' insurance offers coverage for personal belongings and liability protection, providing tenants with financial security and peace of mind in their rental living arrangements.
Segmentations:
By Coverage:
- Fire and theft
- House Damage
- Floods and Earthquakes
- Personal Property
By Application:
- Personal
- Enterprise
By End User:
- Landlords
- Homeowners
- Renters
By Region:
- Saudi Arabia
- UAE
- Qatar
- Kuwait
- South Africa
- Nigeria
- Algeria
- The rest of MEA
Market Drivers
Rapid Urbanization:
The Middle East and Africa are witnessing a swift transition towards urban living, marked by a significant influx of people into cities. For instance, the urban population in the Middle East and North Africa (MENA) region is already 64% urbanized. This rapid urbanization phenomenon stems from various factors, including employment opportunities, better amenities, and improved infrastructure. As more individuals migrate to urban centers, there is a corresponding surge in property ownership, both residential and commercial. This uptick in property ownership underscores the critical need for property insurance as urban dwellers seek to protect their valuable assets against unforeseen risks and liabilities.
Rising Construction Activity:
Governments across the Middle East and Africa are channeling substantial investments into infrastructure development projects to support economic growth and meet the demands of expanding urban populations. For example, the Middle East and North Africa (MENA) region is expected to spend $1 trillion on transport infrastructure projects over the next decade. This concerted effort has fueled a construction boom, resulting in the proliferation of residential, commercial, and industrial properties. The escalating value of insurable properties amplifies the relevance of property insurance as property owners seek to safeguard their investments against potential risks and vulnerabilities arising from construction activities and associated hazards.
Increasing Awareness about Risk Management:
A notable shift in societal attitudes towards risk management is underway, driven by heightened awareness of the potential perils posed by natural disasters, fire outbreaks, theft incidents, and other unforeseen events. This growing consciousness prompts individuals and businesses alike to prioritize financial protection through property insurance. As stakeholders recognize the inherent risks associated with property ownership, there is a corresponding uptick in demand for comprehensive insurance coverage to mitigate potential losses and liabilities.
Need for Mortgage Protection:
The proliferation of mortgage products in select regions of the Middle East and Africa underscores the need for property insurance as a means of mortgage protection. Lenders often mandate borrowers to procure property insurance to safeguard the mortgaged property against damage or destruction, mitigating the lender's risk exposure. This symbiotic relationship between mortgage lending and property insurance underscores the integral role of insurance in facilitating homeownership and ensuring financial security for borrowers and lenders alike.
Growing Financial Inclusion:
Financial inclusion initiatives are gaining traction across the Middle East and Africa, fostering greater accessibility to insurance products among previously underserved populations. This broader access to insurance services expands the pool of potential policyholders considering property insurance as a means of asset protection and risk mitigation. By extending insurance coverage to a wider segment of the population, financial inclusion initiatives contribute to the overall resilience and stability of the property insurance market in the region.
Technological Advancements:
The advent of InsurTech, characterized by technological innovations in the insurance sector, is reshaping the landscape of property insurance in the Middle East and Africa. Digital platforms and online tools facilitate seamless policy comparison, convenient online purchasing, and streamlined claim processing, enhancing the overall customer experience. These technological advancements make property insurance more accessible, user-friendly, and efficient, driving increased adoption and market penetration.
Market Trends
Product Diversification:
Insurers operating in the Middle East and Africa (MEA) property insurance market are diversifying their product offerings beyond traditional insurance products. This trend involves the introduction of specialized coverage options tailored to address specific risks faced by property owners. For instance, 63% of surveyed MEA companies purchase some type of cyber insurance. Examples of these specialized coverages include earthquake insurance, which is becoming increasingly relevant due to the region’s exposure to earthquake risk; flood insurance, which is gaining importance due to the increasing frequency and severity of floods in the region; and cyber insurance, which protects against data breaches and cyberattacks that can impact property functionality.
Usage-Based Insurance (UBI):
Leveraging telematics and Internet of Things (IoT) technologies, insurers are introducing usage-based insurance (UBI) models in the MEA property insurance market. For instance, the usage-based insurance market in the Middle East and Africa is expected to witness market growth at a rate of 16.6% in the forecast period of 2021 to 2028. Property owners can opt for UBI policies that offer discounts based on real-time data on security measures and occupancy patterns. For example, a study conducted at Qatar University demonstrated an occupancy detection system that achieved a real-time prediction accuracy of 99.75%.
By promoting risk mitigation and personalized premiums, UBI encourages proactive property management practices. For instance, insurers in the region have been swift in responding to market situations, introducing initiatives such as premium discounts and additional coverage.
Focus on the customer experience:
Insurers are placing a heightened emphasis on enhancing the customer experience within the MEA property insurance market. This entails the provision of online portals for policy management, mobile apps for claim filing, and round-the-clock customer support services. By prioritizing convenience, accessibility, and responsiveness, insurers aim to improve customer satisfaction and retention rates, thereby strengthening their competitive position in the market and fostering long-term relationships with policyholders.
Strategic Partnerships:
Collaboration between insurance companies, technology providers, and regional distributors is becoming increasingly prevalent in the MEA property insurance market. These strategic partnerships enable insurers to expand their market reach, leverage technological expertise, and cater to diverse customer segments more effectively. By pooling resources and expertise, insurers can enhance their product offerings, distribution channels, and customer engagement strategies, ultimately driving growth and innovation within the industry.
Emphasis on Risk Prevention:
Insurers in the MEA property insurance market are recognizing the value of proactive risk prevention strategies in mitigating potential losses and enhancing policyholder satisfaction. To incentivize risk prevention efforts, insurers offer policyholders discounts for installing security systems or implementing preventative measures against natural disasters. This focus on risk mitigation not only benefits insurers by reducing claim payouts but also empowers policyholders to safeguard their properties and minimize their exposure to risks.
Regulatory Developments:
Regulatory bodies in the MEA region are implementing stricter regulations to ensure transparency, fair pricing, and consumer protection within the property insurance market. These regulatory developments foster trust among stakeholders and promote healthy competition among insurers. By establishing clear guidelines and standards, regulatory authorities contribute to market stability and integrity, ultimately enhancing consumer confidence and facilitating sustainable growth within the MEA property insurance sector.
Market Restraints and Challenges
Low Insurance Penetration:
One of the primary challenges confronting the Middle East and Africa (MEA) property insurance market is the persistently low insurance penetration, particularly prevalent in many African countries. Factors contributing to this phenomenon include limited disposable income among the population, a lack of awareness about the benefits of insurance, and a cultural inclination towards self-insurance practices. Addressing this hurdle requires concerted efforts to enhance insurance literacy, promote financial inclusion, and develop innovative distribution channels to reach underserved segments of the population.
Informal Property Ownership:
A significant proportion of properties in Africa, particularly in rural areas, lack formal documentation, posing a challenge for insurers in assessing risk and offering insurance coverage for these properties. The prevalence of informal property ownership complicates risk management efforts and hampers insurers' ability to accurately underwrite policies. Collaborative initiatives involving governmental bodies, community organizations, and insurers are needed to streamline property documentation processes and enhance insurance accessibility for property owners in these regions.
Limited Catastrophe Modeling:
The underdevelopment of catastrophe modeling tools in certain parts of the MEA region presents a considerable obstacle for insurers in accurately assessing risks associated with natural disasters. The lack of comprehensive catastrophe modeling capabilities can lead to underpricing of insurance policies or reluctance among insurers to offer coverage in high-risk areas. Investment in the development and implementation of advanced catastrophe modeling technologies is essential to strengthening insurers' risk management practices and improving their ability to quantify and mitigate catastrophic risks effectively.
Political Instability and Conflict:
Political instability and ongoing conflicts in certain regions of the MEA pose significant challenges for insurance companies operating in the property insurance market. The unpredictable security situation undermines investor confidence, discourages investment in insurance infrastructure, and complicates insurers' ability to operate effectively. To navigate these challenges, insurers must adopt robust risk management strategies, closely monitor geopolitical developments, and collaborate with relevant stakeholders to mitigate the impacts of political instability and conflict on their operations.
High Reinsurance Costs:
Reinsurance costs for certain perils, such as natural disasters and political risks, can be prohibitively high in some parts of Africa and the Middle East. The elevated reinsurance costs impose financial constraints on insurers, making it expensive to offer comprehensive property insurance products. To address this challenge, insurers may need to explore alternative risk transfer mechanisms, diversify their reinsurance portfolios, and implement rigorous risk selection and pricing strategies to manage reinsurance costs effectively while maintaining adequate coverage levels for policyholders.
Fraudulent Claims:
The risk of fraudulent claims poses a significant deterrent for insurers operating in the MEA property insurance market, particularly in regions with weak legal systems and lax enforcement. Fraudulent claims inflate insurers' operational costs, erode profitability, and undermine trust in the insurance industry. To combat fraudulent activities effectively, insurers must invest in robust fraud detection and prevention measures, enhance collaboration with law enforcement agencies, and implement stringent claims verification processes to deter fraudulent behavior and protect the interests of legitimate policyholders.
Key Players
- Oman Insurance Company
- AXA Gulf
- RSA Insurance
- Qatar Insurance Company
- SANAD Cooperative Insurance and Reinsurance Company
- Abu Dhabi National Insurance Company (ADNIC)
- Alliance Insurance
Regional Analysis
Saudi Arabia
Saudi Arabia dominates the Middle East and Africa Property Insurance Market, capturing around 25% of the total market share. The country's booming construction and real estate sectors, driven by initiatives such as Saudi Vision 2030, have fueled the demand for property insurance solutions. The presence of major insurance providers, coupled with the government's efforts to promote insurance literacy, has contributed significantly to market growth. Additionally, the implementation of mandatory property insurance regulations for certain sectors has further propelled the adoption of these solutions in Saudi Arabia.
United Arab Emirates (UAE)
The UAE accounts for approximately 20% of the Middle East and Africa Property Insurance Market share. The country's status as a global business hub and its thriving real estate market have driven the demand for comprehensive property insurance solutions. The UAE's well-established regulatory framework and the presence of international insurance companies have facilitated the growth of the market. Furthermore, the increasing awareness of risk management among property owners and the growing affluence of the population have contributed to the adoption of property insurance products in the region.
Qatar
Qatar holds a modest share of the Middle East and Africa Property Insurance Market, estimated at around 10%. The country's robust economic growth, driven by its energy sector and infrastructure development projects, has fueled the demand for property insurance solutions. The government's efforts to promote the insurance sector and attract global insurers have facilitated market expansion in Qatar. Additionally, the increasing awareness of risk mitigation among property owners and the implementation of mandatory insurance regulations for certain sectors have contributed to the market's growth.
Kuwait
Kuwait accounts for approximately 8% of the Middle East and Africa Property Insurance Market share. The country's stable economy and the growing real estate sector have driven the demand for property insurance solutions. The Kuwaiti government's initiatives to promote the insurance industry and the presence of established local insurers have facilitated market growth. Furthermore, the increasing awareness of risk management among property owners and the implementation of mandatory insurance regulations for certain sectors have contributed to the adoption of property insurance products in Kuwait.
South Africa
South Africa holds a significant share of the Middle East and Africa Property Insurance Market, capturing around 15% of the total market. The country's well-developed insurance sector and the presence of major players have driven the adoption of property insurance solutions. The increasing awareness of risk management among property owners, coupled with the implementation of regulatory requirements for certain industries, has fueled market growth. Additionally, the growing real estate market and the need for comprehensive coverage against natural disasters have contributed to the demand for property insurance products in South Africa.
Future Outlook
- The Middle East and Africa property insurance market is expected to witness sustained expansion in the coming years, driven by rapid urbanization and infrastructure development.
- Growing awareness among property owners about the importance of insurance coverage against natural disasters, accidents, and other risks is likely to boost market penetration.
- Adoption of advanced technologies such as artificial intelligence, the Internet of Things (IoT), and data analytics will enhance risk assessment, claim processing efficiency, and customer service.
- Ongoing regulatory reforms aimed at enhancing transparency, consumer protection, and industry stability are expected to shape the market landscape and foster healthy competition.
- The market will need to adapt to emerging risks such as cyber threats, climate change-related events, and geopolitical instability, necessitating innovative insurance products and risk management strategies.
- Rising investments in real estate and infrastructure projects across the region will create opportunities for insurers to offer tailored coverage solutions to property developers, investors, and homeowners.
- Economic diversification efforts and infrastructure investments in key markets such as the United Arab Emirates, Saudi Arabia, and Egypt are anticipated to drive demand for property insurance products.
- Insurers will prioritize enhancing the customer experience through digitalization, personalized offerings, and streamlined claims processes to differentiate themselves in the competitive landscape.
- Collaborations between insurers, reinsurers, brokers, and technology providers will facilitate innovation, knowledge sharing, and market expansion, benefiting both industry stakeholders and consumers.
- Increasing emphasis on sustainability and environmental conservation is likely to influence insurers to develop eco-friendly insurance products and promote risk mitigation measures to address climate-related challenges.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Middle East and Africa Property Insurance Market between 2023 and 2032?
What factors are driving the growth of the Middle East and Africa Property Insurance Market?
Who are the major players in the Middle East and Africa Property Insurance Market?
How is the availability of the Middle East and Africa Property Insurance Market expanding, and through what channels?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Middle East and Africa Property Insurance Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Middle East and Africa Property Insurance Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 13,227.68 million → forecast year: USD 17,528.44 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Middle East and Africa Property Insurance Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Middle East and Africa Property Insurance Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Middle East and Africa Property Insurance Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Middle East and Africa Property Insurance Market Drivers
- 3.3 Middle East and Africa Property Insurance Market Restraints & Challenges
- 3.4 Middle East and Africa Property Insurance Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Middle East and Africa Property Insurance Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Middle East and Africa Property Insurance Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Middle East and Africa Property Insurance category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Middle East and Africa Property Insurance Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Middle East and Africa Property Insurance Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Middle East and Africa Property Insurance market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Middle East and Africa Property Insurance Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Middle East and Africa Property Insurance Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Middle East and Africa Property Insurance Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Middle East and Africa Property Insurance (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Middle East and Africa Property Insurance Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Middle East and Africa Property Insurance Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Middle East and Africa Property Insurance Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Middle East and Africa Property Insurance Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Middle East and Africa Property Insurance Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Middle East and Africa Property Insurance Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Middle East and Africa Property Insurance Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Middle East and Africa Property Insurance Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Middle East and Africa Property Insurance Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
