
Market Overview:
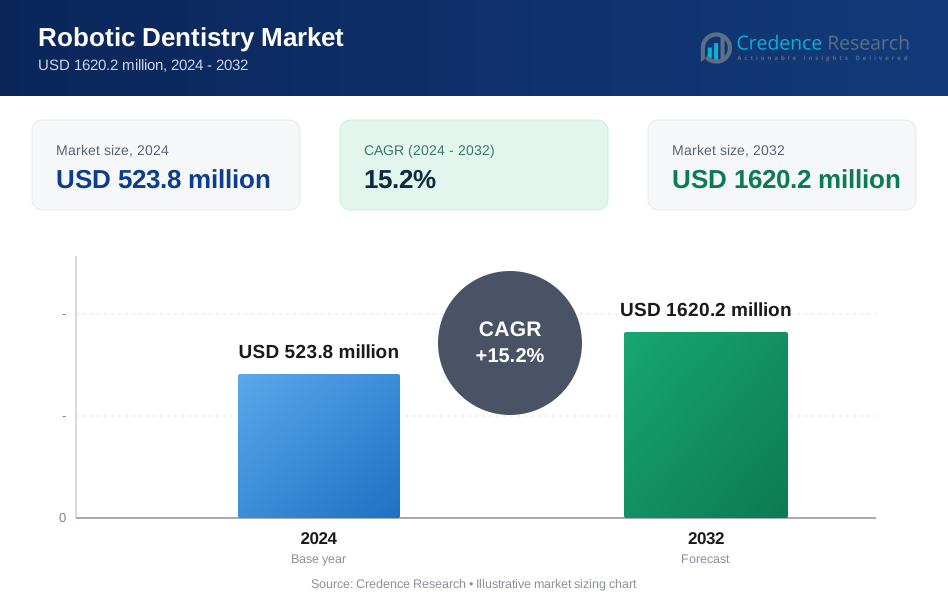
The robotic dentistry market size was valued at USD 523.8 million in 2024 and is anticipated to reach USD 1620.2 million by 2032, at a CAGR of 15.2% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Robotic Dentistry Market Size 2024 | USD 523.8 million |
| Robotic Dentistry Market, CAGR | 15.2% |
| Robotic Dentistry Market Size 2032 | USD 1620.2 million |
Key drivers include rising prevalence of dental disorders, growing geriatric population, and demand for advanced dental care. Robotics enhances accuracy in implantology, orthodontics, and endodontics, reducing surgical errors and improving patient outcomes. Increasing integration of AI-driven navigation, 3D imaging, and haptic feedback technologies also accelerates market adoption. Additionally, the shortage of skilled dental surgeons is pushing clinics and hospitals to embrace robotic-assisted solutions for efficiency.
Regionally, North America leads the market due to advanced healthcare infrastructure and early adoption of medical robotics. Europe follows closely, driven by favorable reimbursement systems and strong dental research initiatives. Asia-Pacific is emerging as the fastest-growing region, supported by rising healthcare investments in China, Japan, and India, along with increasing awareness of digital dentistry. The Middle East and Latin America are also gaining traction, supported by expanding private dental clinics and modernization of healthcare facilities.

Market Insights:
- The robotic dentistry market size was USD 523.8 million in 2024 and will reach USD 1620.2 million by 2032, growing at a CAGR of 15.2%.
- Rising prevalence of dental disorders and demand for advanced care drive market expansion.
- Robotic systems improve accuracy in implantology, orthodontics, and endodontics, reducing surgical risks.
- Integration of AI, 3D imaging, and haptic feedback boosts adoption across clinical practices.
- High system costs and technical complexity limit accessibility, especially in smaller dental clinics.
- North America held 42% share in 2024, supported by strong infrastructure and innovation.
- Asia-Pacific captured 20% share and is the fastest-growing region, driven by healthcare investments in China, India, and Japan.
Market Drivers:
Rising Demand for Precision and Minimally Invasive Dental Procedures:
The robotic dentistry market is driven by the growing demand for precise and minimally invasive procedures. Patients prefer advanced treatments that ensure reduced pain, faster recovery, and improved outcomes. Robotic systems provide greater accuracy in implant placement and orthodontic applications. Dentists benefit from reduced fatigue and improved workflow efficiency, strengthening clinical adoption.
- For Instance, Neocis’s FDA-cleared Yomi robotic platform has enabled clinicians to perform over 60,000 robot-assisted dental implant procedures as of late 2024.
Integration of Advanced Imaging and Artificial Intelligence:
The market benefits from the integration of 3D imaging, AI-powered navigation, and haptic feedback systems. These technologies enhance accuracy during complex dental surgeries and reduce the risk of errors. It helps practitioners plan procedures more effectively with real-time guidance. The combination of robotics and digital dentistry platforms creates higher confidence among patients and providers.
- For instance, Neocis’s Yomi robotic platform—integrated with 3D CBCT imaging and AI-driven haptic feedback—was evaluated in a large prospective series of 273 implant cases, achieving an average depth deviation of just 0.2 mm; to date, over 47,000 implants have been placed with robotic assistance.
Growing Geriatric Population and Prevalence of Oral Disorders:
The robotic dentistry market gains momentum from the rising prevalence of oral health issues among older adults. An aging population faces higher risks of tooth loss, gum disease, and complex dental conditions. Robotic solutions provide consistent precision in addressing these challenges through automated systems. It ensures improved patient safety and supports expanding adoption across hospitals and dental clinics.
Shortage of Skilled Dental Surgeons and Workforce Efficiency Needs:
The market is further influenced by the global shortage of trained dental professionals. Robotic-assisted solutions help address this gap by increasing efficiency and reducing dependence on manual procedures. It enables clinics to perform complex surgeries with consistent quality and minimal errors. The technology also helps reduce procedure time, allowing providers to treat more patients effectively.
Market Trends:
Increasing Adoption of AI-Enabled Robotics and Digital Dentistry Platforms:
The robotic dentistry market is witnessing strong adoption of AI-enabled robotics integrated with digital dentistry platforms. AI algorithms assist in treatment planning, surgical navigation, and error reduction during dental procedures. It enhances efficiency by combining robotics with 3D imaging, CAD/CAM systems, and intraoral scanning. Clinics use these technologies to deliver more accurate implant placements and orthodontic corrections. Robotics paired with digital workflows also improves patient experience by offering predictable outcomes. The trend reflects a shift toward data-driven, automated practices that strengthen precision and reliability in dental care.
- For instance, 3Shape’s TRIOS 5 intraoral scanner captures 2,400 images per second during full-arch scans. Innovations like its ScanAssist engine allow experienced users to complete full-arch scans in as little as 18–35 seconds, resulting in a significantly reduced overall scanning time per arch.
Expansion of Robotic-Assisted Training and Global Investment in Dental Technology:
The market is experiencing growth through the expansion of robotic-assisted training programs for dental professionals. Academic institutions and hospitals invest in simulation-based platforms to train surgeons in complex procedures. It helps bridge skill gaps and supports higher adoption rates among younger practitioners. Global investments in dental robotics research are increasing, with companies focusing on compact, user-friendly systems. New product launches and strategic partnerships are shaping competitive dynamics and driving technological advancements. The trend highlights the industry's commitment to scaling innovation while meeting growing patient expectations worldwide.
- For instance, Neocis’s Yomi robotic system placed over 60,000 dental implants worldwide by January 2025, reflecting rapid adoption across leading academic and clinical centers.
Market Challenges Analysis:
High Cost of Robotic Systems and Limited Accessibility:
The robotic dentistry market faces challenges due to the high cost of robotic systems and maintenance. Advanced platforms require significant investment, which limits adoption by small and mid-sized dental clinics. It creates disparities in access, with large hospitals and specialized centers leading usage. Training costs for dentists also add to the financial burden. Affordability remains a barrier in emerging economies where healthcare budgets are restricted. The expense factor continues to slow down wider penetration across different practice settings.
Technical Complexity and Resistance from Dental Professionals:
The market is further restrained by the technical complexity of robotic systems and the resistance from some dental professionals. Dentists may hesitate to adopt robotics due to steep learning curves and workflow adjustments. It can create reluctance in clinics where traditional techniques remain dominant. System malfunctions or software issues also raise concerns about reliability. Regulatory approval processes for new technologies add more delays to commercialization. The slow pace of acceptance impacts the potential scale of robotic dentistry worldwide.
Market Opportunities:
Rising Demand for Cosmetic Dentistry and Patient-Centric Care:
The robotic dentistry market presents strong opportunities through rising demand for cosmetic dentistry and patient-focused treatments. Growing interest in aesthetic procedures such as dental implants, veneers, and orthodontics supports the adoption of robotics. It improves precision, reduces recovery time, and ensures predictable results that align with patient expectations. Clinics offering advanced robotic-assisted services gain a competitive advantage in urban and high-income regions. Expanding awareness about minimally invasive dental solutions also strengthens opportunities for broader use. The trend positions robotics as a key enabler in personalized and outcome-driven dental care.
Expansion Potential in Emerging Economies and Tele-Dentistry Integration:
The market also holds significant opportunity in emerging economies where healthcare investments are increasing. Governments and private players invest in modern dental infrastructure, creating favorable conditions for robotic adoption. It supports the development of cost-effective systems tailored for smaller clinics in these regions. Integration with tele-dentistry platforms further expands opportunities, enabling remote planning and guided procedures. Partnerships between technology providers and dental institutions can accelerate adoption and market reach. This expansion potential makes robotic dentistry an attractive sector for innovation and global investment.
Market Segmentation Analysis:
By Product & Services:
The robotic dentistry market includes robotic systems, instruments, software, and services. Robotic systems hold the largest share due to growing use in dental implantology and orthodontics. Instruments and accessories support daily clinical operations by ensuring precision and consistency. Software solutions are gaining importance for treatment planning and navigation. It also strengthens service offerings that include training, maintenance, and technical support for clinics and hospitals.
- For instance, the Straumann® CARES® M series milling system features a super high-frequency spindle operating at 100 000 rpm and a six-tool automatic changer, enabling versatile wet and dry processing with micron-level accuracy.
By Application:
The market is segmented into implantology, orthodontics, endodontics, and others. Implantology leads due to rising demand for dental implants requiring high precision. Orthodontics benefits from robotic assistance in alignment and corrective procedures. Endodontics applications expand as robotics ensures accuracy in root canal surgeries. It reflects broad adoption of automation in multiple dental specialties to enhance treatment outcomes.
- For instance, the SureSmile robotic arch-wire bending system delivers bend positioning accuracy within ±0.1 mm, with angular/torsional errors limited to ±1°, ensuring highly consistent custom wire fabrication.
By End-use:
The robotic dentistry market is segmented into hospitals, dental clinics, and academic research institutes. Hospitals dominate due to advanced infrastructure and availability of trained professionals. Dental clinics show rapid growth with demand for minimally invasive and patient-focused treatments. Academic and research institutes adopt robotic systems for education and clinical training. It strengthens innovation and supports faster adoption across end-users worldwide.
Segmentations:
By Product & Services:
- Robotic Systems
- Instruments and Accessories
- Software Solutions
- Services
By Application:
- Implantology
- Orthodontics
- Endodontics
- Others
By End-use:
- Hospitals
- Dental Clinics
- Academic and Research Institutes
By Region:
North America- S.
- Canada
- Mexico
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Brazil
- Argentina
- Rest of Latin America
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America:
North America held 42% market share in the robotic dentistry market in 2024. The region leads adoption due to advanced healthcare infrastructure and early integration of robotics in dental practices. It benefits from a high concentration of specialized dental hospitals, clinics, and research institutions. Strong reimbursement systems and investment in digital dentistry further accelerate acceptance. The United States drives growth with continuous innovation and product launches. Canada also supports expansion through government-backed dental care programs and private sector investment.
Europe:
Europe accounted for 28% market share in the robotic dentistry market in 2024. The region benefits from strong research networks, clinical trials, and government support for advanced medical devices. It focuses on integrating robotics with digital platforms for safer and faster dental care. Germany, France, and the U.K. remain key contributors due to advanced dental education and high patient demand. It also sees growing partnerships between robotics developers and academic institutions. Adoption continues to rise as healthcare systems invest in efficiency and accuracy in dental treatment.
Asia-Pacific:
Asia-Pacific represented 20% market share in the robotic dentistry market in 2024. The region shows fastest growth supported by expanding healthcare investments and rising demand for advanced dental services. It benefits from large patient populations in China, India, and Japan where oral disorders are increasing. Growing awareness of minimally invasive dentistry also supports higher adoption. Governments allocate budgets to modernize dental infrastructure and attract private sector collaborations. It is expected to remain a key growth hub with strong potential for global technology providers.
Key Player Analysis:
- Aseptico Inc.
- Medtronic
- Biolase, Inc.
- Straumann Group
- Neocis
- Synaptive Medical
- Zimmer Biomet
- Renishaw
- PreXion Corporation
- Robocath
- Mectron S.p.A.
- MeKo Laser Material Processing
Competitive Analysis:
The robotic dentistry market is shaped by strong competition among global and specialized players. Key companies include Aseptico Inc., Medtronic, Biolase, Inc., Straumann Group, Neocis, Synaptive Medical, and Zimmer Biomet. These firms focus on innovation, strategic partnerships, and product development to expand their presence. It emphasizes advanced robotic systems with AI integration, precision tools, and digital platforms to meet growing demand. Companies invest in training programs and research collaborations to strengthen clinical adoption. Leading players also pursue acquisitions and alliances to enhance technology portfolios and market reach. The competitive landscape reflects rapid technological progress and a strong push toward cost-efficient, user-friendly solutions.
Recent Developments:
- In June 2024, Aseptico introduced six new products including the GO Ultra Portable Dental System, their most advanced portable dental system with a built-in ultrasonic scaler designed for use in non-traditional locations.
- In February 2024, Biolase launched the Waterlase iPlus Premier Edition™, an all-tissue dental laser system featuring modular software design and remote diagnostics at the Chicago Midwinter Meeting.
- In April 2025, Medtronic received FDA approval for the Simplera Sync™ sensor for use with the MiniMed™ 780G insulin delivery system, with a limited U.S. launch planned for fall 2025.
Report Coverage:
The research report offers an in-depth analysis based on Product & Services, Application, End-use and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The robotic dentistry market will see wider integration of AI and machine learning for advanced treatment planning.
- It will experience stronger adoption in implantology and orthodontics due to rising demand for precision.
- Robotic platforms will evolve into compact and user-friendly systems suited for small and mid-sized clinics.
- It will expand through partnerships between technology firms, dental schools, and healthcare providers.
- Training programs with robotic simulators will help dentists adapt faster to new technologies.
- The market will benefit from growing demand for minimally invasive and patient-centric dental procedures.
- It will gain momentum in emerging economies as governments invest in modern dental infrastructure.
- Integration with digital dentistry, including CAD/CAM and 3D imaging, will drive system efficiency.
- It will attract strong investment from global manufacturers focused on innovation and cost optimization.
- Increasing patient awareness of advanced robotic-assisted treatments will further accelerate adoption across regions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the robotic dentistry market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the robotic dentistry market projected to grow between 2024 and 2032?
Which robotic dentistry market segment held the largest share in 2024?
What are the primary factors fueling the growth of the robotic dentistry market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Robotic Dentistry Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Robotic Dentistry Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 523.8 million → 2032: USD 1620.2 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Robotic Dentistry Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Robotic Dentistry Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Robotic Dentistry Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Robotic Dentistry Market Drivers
- 3.3 Robotic Dentistry Market Restraints & Challenges
- 3.4 Robotic Dentistry Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Robotic Dentistry Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Robotic Dentistry Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Robotic Dentistry category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Robotic Dentistry Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Robotic Dentistry Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Robotic Dentistry market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Robotic Dentistry Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Robotic Dentistry Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Robotic Dentistry Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Robotic Dentistry (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Robotic Dentistry Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Robotic Dentistry Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Robotic Dentistry Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Robotic Dentistry Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Robotic Dentistry Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Robotic Dentistry Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Robotic Dentistry Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Robotic Dentistry Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Robotic Dentistry Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
