
Blood Meal Market Overview:
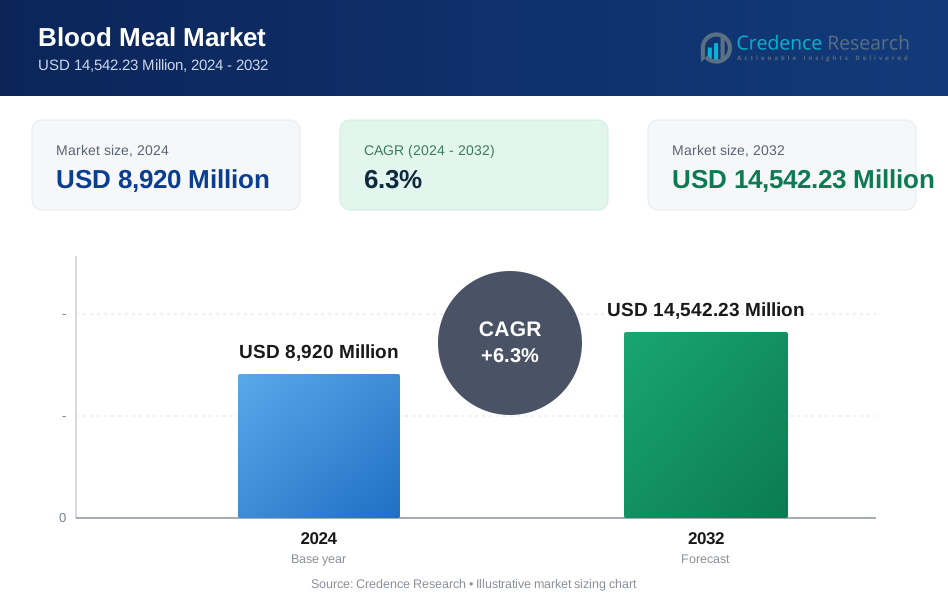
Blood Meal Market size was valued USD 8,920 Million in 2024 and is anticipated to reach USD 14,542.23 Million by 2032, at a CAGR of 6.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Blood Meal Market Size 2024 | USD 8,920 million |
| Blood Meal Market, CAGR | 6.3% |
| Blood Meal Market Size 2032 | USD 14,542.23 million |
Blood Meal Market Insights
- Market overview highlights rising demand for high-protein feed ingredients across poultry, swine, ruminant, and aquaculture sectors, with the poultry feed segment holding a dominant 42.7% share in 2024 due to strong adoption in commercial livestock production and cost-efficient nutrition benefits.
- Market drivers include expansion of meat processing industries, growth in sustainable by-product utilization, and increasing use of blood meal as an organic fertilizer in regenerative and organic farming systems, supporting value recovery and circular-economy practices.
- Market trends and competitive analysis indicate investments in spray-drying and advanced rendering technologies, product standardization, and capacity upgrades by key players to enhance quality consistency, safety compliance, and export competitiveness across global feed supply chains.
- Regional analysis shows Asia-Pacific leading the market with a 34.6% share in 2024, followed by North America at 29.4% and Europe at 23.8%, while Latin America and Middle East & Africa together accounted for the remaining share, supported by expanding livestock industries and improving processing infrastructure.

Blood Meal Market Segmentation Analysis:
By Source
The Blood Meal market by source is dominated by the poultry blood segment, which accounted for 48.6% share in 2024, driven by its high protein concentration, wide availability from poultry processing plants, and strong demand in animal nutrition formulations. Porcine blood held 31.4% share, supported by its use in swine and aquaculture feed owing to favorable amino acid profiles and digestibility. Ruminant blood contributed 20.0% share, primarily used in ruminant and specialty feed applications. Growth across all sub-segments is supported by rising meat production, increasing focus on sustainable protein recovery, and expanding feed manufacturing capacity.
- For instance, Tyson Foods reported processing over 2 billion chickens annually in the U.S. in recent years, providing a consistent stream of poultry by‑products that can be rendered into high‑protein blood meal for feed applications.
By Application
In the Blood Meal market by application, poultry feed emerged as the dominant sub-segment with 42.7% share in 2024, driven by increasing broiler production, demand for cost-efficient protein supplements, and nutritional benefits such as improved growth performance and feed conversion ratios. Porcine feed accounted for 21.9% share, followed by ruminant feed with 15.6% share, supported by integration into livestock nutrition programs. Aqua feed represented 11.8% share, while organic fertilizer and natural pest deterrent applications together contributed 8.0% share, fueled by organic farming expansion and rising preference for sustainable soil-enrichment solutions.
- For instance, commercial nutrition programs referenced by entities such as the U.S. Poultry & Egg Association highlight the use of rendered animal proteins to enhance amino acid balance and feed efficiency in broiler rations.
By Process
By process, the Blood Meal market is led by the spray drying segment, which held 36.9% share in 2024, driven by its ability to retain nutrient quality, deliver uniform particle size, and enhance product digestibility for high-value feed applications. Drum drying accounted for 28.4% share due to its cost efficiency and suitability for bulk processing. Solar drying represented 18.7% share, favored in low-cost, small-scale production environments. Ring and flash drying contributed 16.0% share, supported by its rapid moisture-reduction capability and growing adoption in advanced processing facilities to improve product stability and shelf life.
Key Growth Drivers
Rising Demand for High-Protein Animal Feed Supplements
The Blood Meal market is experiencing strong growth due to the increasing demand for high-protein feed ingredients across poultry, swine, ruminant, and aquaculture industries. Blood meal contains up to 80–90% crude protein with a rich amino acid profile, making it an effective alternative to soybean meal and fishmeal in livestock diets. Feed manufacturers prefer blood meal for its nutritional efficiency, digestibility benefits, and ability to improve weight gain and feed conversion ratios. Rapid expansion in commercial livestock farming and intensifying meat production across emerging economies further accelerate consumption. Additionally, rising awareness of performance-enhancing protein concentrates in feed formulations encourages greater adoption among integrated producers and contract farmers. The shift toward cost-efficient feed inputs amid fluctuating plant-protein prices also strengthens market penetration. Together, these factors position blood meal as a strategic protein source supporting productivity, profitability, and nutritional sustainability in the global animal feed sector.
- For instance, the FAO and various feed formulation guidelines document the use of spray‑dried blood products to enhance lysine content and overall protein density in monogastric diets.
Expansion of Meat Processing and Slaughterhouse By-Product Utilization
Market growth is strongly supported by the structural expansion of meat processing industries and improved utilization of slaughterhouse by-products. As global meat production increases, the volume of animal blood generated during processing rises correspondingly, creating significant opportunities for value-added recovery through rendering and protein extraction. Governments and industry bodies increasingly promote circular-economy practices, encouraging waste minimization and by-product valorization. Blood meal production aligns with these sustainability objectives by converting waste streams into economically valuable feed and fertilizer inputs. Modern rendering facilities and technological advancements in drying and processing enhance product consistency and safety standards, which strengthens acceptance among feed producers. Moreover, regulatory focus on environmental compliance and responsible waste disposal incentivizes processors to invest in blood meal production infrastructure. These developments collectively transform animal blood from a disposal challenge into a strategic raw material stream, supporting both sustainability goals and revenue diversification within the meat processing ecosystem.
- For instance, the European Union’s waste and by‑product regulations and initiatives on circular economy, along with sustainability frameworks adopted by meat companies in their ESG reports, explicitly emphasize improved rendering and by‑product utilization.
Growing Adoption of Organic and Sustainable Agricultural Inputs
The increasing shift toward organic farming and eco-friendly soil nutrition solutions is emerging as a key growth driver for the Blood Meal market. Blood meal is widely used as a natural nitrogen-rich fertilizer and soil amendment that supports plant growth, soil conditioning, and microbial activity without relying on synthetic chemical inputs. Demand is rising from organic crop producers, horticulture applications, and home gardening segments, particularly in regions emphasizing regenerative and sustainable agriculture. The product’s high nitrogen content enables faster nutrient release compared to plant-based organic fertilizers, making it attractive for high-value crops and specialty cultivation. Growing consumer preference for organically grown food and stricter restrictions on chemical fertilizers further stimulate adoption. Additionally, sustainability-driven procurement policies and environmental certifications encourage wider use of natural input materials. This expanding role of blood meal beyond feed applications strengthens its market relevance across both agricultural input and environmental sustainability value chains.
Key Trends & Opportunities
Technological Advancements in Processing and Product Standardization
A major trend shaping the Blood Meal market is the increasing adoption of advanced processing technologies, such as spray drying, ring and flash drying, and controlled thermal treatment, which enhance product quality, safety, and nutrient retention. These innovations enable manufacturers to produce highly consistent and microbiologically safe protein concentrates suitable for premium feed applications. Standardization initiatives, improved traceability, and quality-assurance protocols are also gaining prominence, supporting wider acceptance among multinational feed companies and export-oriented producers. Opportunities emerge in developing specialized blood meal grades tailored for aquafeed, pet nutrition, and high-performance livestock diets. Integration of automation, energy-efficient drying solutions, and hygienic processing equipment reduces operational costs and strengthens scalability. Companies investing in R&D, process optimization, and certification-compliant production capabilities are well-positioned to capture higher-value market segments and expand their global footprint as the industry transitions toward more technology-driven and quality-focused supply chains.
- For instance, spray‑dried blood products are widely documented in feed industry literature and by companies supplying processed animal proteins for use in piglet, aquafeed, and pet nutrition due to their high digestibility and standardized quality.
Diversification into Fertilizer, Bioproduct, and Circular-Economy Applications
Another key trend in the Blood Meal market is the diversification of applications beyond traditional animal feed toward organic fertilizers, bio-based agricultural inputs, and emerging circular-economy product streams. Increasing interest in sustainable nutrient recycling and soil-health enhancement opens opportunities for blood meal use in organic crop cultivation, landscaping, and specialty agriculture sectors. Manufacturers are also exploring integration into composite fertilizers, controlled-release nutrient blends, and pest-deterrent formulations. Growth opportunities extend to bioproduct development, including bio-stimulants and carbon-efficient farming inputs aligned with environmental regulatory frameworks. Partnerships between rendering companies, fertilizer producers, and agritech innovators are expanding product portfolios and market reach. As agricultural stakeholders prioritize eco-friendly input substitution and resource-efficient nutrient cycles, blood meal is gaining strategic positioning as a renewable, value-recovered material. This diversification enhances revenue resilience and strengthens the product’s role across interconnected agri-food and sustainability-oriented markets.
- For instance, organic and regenerative farming guidelines promoted by bodies such as USDA‑Organic and IFOAM recognize animal‑derived meals, including blood meal, as allowable nutrient sources under defined processing and application conditions.
Key Challenges
Regulatory Compliance, Quality Variability, and Safety Concerns
One of the major challenges in the Blood Meal market arises from stringent regulatory frameworks, quality-control requirements, and safety-related concerns across different regions. Variations in sourcing conditions, processing standards, and hygienic handling practices can create inconsistencies in nutrient content, digestibility, and microbiological safety. Compliance with feed safety laws, animal-by-product regulations, and international trade standards demands significant investment in testing, traceability, and certification processes, increasing production and operational costs. Perception-based concerns related to disease transmission risks or contamination further require robust assurance mechanisms and transparent quality governance. Smaller producers often face barriers in meeting export requirements and competing with technologically advanced rendering facilities. Any lapses in regulatory compliance may result in trade restrictions, reputational risk, or supply disruptions. Addressing these challenges requires continuous technological upgrades, rigorous quality monitoring, standardized processing protocols, and industry collaboration to strengthen trust and regulatory alignment across global markets.
Raw Material Dependency, Price Fluctuations, and Ethical Constraints
The Blood Meal market also faces challenges related to raw-material dependency on slaughterhouse operations, seasonal livestock processing cycles, and fluctuating meat industry dynamics. Variability in animal slaughter volumes directly influences feedstock availability and pricing stability, which can affect supply planning for feed manufacturers and fertilizer producers. Competition from alternative protein sources such as fishmeal, plant-based concentrates, and synthetic amino acids may intensify during periods of price volatility. Ethical and consumer perception concerns regarding animal-derived inputs in agriculture and feed systems also create resistance in certain market segments. In addition, logistical constraints, storage requirements, and transport costs contribute to operational complexity, particularly in developing markets with limited processing infrastructure. Overcoming these challenges requires diversification of sourcing networks, supply-chain resilience strategies, investment in local rendering capacity, and clear communication of sustainability and circular-resource benefits to balance ethical expectations with functional and economic advantages.
Regional Analysis
North America
North America held a significant position in the Blood Meal market with a 29.4% share in 2024, supported by the strong presence of industrial livestock farming, advanced rendering infrastructure, and high adoption of protein-rich feed ingredients. The United States leads regional demand due to large-scale poultry and swine production, organized slaughterhouse networks, and established feed manufacturing facilities. Increasing integration of sustainable by-product utilization and regulatory emphasis on waste valorization further strengthen market growth. Rising use of blood meal in organic fertilizer applications and gardening segments also contributes to incremental demand, particularly across specialty crop and horticulture production systems.
Europe
Europe accounted for 23.8% share of the Blood Meal market in 2024, driven by its well-regulated rendering sector, strong focus on circular bioeconomy practices, and increasing demand for high-quality animal nutrition inputs. Countries such as Germany, France, Spain, and Poland contribute significantly due to organized meat processing and intensive livestock farming structures. The region benefits from stringent environmental compliance, standardized processing methods, and traceability systems that enhance product acceptance among commercial feed manufacturers. Growth is further supported by the rising adoption of organic farming, where blood meal is used as a nitrogen-rich natural fertilizer across horticulture, crop cultivation, and landscaping applications.
Asia-Pacific
Asia-Pacific dominated the global Blood Meal market with a 34.6% share in 2024, emerging as the largest and fastest-growing region due to rapid expansion of poultry, swine, and aquaculture production across China, India, Vietnam, Indonesia, and Thailand. The region benefits from rising animal protein consumption, large-scale meat processing activity, and increasing adoption of cost-efficient protein concentrates in commercial feed formulations. Expanding aquafeed manufacturing and feed export industries further stimulate demand. Investments in rendering capacity, improving processing technologies, and growing awareness of by-product recovery as a sustainable resource also strengthen market penetration across both feed and organic fertilizer applications.
Latin America
Latin America represented 7.6% share of the Blood Meal market in 2024, supported by the expanding livestock and poultry sectors in Brazil, Mexico, Argentina, and Chile. The region benefits from rising feed production, export-oriented meat processing, and increasing utilization of slaughterhouse by-products for value-added applications. Growing adoption of blood meal in poultry and swine feed nutrition, along with its emerging use in organic agriculture and soil-enrichment programs, strengthens market growth. However, infrastructure gaps and supply-chain inefficiencies in certain countries moderate adoption levels, encouraging investments in modern rendering facilities and processing upgrades to improve product quality and consistency.
Middle East & Africa
The Middle East & Africa accounted for a 4.6% share of the Blood Meal market in 2024, driven by gradual expansion of poultry and ruminant production, increasing feed manufacturing capacity, and rising interest in sustainable nutrient recovery practices. Demand is growing in Gulf countries, South Africa, Egypt, and Kenya, where livestock intensification and feed efficiency improvement initiatives support adoption. Blood meal is also gaining traction in organic crop cultivation and soil-fertility management across niche agricultural segments. However, limited rendering infrastructure and dependency on imports in certain markets present challenges, prompting strategic investments in local processing and technology enhancement initiatives.
Blood Meal Market Segmentations:
By Source
- Poultry blood
- Porcine blood
- Ruminant blood
By Application
- Poultry Feed
- Porcine Feed
- Ruminant Feed
- Aqua Feed
- Natural Pest Deterrent
- Organic Fertilizer
By Process
- Solar Drying
- Drum Drying
- Spray Drying
- Ring and Flash Drying
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape in the Blood Meal market is characterized by the presence of integrated rendering companies, feed ingredient suppliers, and fertilizer input manufacturers that compete on product quality, processing technology, sourcing reliability, and regional supply capabilities. Key players operating in the market include Darling Ingredients, Sanimax Group, Hamlet Protein, NexGen Bioproducts, Moy Park, PBFS, GNT Group, Grenada Beef, Gea Farm Technologies, and Bio-Nutrition, along with several regional processors and specialized feed producers. These companies focus on strengthening raw-material procurement networks, enhancing drying and sterilization technologies, and developing standardized, high-protein blood meal grades for poultry, swine, ruminant, and aquafeed applications. Strategic priorities also include expansion into organic fertilizer and sustainable agriculture segments, portfolio diversification, and compliance with stringent feed safety and environmental regulations. Market participants are increasingly investing in capacity upgrades, supply-chain traceability, and international certifications to improve export competitiveness, while collaborations with feed manufacturers and agri-input distributors support broader market penetration across emerging and developed economies.
Key Player Analysis
- PBFS
- Moy Park
- Sanimax Group
- Bio-Nutrition
- Darling Ingredients
- NexGen Bioproducts
- Hamlet Protein
- GNT Group
- Grenada Beef
- Gea Farm Technologies
Recent Developments
- In June 2025, Hamlet Protein launched a new product, HP 270, at the World Pork Expo in the USA, aimed at providing a cost-effective fast protein feed solution for swine nutrition
- In May 2025, Darling Ingredients Inc. signed a non-binding term sheet with Tessenderlo Group to form a new joint venture company called Nextida™, combining collagen and gelatin segments to accelerate product development and growth.
- In August 2023, NexGen Bioproducts introduced an advanced blood meal processing technique that reduces energy consumption while improving product quality, marking a technological advancement in blood meal production.
Report Coverage
The research report offers an in-depth analysis based on Source, Application, Process and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness steady growth as livestock intensification and commercial poultry farming continue to expand across emerging economies.
- Demand for high-protein feed ingredients will increase as producers prioritize feed efficiency, weight-gain performance, and nutritional consistency in animal diets.
- Adoption of blood meal in aquafeed formulations will rise with the expansion of fish farming and the search for cost-effective alternatives to fishmeal.
- The role of blood meal in organic and sustainable agriculture will strengthen as farmers shift toward natural fertilizer and soil-nutrition inputs.
- Manufacturers will invest in advanced drying and sterilization technologies to improve product safety, digestibility, and nutrient retention.
- Regulatory focus on waste valorization and circular-resource utilization will support higher by-product recovery from meat processing facilities.
- Market participants will expand capacity and strengthen sourcing networks to ensure reliable raw-material availability and supply stability.
- Product standardization and certification compliance will become increasingly important for international trade and export-oriented supply chains.
- Competition from alternative protein sources will encourage innovation in specialized blood meal grades for premium feed applications.
- Strategic partnerships between rendering companies, feed manufacturers, and fertilizer producers will expand application opportunities and market reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Blood Meal Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Blood Meal Market projected to grow between 2024 and 2032?
Which Blood Meal Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Blood Meal Market?
Who are the leading companies in the Blood Meal Market?
Which region commanded the largest share of the Blood Meal Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Blood Meal Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Blood Meal Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 8,920 Million → 2032: USD 14,542.23 Million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Blood Meal Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Blood Meal Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Blood Meal Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Blood Meal Market Drivers
- 3.3 Blood Meal Market Restraints & Challenges
- 3.4 Blood Meal Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Blood Meal Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Blood Meal Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Blood Meal category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Blood Meal Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Blood Meal Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Blood Meal market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Blood Meal Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Blood Meal Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Blood Meal Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Blood Meal (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Blood Meal Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Blood Meal Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Blood Meal Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Blood Meal Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Blood Meal Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Blood Meal Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Blood Meal Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Blood Meal Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Blood Meal Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
