
Market Overview:
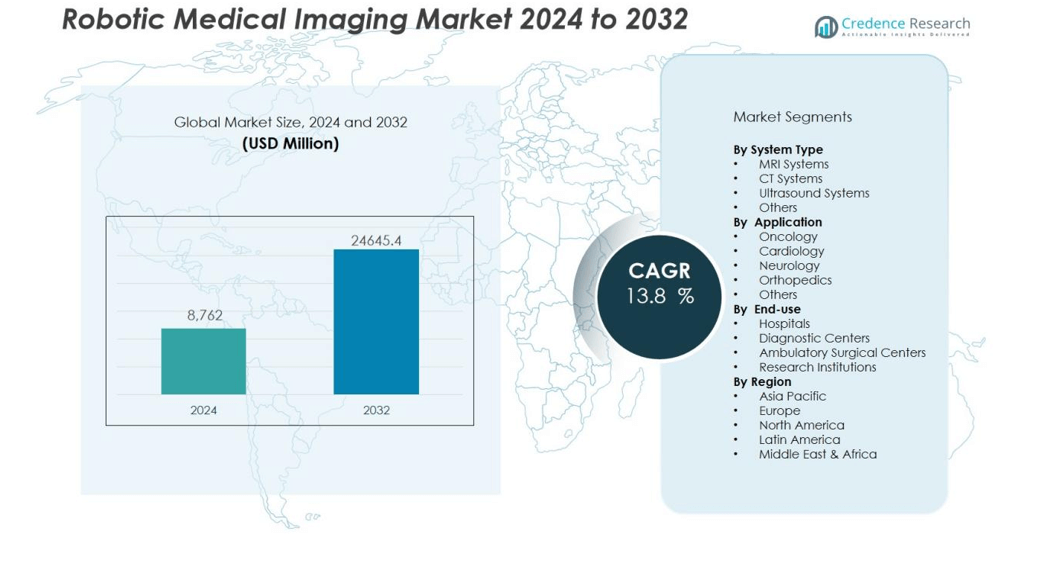
The robotic medical imaging market size was valued at USD 8,762 million in 2024 and is anticipated to reach USD 24645.4 million by 2032, at a CAGR of 13.8 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Robotic Medical Imaging Market Size 2024 | USD 8,762 million |
| Robotic Medical Imaging Market, CAGR | 13.8% |
| Robotic Medical Imaging Market Size 2032 | USD 24645.4 million |
Key growth drivers include the rising prevalence of chronic diseases, demand for minimally invasive diagnostic procedures, and the need for improved surgical accuracy. Hospitals and diagnostic centers are rapidly adopting robotic imaging solutions to enhance efficiency, reduce human error, and improve patient outcomes. Continuous innovations in MRI, CT, and ultrasound platforms, along with growing investments in medical robotics, are further accelerating adoption across clinical practices.
Regionally, North America leads the robotic medical imaging market due to advanced healthcare infrastructure, high adoption of robotic-assisted technologies, and supportive reimbursement policies. Europe follows, supported by strong R&D investments and expanding use in major economies such as Germany, France, and the U.K. Asia-Pacific is anticipated to register the fastest growth, fueled by rising healthcare spending, expanding hospital networks, and government initiatives promoting medical technology adoption in China, India, and Japan.
Market Insights:
- The robotic medical imaging market was valued at USD 8,762 million in 2024 and is projected to reach USD 24,645.4 million by 2032, growing at a CAGR of 13.8%.
- Rising prevalence of cancers, cardiovascular, and neurological disorders is driving strong demand for robotic-assisted diagnostic solutions.
- Growing preference for minimally invasive procedures supports wider adoption of real-time, high-definition imaging systems in hospitals and surgical centers.
- Integration of AI and automation improves accuracy, reduces human error, and enables clinicians to handle higher patient volumes efficiently.
- High equipment costs and limited accessibility in smaller healthcare facilities continue to restrict adoption in cost-sensitive regions.
- North America led with 41% market share in 2024, followed by Europe at 29%, while Asia-Pacific captured 23% and is expected to witness the fastest growth.
- Investments in portable imaging platforms, tele-imaging solutions, and hybrid systems are creating new opportunities for improved patient outcomes and broader market expansion.
Market Drivers:
Rising Prevalence of Chronic Diseases Driving Imaging Demand:
The growing incidence of chronic conditions such as cardiovascular diseases, cancers, and neurological disorders has increased reliance on advanced imaging tools. Robotic medical imaging market growth is supported by the need for precise diagnostics in complex cases. Robotic-assisted systems improve visualization, accuracy, and speed in detecting abnormalities. It helps healthcare providers reduce misdiagnosis and enhance treatment planning efficiency.
- For instance, GE HealthCare's AI-enabled devices have received 58 FDA clearances, the most in the industry, and their Critical Care Suite was among the first AI triage tools cleared for detecting pneumothorax on chest X-rays-a major technological milestone improving diagnostic workflows.
Increasing Shift Toward Minimally Invasive Procedures:
Patients and healthcare providers prefer minimally invasive interventions due to shorter recovery times and reduced risks. Robotic medical imaging market expansion benefits from technologies that support these procedures with high-definition imaging and navigation. Real-time imaging guidance allows surgeons to perform delicate operations with precision. It enhances patient outcomes and minimizes hospital stays, boosting adoption in surgical departments.
- For instance, Intuitive Surgical’s da Vinci Surgical System performed over 2.2 million procedures globally in 2023. Its 3D high-definition vision system enabled precise minimally invasive surgeries, contributing to faster patient discharge rates.
Integration of Artificial Intelligence and Automation in Imaging:
AI and automation are transforming medical imaging by improving efficiency and decision-making. The robotic medical imaging market leverages AI-driven platforms for image analysis, workflow optimization, and predictive diagnostics. Intelligent automation reduces human error and accelerates diagnostic processes. It enables clinicians to make data-driven decisions while handling higher patient volumes.
Growing Investments in Healthcare Infrastructure and Technology:
Governments and private healthcare providers are investing heavily in advanced medical technologies. The robotic medical imaging market benefits from these initiatives aimed at modernizing hospitals and diagnostic centers. Investments in robotics, digital healthcare, and precision imaging tools improve accessibility and affordability. It ensures broader adoption across developed and emerging economies, fueling long-term market expansion.
Market Trends:
Growing Adoption of AI-Integrated and Real-Time Imaging Solutions:
Artificial intelligence and real-time imaging are becoming central to modern healthcare systems. Hospitals are deploying robotic platforms integrated with AI algorithms to improve image interpretation and diagnostic accuracy. The robotic medical imaging market benefits from AI’s role in automating workflows, reducing human error, and enhancing decision support for clinicians. Real-time imaging technologies, particularly in MRI and CT systems, are enabling faster assessments during surgeries and complex procedures. It allows physicians to navigate with greater precision and improve patient outcomes. The trend also aligns with the broader shift toward data-driven and personalized medicine in clinical settings.
- For instance, Medtronic’s O-arm imaging system provides intraoperative 3D imaging with scan times as fast as 13 seconds, leading to improved surgical navigation and accuracy in more than 1,000 hospitals globally .
Rising Focus on Tele-Imaging, Remote Diagnostics, and Hybrid Imaging Platforms:
Healthcare providers are embracing tele-imaging solutions to address workforce shortages and extend diagnostic capabilities to underserved areas. Robotic medical imaging systems integrated with cloud connectivity support remote consultations and real-time collaboration among specialists. Hybrid imaging platforms that combine modalities such as PET-CT or MRI-ultrasound are gaining prominence for offering comprehensive diagnostic insights. It strengthens treatment planning and reduces the need for multiple diagnostic sessions. Growing demand for portable and compact robotic imaging devices is also shaping purchasing preferences in outpatient and emergency care facilities. The expansion of these technologies reflects the industry’s shift toward accessibility, flexibility, and efficiency in advanced medical imaging.
- For instance, Brainlab's Loop-X mobile robotic imaging system operates within a compact footprint of only 1.5 square meters while featuring a large 43 cm x 43 cm flat-panel detector.
Market Challenges Analysis:
High Costs and Limited Accessibility Restricting Adoption:
The robotic medical imaging market faces a significant challenge in managing high equipment and installation costs. Advanced robotic platforms require large capital investments, making them less accessible for smaller hospitals and clinics. High maintenance expenses and the need for skilled operators further add to the financial burden. It restricts adoption in price-sensitive regions where healthcare budgets are limited. Lack of affordable financing models also limits market penetration, particularly in emerging economies. This creates a gap between developed and developing markets in terms of access to advanced imaging technologies.
Regulatory Barriers and Integration Complexities:
Strict regulatory approvals for robotic medical imaging devices delay product launches and slow adoption. Manufacturers must comply with complex standards, leading to higher costs and longer timelines. Integration with existing healthcare IT systems, such as electronic health records and hospital infrastructure, also presents operational challenges. It often requires customization and training, which can delay clinical use. Concerns over data privacy and cybersecurity further complicate deployment in connected imaging systems. Limited awareness and hesitation among medical professionals to adopt new technologies also affect overall market growth. These factors collectively challenge the scalability of robotic imaging solutions across global markets.
Market Opportunities:
Expansion Potential in Emerging Healthcare Markets:
Rising investments in healthcare infrastructure across emerging economies create strong opportunities for robotic imaging technologies. Countries in Asia-Pacific, Latin America, and the Middle East are increasing spending on advanced medical equipment. The robotic medical imaging market can benefit from government-backed modernization programs and growing private sector involvement. It enables hospitals in developing regions to adopt cutting-edge imaging systems, expanding patient access to high-quality care. Increasing demand for early diagnosis of chronic diseases further strengthens this potential. Partnerships with local distributors and healthcare providers can accelerate market penetration in these fast-growing regions.
Innovation in AI-Powered and Portable Imaging Platforms:
Continuous innovation in AI-powered robotic platforms opens opportunities to improve diagnostic accuracy and speed. Portable and compact imaging devices are gaining traction in outpatient clinics, emergency departments, and remote care centers. The robotic medical imaging market is well positioned to capture demand for solutions that combine portability, precision, and connectivity. It also benefits from growing telemedicine adoption, which requires integrated robotic imaging support for remote consultations. Hybrid imaging technologies, combining modalities such as MRI-ultrasound, present new avenues for clinical efficiency. Companies investing in R&D and partnerships can capitalize on these evolving needs and secure long-term growth.
Market Segmentation Analysis:
By System Type:
The robotic medical imaging market is segmented into MRI systems, CT systems, ultrasound systems, and others. MRI systems lead due to their ability to deliver detailed imaging for neurological and cardiovascular cases. CT systems gain demand in oncology and trauma care where speed and precision are critical. Ultrasound systems show steady growth, supported by portability and use in real-time surgical guidance. It benefits from technological integration that enhances diagnostic performance across multiple departments.
- For instance, the Monteris NeuroBlate System, which is FDA-cleared for MRI-guided neurosurgery, enables robotically controlled laser thermotherapy for brain tumor ablation. The system achieves high precision, with its thermography software calculating the thermal dose threshold (TDT) lines within an average accuracy of \(1.5\pm 0.7\) mm.
By Application:
Key applications include oncology, cardiology, neurology, orthopedics, and others. Oncology dominates due to rising cancer prevalence and demand for accurate tumor detection and monitoring. Cardiology follows with adoption of robotic-assisted systems in interventional procedures requiring high-resolution imaging. Neurology applications benefit from precision imaging in brain and spinal diagnostics. Orthopedic procedures increasingly rely on robotic imaging for surgical navigation and implant positioning. It strengthens overall adoption across diverse clinical specialties.
- For instance,the MAKO Total Knee system achieves 94.29% of bone resections within 1mm of surgical plan with mean alignment accuracy of 0.78° (±0.78°)
By End-Use:
Hospitals account for the largest share due to high patient volumes, advanced infrastructure, and greater capital availability. Diagnostic centers adopt robotic imaging systems to improve accuracy and speed of routine diagnostics. Ambulatory surgical centers gain traction with compact robotic platforms supporting minimally invasive procedures. Research institutions also invest in robotic imaging for clinical studies and innovation in treatment planning. It ensures broad end-use adoption, strengthening the market’s long-term growth trajectory.
Segmentations:
By System Type:
- MRI Systems
- CT Systems
- Ultrasound Systems
- Others
By Application:
- Oncology
- Cardiology
- Neurology
- Orthopedics
- Others
By End-Use:
- Hospitals
- Diagnostic Centers
- Ambulatory Surgical Centers
- Research Institutions
By Region:
North America- U.S.
- Canada
- Mexico
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Brazil
- Argentina
- Rest of Latin America
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America:
North America held 41% market share in 2024, supported by high adoption of robotic-assisted technologies. The region benefits from advanced healthcare infrastructure, strong reimbursement systems, and a skilled medical workforce. The robotic medical imaging market in North America is driven by rapid integration of AI-enabled imaging solutions across hospitals and diagnostic centers. It gains further momentum from high prevalence of chronic diseases requiring advanced imaging for early detection. Strong investments in R&D by leading companies in the U.S. strengthen innovation pipelines. Favorable government support for digital health initiatives also drives market penetration across this region.
Europe:
Europe accounted for 29% market share in 2024, driven by growing demand for precision imaging. Countries such as Germany, France, and the U.K. lead adoption with significant healthcare spending and innovation capacity. The robotic medical imaging market benefits from strong regulatory frameworks that encourage safe and effective adoption of medical devices. It also sees higher uptake due to rising emphasis on minimally invasive surgeries across leading economies. Growing partnerships between hospitals and technology developers further expand deployment of robotic platforms. Public-private collaborations and continuous upgrades to healthcare infrastructure support sustained growth across Europe.
Asia-Pacific:
Asia-Pacific captured 23% market share in 2024, supported by rapid growth in healthcare infrastructure and spending. Rising patient populations and increasing cases of chronic diseases are accelerating demand for advanced imaging technologies. The robotic medical imaging market in Asia-Pacific benefits from government-backed initiatives promoting modernization of hospital facilities. It also gains traction from strong investments in medical robotics by countries such as China, India, and Japan. Expanding private healthcare providers further fuel the integration of robotic-assisted systems. Strong economic growth and increasing focus on early diagnostics are expected to maintain momentum across this region.
Key Player Analysis:
- Mazor Robotics
- Zimmer Biomet
- Philips Healthcare
- Varian Medical Systems
- Medtronic
- Neocis
- Accuray
- Siemens Healthineers
- Brainlab
- Intuitive Surgical
- Stryker
- Toshiba Medical Systems
Competitive Analysis:
The robotic medical imaging market is characterized by strong competition among global medical technology leaders. Key players include Mazor Robotics, Zimmer Biomet, Philips Healthcare, Varian Medical Systems, Medtronic, Neocis, and Accuray. These companies compete through advanced product portfolios, integration of AI, and expansion into minimally invasive imaging solutions. The market is shaped by continuous innovation in MRI, CT, and ultrasound platforms designed to improve precision and workflow efficiency. It benefits from strategic collaborations between healthcare providers and manufacturers aimed at expanding access to robotic-assisted systems. Partnerships, mergers, and acquisitions remain central strategies to strengthen global footprints. The competitive environment is expected to intensify with rising demand for cost-effective and portable imaging platforms.
Recent Developments:
- In January 2025, Bridgefield Capital entered into a definitive agreement to acquire the Philips Emergency Care Business, with the acquisition expected to close later in 2025 after regulatory approval.
- In January 2025, Zimmer Biomet agreed to acquire Paragon 28 for approximately $1.2 billion, targeting enhanced offerings in the orthopedic foot and ankle market, with closing anticipated in the first half of the year.
- In June 2025, Varian announced an expanded global partnership with Icon Group to deliver advanced cancer technology across the UK.
Report Coverage:
The research report offers an in-depth analysis based on System Type, Application, End-Use and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The robotic medical imaging market will expand with rising adoption of AI-powered diagnostic systems.
- Hospitals will prioritize real-time imaging platforms to support precision surgeries and complex procedures.
- Demand for minimally invasive procedures will strengthen adoption of robotic-assisted imaging solutions.
- Integration with telemedicine and remote diagnostics will increase deployment across connected healthcare networks.
- Portable and compact robotic imaging devices will gain traction in outpatient and emergency care facilities.
- Hybrid imaging technologies combining MRI, CT, and ultrasound will create new clinical efficiencies.
- Growing collaborations between technology firms and healthcare providers will accelerate innovation pipelines.
- Government initiatives to modernize healthcare infrastructure will drive adoption in emerging economies.
- Automation and machine learning will enhance workflow optimization and reduce diagnostic errors.
- Investments in cybersecurity and data privacy will ensure safer deployment of connected imaging platforms.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the robotic medical imaging market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the robotic medical imaging market projected to grow between 2024 and 2032?
Which robotic medical imaging market segment held the largest share in 2024?
What are the primary factors fueling the growth of the robotic medical imaging market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Robotic Medical Imaging Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Robotic Medical Imaging Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 8,762 million → 2032: USD 24,645.4 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Robotic Medical Imaging Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Robotic Medical Imaging Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Robotic Medical Imaging Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Robotic Medical Imaging Market Drivers
- 3.3 Robotic Medical Imaging Market Restraints & Challenges
- 3.4 Robotic Medical Imaging Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Robotic Medical Imaging Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Robotic Medical Imaging Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Robotic Medical Imaging category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Robotic Medical Imaging Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Robotic Medical Imaging Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Robotic Medical Imaging. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Robotic Medical Imaging Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Robotic Medical Imaging Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Robotic Medical Imaging Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Robotic Medical Imaging (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Robotic Medical Imaging
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Robotic Medical Imaging Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Robotic Medical Imaging Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Robotic Medical Imaging Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Robotic Medical Imaging Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Robotic Medical Imaging Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Robotic Medical Imaging Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Robotic Medical Imaging Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Robotic Medical Imaging Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
