
Market Overview
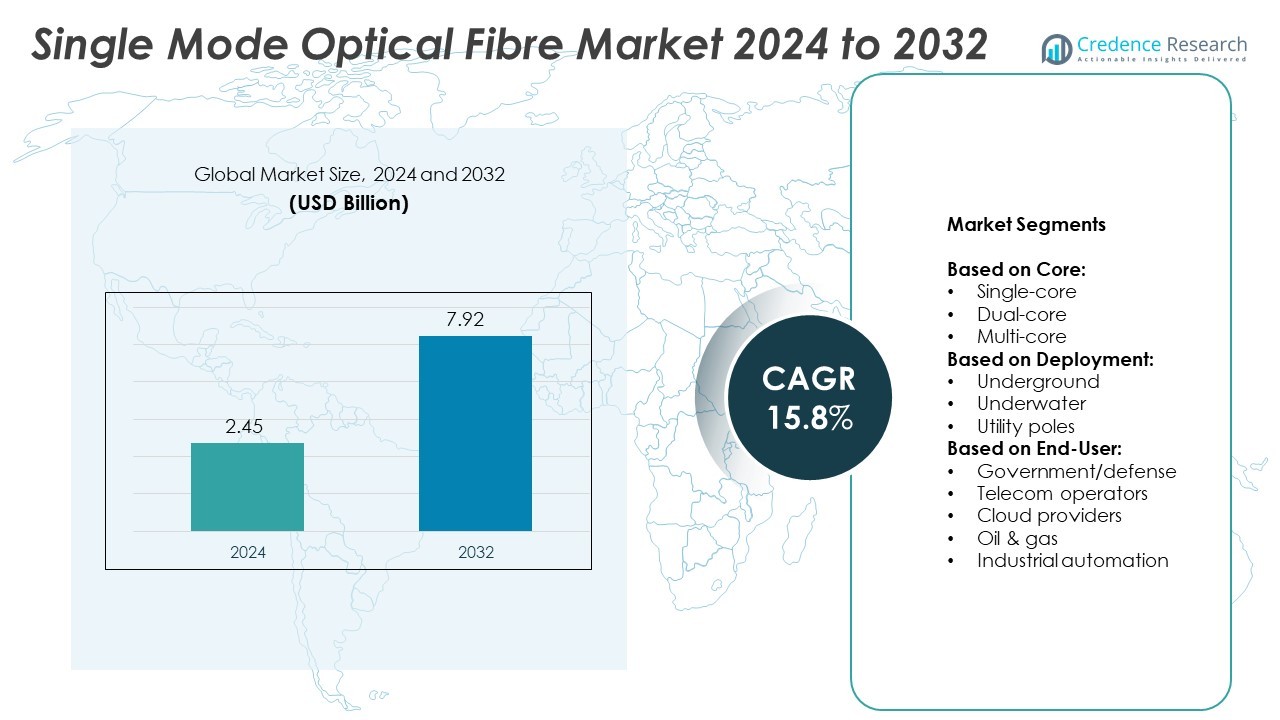
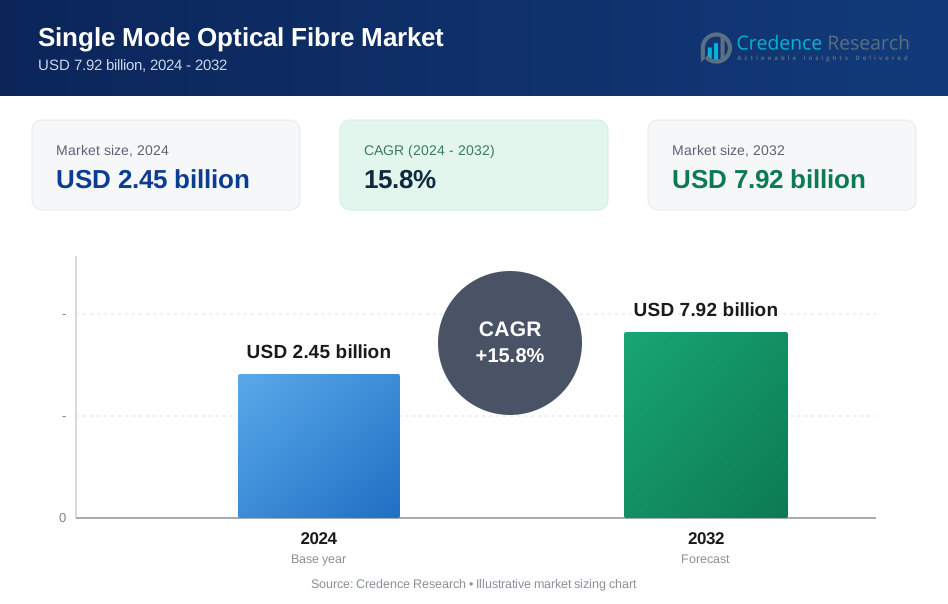
The Single Mode Optical Fibre Market size was valued at USD 2.45 billion in 2024 and is anticipated to reach USD 7.92 billion by 2032, at a CAGR of 15.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Single Mode Optical Fibre Market Size 2024 | USD 2.45 Billion |
| Single Mode Optical Fibre Market, CAGR | 15.8% |
| Single Mode Optical Fibre Market Size 2032 | USD 7.92 Billion |
The Single Mode Optical Fibre market grows rapidly, driven by the rising demand for high-speed connectivity across telecom, cloud computing, and data center networks. Expanding 5G rollouts and fibre-to-the-home projects strengthen adoption, supported by government investments in broadband and smart city initiatives. It benefits from increasing reliance on AI, IoT, and industrial automation that require low-latency and high-capacity networks. Trends highlight advancements in bend-insensitive and low-loss fibre designs that enhance efficiency and scalability.
Asia-Pacific leads the Single Mode Optical Fibre market, supported by large-scale 5G rollouts, broadband expansion, and strong fibre manufacturing capacity. North America follows with advanced telecom infrastructure and growing cloud adoption, while Europe emphasizes digital strategies and sustainability-driven fibre projects. Latin America and the Middle East & Africa show steady progress through government-backed broadband initiatives and undersea cable investments. Key players shaping the market include Prysmian, Corning, Sumitomo Electric, and Fujikura, each focusing on innovation and strategic partnerships to strengthen their global presence.
Market Insights
- The Single Mode Optical Fibre market was valued at USD 2.45 billion in 2024 and is projected to reach USD 7.92 billion by 2032, growing at a CAGR of 15.8% between 2025 and 2032.
- Strong demand for high-speed connectivity, expanding 5G infrastructure, cloud computing, and fibre-to-the-home deployments are driving adoption across both developed and emerging economies.
- Technological trends emphasize innovations in bend-insensitive and low-loss fibre designs, ensuring longer transmission distances, higher capacity, and improved efficiency for telecom and data center networks.
- The competitive landscape is defined by global leaders such as Prysmian, Corning, Sumitomo Electric, and Fujikura, supported by regional players offering cost-efficient alternatives tailored to local needs.
- High installation costs, complex deployment requirements, and supply chain vulnerabilities remain restraints that limit faster adoption in certain geographies, particularly rural and underserved regions.
- Asia-Pacific leads growth due to large-scale telecom projects and strong domestic fibre production, North America follows with advanced data centers and 5G rollouts, Europe shows steady growth with digital initiatives, while Latin America and the Middle East & Africa expand gradually through broadband and submarine cable projects.
- The market outlook reflects growing opportunities from smart city projects, AI-driven workloads, and undersea connectivity investments, with sustainability practices and resilient supply networks shaping long-term strategies for global adoption.
Market Drivers
Rising Adoption in Telecommunications and 5G Networks
The Single Mode Optical Fibre market benefits from the global shift toward high-speed and reliable communication infrastructure. Telecom operators deploy advanced networks to meet data traffic demand driven by smartphones, IoT devices, and streaming platforms. It supports long-distance transmission with minimal signal loss, making it ideal for core and metro networks. Governments and private players invest in 5G rollouts that require extensive fibre backhaul. Leading service providers extend fibre-to-the-home projects to improve connectivity. This trend positions single mode fibre as a foundation for modern digital ecosystems.
- For instance, Sumitomo Electric supplied over 20,000 kilometers of optical fibre for NTT’s 5G backhaul expansion in Japan in 2023.
Expanding Data Center Infrastructure and Cloud Computing Growth
Global cloud adoption and hyperscale data centers strengthen demand for efficient fibre solutions. Enterprises and consumers rely on cloud platforms that process enormous data volumes daily. The Single Mode Optical Fibre market gains traction through its ability to provide high bandwidth and low latency, essential for advanced computing environments. It integrates seamlessly into high-capacity links connecting global data hubs. Technology giants continue to scale networks for AI workloads, requiring superior fibre solutions. This creates steady deployment opportunities across established and emerging regions.
- For instance, corning delivered more than 100 million Homes globally in 2023, supporting large-scale data center connectivity.
Government Initiatives and Smart City Development Projects
Public sector investments in smart cities and national broadband initiatives enhance demand for advanced fibre infrastructure. The Single Mode Optical Fibre market aligns with strategic projects aimed at improving digital inclusion and e-governance services. It supports intelligent traffic management, surveillance systems, and energy-efficient grids. Developing economies prioritize large-scale fibre rollouts to bridge connectivity gaps. Policymakers allocate funds to rural broadband networks, increasing fibre penetration beyond urban areas. These efforts accelerate the long-term adoption curve across multiple sectors.
Advancements in Fibre Technology and Performance Enhancements
Continuous innovation improves the performance and efficiency of fibre solutions. The Single Mode Optical Fibre market benefits from advancements in bend-insensitive designs and low-loss cables. It ensures consistent transmission quality under demanding environmental conditions. Manufacturers develop fibres that meet the needs of 400G and 800G systems in next-generation networks. Research focuses on materials that reduce attenuation and expand transmission capacity. These technological gains reinforce fibre’s position as a critical enabler of global connectivity.
Market Trends
Growing Integration of Fibre in 5G and Next-Generation Networks
The Single Mode Optical Fibre market experiences momentum from the rapid global deployment of 5G technology. Network operators strengthen fibre backhaul to handle massive increases in mobile data traffic. It supports seamless connectivity between base stations and core networks with superior speed and reliability. Enterprises adopt private 5G networks for industrial automation and IoT applications, requiring advanced fibre infrastructure. Continuous investment in ultra-low latency communication accelerates this shift. These trends position fibre as the backbone of future telecommunications ecosystems.
- For instance, Prysmian delivered 6,000 kilometers of fibre cables for India’s BharatNet Phase-II broadband project in 2023.
Rising Demand from Hyperscale Data Centers and Cloud Services
The growth of hyperscale facilities and cloud platforms reshapes global fibre demand. The Single Mode Optical Fibre market supports ultra-fast data transfer across large networks connecting storage, compute, and application systems. It addresses the need for efficient, high-capacity links in regions with expanding AI and big data workloads. Cloud service providers expand transcontinental fibre routes to ensure uninterrupted services. Enterprises migrate critical workloads to distributed data centers that require scalable and reliable optical infrastructure. This sustained demand strengthens fibre’s relevance in modern computing ecosystems.
- For instance, Fujikura introduced a new ultra-low-loss fibre with 0.14 dB/km attenuation at 1550 nm wavelength.
Increasing Deployment in Smart Cities and IoT Infrastructure
Smart city development creates strong adoption opportunities for advanced fibre networks. The Single Mode Optical Fibre market aligns with projects integrating IoT-enabled systems for transportation, utilities, and security. It ensures uninterrupted connectivity for sensors, cameras, and automated services. Governments invest heavily in nationwide broadband plans to connect urban and rural populations. The expansion of intelligent grids and digital healthcare facilities relies on robust fibre deployment. These trends establish fibre as a strategic enabler of urban transformation.
Technological Innovations Driving Higher Capacity Solutions
Continuous innovation in fibre technology enhances efficiency and scalability. The Single Mode Optical Fibre market benefits from developments such as bend-insensitive fibre, low-loss cable designs, and compatibility with 400G and 800G systems. It supports transmission over longer distances without compromising performance. Manufacturers focus on advanced materials that minimize attenuation and increase bandwidth capacity. Research in ultra-dense wavelength division multiplexing extends the life of existing infrastructure. These advancements ensure fibre remains central to high-capacity global networks.
Market Challenges Analysis
High Installation Costs and Complex Deployment Requirements
The Single Mode Optical Fibre market faces barriers linked to the high cost of installation and infrastructure development. Extensive trenching, cabling, and network integration require significant capital investments, particularly in underserved or rural areas. It often involves challenges in securing rights-of-way and navigating regulatory frameworks that delay project execution. Network operators weigh the long-term benefits against immediate financial constraints, slowing widespread adoption. Smaller service providers find it difficult to compete with large incumbents that possess stronger resources. These cost and complexity issues limit the speed of global fibre rollout.
Supply Chain Vulnerabilities and Limited Skilled Workforce
The Single Mode Optical Fibre market encounters disruptions caused by global supply chain dependencies. Raw material shortages, shipping delays, and fluctuating commodity prices increase uncertainty for manufacturers. It also struggles with a shortage of skilled professionals capable of managing complex installation and maintenance tasks. The lack of technical expertise in emerging regions constrains the pace of adoption. Geopolitical tensions further add to risks, impacting cross-border trade of fibre components and equipment. These challenges underscore the importance of resilient supply networks and workforce development initiatives.
Market Opportunities
Expanding Role in Global 5G and Broadband Initiatives
The Single Mode Optical Fibre market presents strong opportunities through large-scale 5G deployments and national broadband projects. Governments allocate significant budgets to strengthen digital infrastructure and extend connectivity to underserved regions. It provides the backbone for high-speed, low-latency communication networks essential for industries and households. Telecom operators expand fibre-to-the-home and fibre-to-the-building initiatives to meet growing data consumption. The rise of private 5G networks for industrial automation further expands adoption. These opportunities reinforce fibre’s role as a critical enabler of next-generation connectivity.
Rising Demand from Cloud, AI, and Data Center Expansion
The Single Mode Optical Fibre market benefits from rapid growth in data-intensive technologies and hyperscale computing facilities. Cloud service providers and enterprises continue to expand global data center capacity to support AI, IoT, and big data applications. It enables high-capacity, low-loss transmission required for distributed workloads across regions. Demand for intercontinental fibre links rises as organizations seek to reduce latency in cross-border operations. Investments in undersea cable projects further highlight the growing reliance on fibre for global communication. These opportunities position fibre at the core of digital transformation worldwide.
Market Segmentation Analysis:
By Core:
The Single Mode Optical Fibre market demonstrates diverse growth potential across core types. Single-core fibres remain dominant due to their widespread use in telecom and broadband applications, offering high efficiency for long-distance transmission. Dual-core fibres gain adoption in specialized networks that require redundancy and improved data throughput. Multi-core fibres represent an emerging segment with strong potential in high-capacity data centers and advanced research networks. It provides enhanced bandwidth within a smaller footprint, making it attractive for next-generation connectivity demands. These variations highlight the adaptability of fibre solutions across evolving technological needs.
- For instance, Yangtze Optical Fibre and Cable supplied 10,000 kilometers of G.652D fibre for China Mobile’s 5G network expansion.
By Deployment:
It shape the pace and scope of fibre adoption. Underground deployment maintains a leading position, offering protection against environmental hazards and ensuring network stability in urban and rural areas. Underwater deployment expands rapidly with the rising need for international connectivity through submarine cable projects. Utility pole deployment remains cost-effective for shorter distances and regions where quick installation is required. The Single Mode Optical Fibre market gains strength from these deployment models, each addressing specific geographic and operational challenges. It ensures reliability across both domestic and cross-border communications.
- For instance, Nexans delivered 5,000 kilometers of fibre for Saudi Arabia’s NEOM smart city project.
By End-User:
It provide further clarity on demand drivers. Telecom operators account for the largest share, driven by fibre-to-the-home projects and 5G backhaul requirements. Government and defense agencies invest in secure and resilient fibre networks for national security and strategic communication. Cloud providers expand their reliance on fibre to connect hyperscale data centers and support AI-driven workloads. Oil and gas industries utilize fibre for monitoring and communication in remote and harsh environments. Industrial automation depends on high-speed, low-latency fibre to optimize operations and enable smart manufacturing. It continues to diversify adoption across multiple industries, reinforcing its role as a core enabler of digital infrastructure.
Segments:
Based on Core:
- Single-core
- Dual-core
- Multi-core
Based on Deployment:
- Underground
- Underwater
- Utility poles
Based on End-User:
- Government/defense
- Telecom operators
- Cloud providers
- Oil & gas
- Industrial automation
Based on the Geography:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- UK.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- The Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a market share of 24%, driven by advanced digital infrastructure and rapid expansion of high-speed connectivity projects. The United States leads the adoption with large-scale fibre-to-the-home deployments and extensive investment in 5G backhaul networks. It benefits from strong involvement of major telecom providers that continue to upgrade legacy systems with single mode fibre. Canada follows with government-backed broadband programs that extend connectivity to underserved rural and northern regions. Cloud service providers strengthen reliance on fibre to support hyperscale data centers and growing AI workloads. The Single Mode Optical Fibre market in North America grows steadily with rising demand for secure, reliable, and low-latency communication networks. It reinforces fibre as the backbone of next-generation digital services across the region.
Europe
Europe accounts for 18% of the market share, reflecting strong regulatory support and coordinated digital strategies across member states. The European Union’s initiatives to achieve widespread gigabit connectivity by 2030 encourage accelerated fibre deployment. It benefits from consistent investments in key markets such as Germany, France, and the United Kingdom, where telecom operators partner with governments to expand network reach. Industrial automation and energy sectors also contribute to demand, requiring high-speed and resilient connectivity. Data center growth in countries like Ireland and the Nordics further strengthens adoption of fibre for cross-border operations. The Single Mode Optical Fibre market in Europe demonstrates steady momentum, shaped by sustainability priorities and strong policy frameworks. It ensures the region continues to compete effectively in the global digital economy.
Asia-Pacific
Asia-Pacific dominates the global landscape with a market share of 41%, underscoring its leadership in telecom and broadband development. Countries such as China, Japan, South Korea, and India drive mass adoption through 5G rollouts and fibre-to-the-home projects. It supports exponential growth in data traffic generated by mobile usage, IoT devices, and video streaming platforms. Smart city initiatives and industrial digitalization further enhance reliance on fibre networks. The presence of large-scale fibre manufacturing hubs in China adds cost efficiency and accelerates deployment capacity. The Single Mode Optical Fibre market in Asia-Pacific thrives on both domestic consumption and global supply chain advantages. It maintains its leadership role by aligning with national digital infrastructure goals and enterprise modernization.
Latin America
Latin America represents 9% of the market share, showing gradual progress in fibre adoption compared to developed economies. Brazil, Mexico, and Chile lead investment in broadband infrastructure supported by government and private partnerships. It enables telecom operators to expand network coverage for a growing population of digitally active consumers. Undersea cable systems play a critical role in linking Latin American markets to global data hubs. Cloud adoption also grows steadily, prompting higher demand for reliable fibre networks. The Single Mode Optical Fibre market in Latin America benefits from industrial applications in oil, gas, and energy where remote operations require secure connectivity. It continues to build momentum as infrastructure challenges are addressed through public and private investment.
Middle East & Africa
The Middle East & Africa account for 8% of the market share, reflecting its status as an emerging but high-potential region. GCC countries spearhead adoption through ambitious projects in smart cities, broadband connectivity, and national digital transformation agendas. It supports telecom operators deploying fibre-to-the-home services to meet rising consumer and enterprise demand. Africa sees growing investment in both terrestrial and undersea fibre networks to bridge the connectivity gap across vast regions. Cloud service providers expand capacity in countries like South Africa and the UAE, reinforcing demand for advanced fibre infrastructure. The Single Mode Optical Fibre market in this region also benefits from investments in oil & gas and government modernization initiatives. It positions the region for sustained growth as infrastructure and access improve over time.
Key Player Analysis
- Prysmian
- Fujikura
- LS Cable and System
- Humanetics
- CommScope
- Yangtze Optical Fiber and Cable
- Sumitomo Electric
- Nexans
- Corning
- Birla Furukawa
- HTGD
- Furukawa
Competitive Analysis
The leading players in the Single Mode Optical Fibre market include Prysmian, Fujikura, LS Cable and System, Humanetics, CommScope, Yangtze Optical Fiber and Cable, Sumitomo Electric, Nexans, Corning, Birla Furukawa, HTGD, and Furukawa. These companies compete by leveraging advanced manufacturing capabilities, strong global distribution networks, and continuous investment in research and development. Innovation remains central, with emphasis on developing bend-insensitive, low-loss, and high-capacity fibre solutions that address the needs of 5G, cloud computing, and hyperscale data centers. Strategic collaborations with telecom operators and governments further strengthen their market positioning, enabling large-scale deployment projects worldwide. The competitive landscape also reflects a balance between regional dominance and global expansion strategies. Established players focus on strengthening supply chains and scaling production capacity to meet rising demand from broadband and smart city initiatives. Emerging players and regional manufacturers compete by offering cost-efficient solutions tailored to specific markets. Companies invest heavily in sustainability practices and advanced materials to align with evolving industry standards. Continuous expansion of undersea cable projects, coupled with growing demand for industrial automation, creates new opportunities for competition. The market remains highly dynamic, defined by technology leadership, pricing strategies, and the ability to address both mature and emerging economies effectively.
Recent Developments
- In 2025, Corning announced that it would showcase next‑generation fiber and cable solutions for AI networks Optical Fiber Communication Conference and Exposition, focusing on dense, scalable connectivity for data centers.
- In 2025, Prysmian entered a long‑term partnership with Relativity Networks, focusing on volume production of hollow‑core optical fiber and cable to support AI‑centric data centers
- In 2025, Prysmian launched its enhanced BendBrightXS 200 µm fibre, providing telecom operators with improved bend‑insensitive, future‑proof solutions
Market Concentration & Characteristics
The Single Mode Optical Fibre market shows moderate to high concentration, shaped by the presence of global leaders with strong manufacturing capacity, technological expertise, and extensive distribution networks. It is characterized by continuous innovation in fibre designs, including bend-insensitive and low-loss solutions, to meet the growing requirements of 5G, hyperscale data centers, and international broadband projects. Competition intensifies around large-scale contracts with telecom operators, governments, and cloud service providers, where established firms leverage economies of scale and R&D strength. Regional manufacturers contribute by offering cost-effective alternatives tailored to local needs, though they face barriers in scaling globally. Strategic partnerships, long-term supply agreements, and investment in sustainable practices define competitive positioning. The Single Mode Optical Fibre market reflects a dynamic structure where product performance, scalability, and reliability remain central to gaining market share. It continues to evolve as industry players adapt to rising demand for high-speed, low-latency, and future-ready communication infrastructure worldwide.
Report Coverage
The research report offers an in-depth analysis based on Core, Deployment, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand steadily with strong adoption in 5G and next-generation telecom networks.
- Demand will rise from hyperscale data centers supporting AI, IoT, and cloud applications.
- Governments will continue to invest in national broadband and smart city projects.
- Fibre-to-the-home deployments will accelerate in both developed and emerging economies.
- Technological innovation will drive new fibre designs with lower loss and higher capacity.
- Submarine cable projects will increase to strengthen global data connectivity.
- Industrial automation will boost demand for reliable high-speed fibre networks.
- Sustainability practices will shape manufacturing and deployment strategies.
- Competition will intensify with regional players offering cost-efficient solutions.
- The market will evolve into a critical enabler of global digital transformation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Single Mode Optical Fibre market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Single Mode Optical Fibre Market projected to grow between 2025 and 2032?
Which Single Mode Optical Fibre market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Single Mode Optical Fibre market?
Who are the leading companies in the Single Mode Optical Fibre Market?
Which region commanded the largest share of the Single Mode Optical Fibre market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Single Mode Optical Fibre Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Single Mode Optical Fibre Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2.45 billion → 2032: USD 7.92 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Single Mode Optical Fibre Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Single Mode Optical Fibre Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Single Mode Optical Fibre Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Single Mode Optical Fibre Market Drivers
- 3.3 Single Mode Optical Fibre Market Restraints & Challenges
- 3.4 Single Mode Optical Fibre Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Single Mode Optical Fibre Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Single Mode Optical Fibre Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Single Mode Optical Fibre category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Single Mode Optical Fibre Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Single Mode Optical Fibre Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Single Mode Optical Fibre market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Single Mode Optical Fibre Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Single Mode Optical Fibre Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Single Mode Optical Fibre Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Single Mode Optical Fibre (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Single Mode Optical Fibre Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Single Mode Optical Fibre Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Single Mode Optical Fibre Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Single Mode Optical Fibre Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Single Mode Optical Fibre Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Single Mode Optical Fibre Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Single Mode Optical Fibre Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Single Mode Optical Fibre Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Single Mode Optical Fibre Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
