
Market Overview
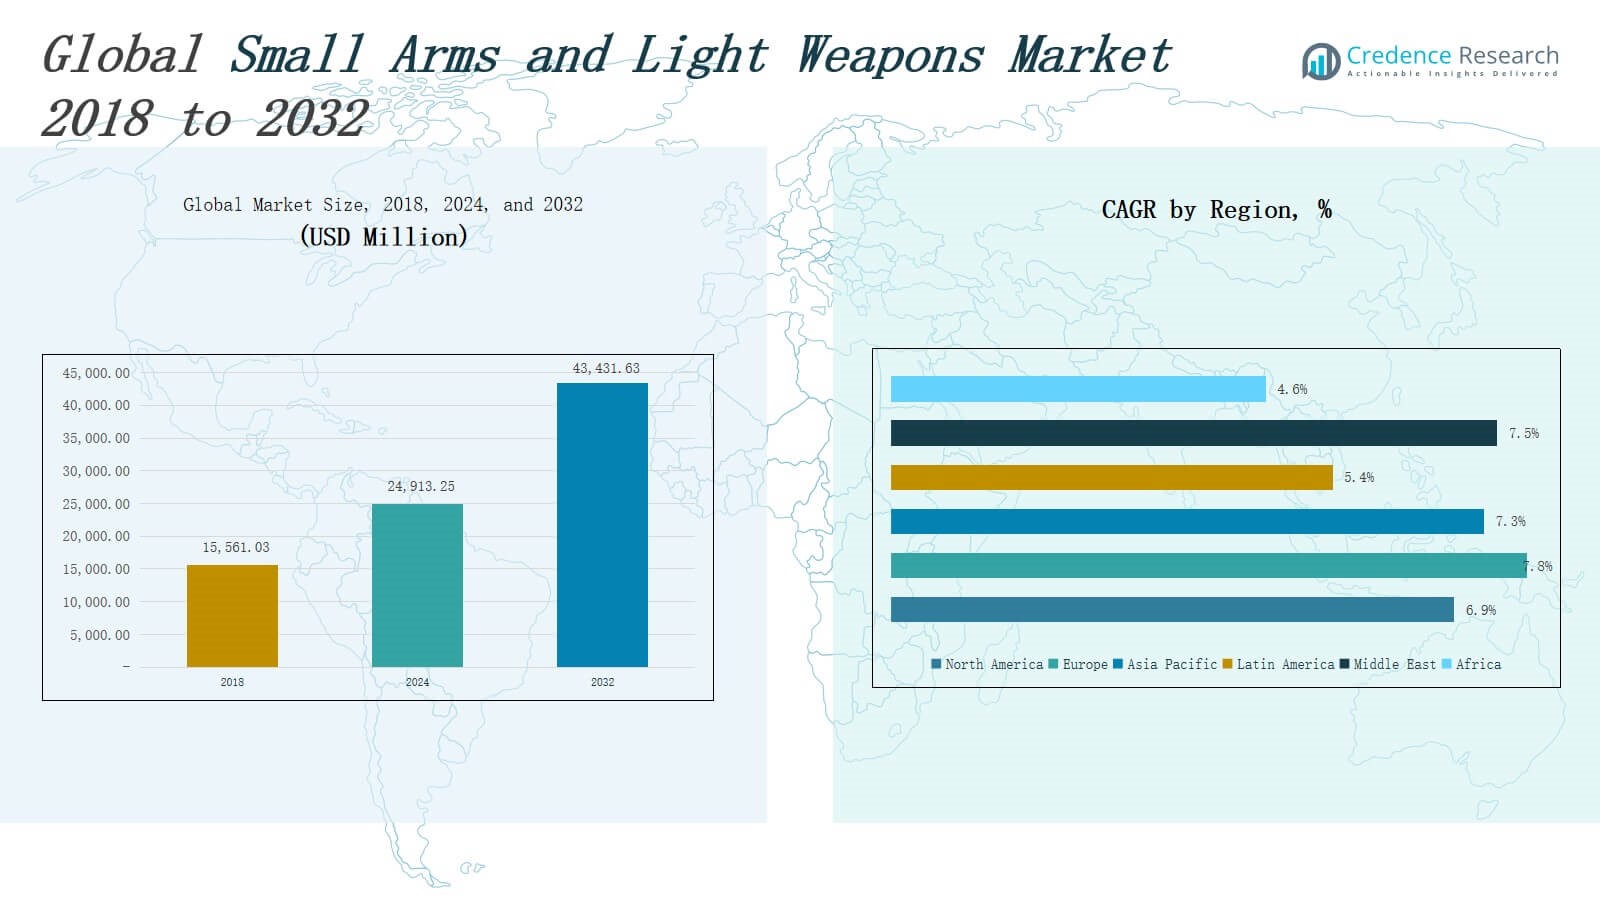
The Small Arms and Light Weapons Market size was valued at USD 15,561.03 million in 2018 to USD 24,913.25 million in 2024 and is anticipated to reach USD 43,431.63 million by 2032, at a CAGR of 7.17% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Small Arms and Light Weapons Market Size 2024 | USD 24,913.25 Million |
| Small Arms and Light Weapons Market, CAGR | 7.17% |
| Small Arms and Light Weapons Market Size 2032 | USD 43,431.63Million |
The Small Arms and Light Weapons (SALW) market is driven by increasing geopolitical tensions, rising defense budgets, and the modernization of military and law enforcement agencies worldwide. Growing demand for personal protection, border security, and counter-terrorism operations fuels procurement across both governmental and civilian sectors. Technological advancements such as modular weapon systems, lightweight materials, and smart optics are enhancing weapon performance and attracting end-users seeking improved accuracy and adaptability. Additionally, the rise in civilian gun ownership for sport shooting and self-defense, particularly in North America and parts of Europe, supports market expansion. Trends indicate a shift toward digitized and customizable weapon platforms, integration of electronic fire control systems, and adoption of 3D printing in component manufacturing. The market is also witnessing increased emphasis on export-oriented production and public-private partnerships in emerging economies. Regulatory developments and efforts to control illicit arms trafficking influence market dynamics, encouraging manufacturers to prioritize compliance and responsible sourcing.
The Small Arms and Light Weapons Market demonstrates strong geographical presence across North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa. North America leads in revenue share, driven by high civilian ownership and defense spending. Europe follows closely with robust military modernization and NATO-led demand. Asia Pacific shows rapid growth due to rising defense budgets in China, India, and South Korea. Latin America focuses on internal security and anti-crime operations, while the Middle East drives demand through military expansion and regional conflicts. Africa remains the smallest market but continues to procure arms for border security and peacekeeping. Key players include General Dynamics Corporation, Heckler & Koch GmBH, Sturm, Ruger & Company, FN Herstal, Colt’s Manufacturing, SIG Sauer, Lockheed Martin, Carl Walther GmbH, and Beretta S.p.A, each competing through innovation, global partnerships, and government contracts.
Market Insights
- The Small Arms and Light Weapons Market was valued at USD 24,913.25 million in 2024 and is projected to reach USD 43,431.63 million by 2032, driven by a strong 7.1% CAGR.
- Geopolitical tensions, counter-terrorism efforts, and rising defense budgets are fueling demand across military, paramilitary, and law enforcement sectors.
- Civilian ownership for self-defense and recreational shooting is rising in North America and Europe, supported by regulatory reforms and e-commerce expansion.
- Technological innovations such as smart optics, modular weapons, and 3D-printed components are transforming weapon performance and production efficiency.
- Strict international regulations and illicit arms trafficking concerns present major compliance challenges, especially for exports into sensitive regions.
- North America leads the market with USD 8,877.66 million in 2024 revenue, followed by Europe and rapidly growing Asia Pacific; Latin America, Middle East, and Africa show emerging demand.
- Key players include General Dynamics, Heckler & Koch, FN Herstal, SIG Sauer, Beretta, Colt’s Manufacturing, and Lockheed Martin, competing through innovation and global defense contracts.
Market Drivers
Rising Geopolitical Conflicts and Border Security Concerns
The Small Arms and Light Weapons Market is expanding due to intensifying regional conflicts, insurgency threats, and cross-border tensions. Governments are strengthening national security by increasing procurement of modern firearms for military and paramilitary forces. It supports rapid deployment and close-combat readiness. Law enforcement agencies seek improved operational capability for counterterrorism and riot control. Demand is particularly high in Asia, the Middle East, and Africa. Ongoing threats drive continuous investment in compact, reliable weapon systems.
- For instance, the United Arab Emirates has boosted domestic production and export of next-generation small arms, with locally manufactured rifles and pistols now being adopted by their armed forces and police, reflecting a documented shift toward self-reliance in hardware amid heightened internal security threats.
Growing Demand from Civilian and Commercial Sectors
The Small Arms and Light Weapons Market is gaining traction from rising civilian interest in firearms for self-defense, sports shooting, and hunting. Countries such as the United States, Canada, and parts of Europe are experiencing steady growth in personal gun ownership. It reflects broader concerns about personal safety and an expanding recreational shooting culture. Commercial shooting ranges and training academies contribute to rising demand. Regulatory shifts in gun ownership laws influence this growth. E-commerce platforms enhance accessibility.
- For instance, in 2023, the National Shooting Sports Foundation (NSSF) reported that 5.4 million Americans purchased their first firearm, with women accounting for approximately 42% of these first-time buyers.
Modernization of Military and Law Enforcement Agencies
The Small Arms and Light Weapons Market benefits from global efforts to replace aging armories with advanced, lightweight, and modular firearms. Governments prioritize investments in enhanced small arms that improve accuracy, durability, and adaptability. It supports mission-specific configurations and tactical upgrades. Increased adoption of red dot sights, suppressors, and electronic fire control systems strengthens combat readiness. Law enforcement units prefer ergonomic and user-friendly weapons. Modern logistics frameworks accelerate supply and inventory management.
Technological Advancements and Manufacturing Innovation
The Small Arms and Light Weapons Market is evolving through innovations in materials, design, and production processes. Industry players adopt polymers, carbon composites, and 3D printing to reduce weight and enhance durability. It enables mass customization and faster time-to-market. Smart weapons with digital sights and integrated tracking systems are gaining traction. Technological upgrades meet end-user expectations for precision and efficiency. Manufacturers partner with defense contractors to expand R&D. These advances drive competitive differentiation.
Market Trends
Shift Toward Lightweight, Modular, and Ergonomic Weapon Designs
The Small Arms and Light Weapons Market is experiencing a significant transition toward lightweight, modular platforms tailored for mission-specific flexibility. Forces prioritize ease of use, mobility, and quick adaptability in diverse combat environments. It supports integrated accessory compatibility, including advanced optics and suppressors. Compact weapon designs are gaining popularity among special forces and urban response units. Ergonomic features reduce fatigue and improve accuracy. Manufacturers focus on user-centric designs to meet operational demands.
- For instance, the SIG Sauer XM7 rifle, adopted by the U.S. Army in 2024, incorporates a free-float handguard, ambidextrous controls, and a quick-detach suppressor, making it lighter and more adaptable to various mission profiles compared to previous models.
Integration of Smart Technologies and Digital Fire Control Systems
The Small Arms and Light Weapons Market reflects a growing trend toward integration of smart technologies for enhanced functionality. Digital fire control systems, electronic aiming modules, and biometric user authentication are increasingly incorporated. It enables better target acquisition, reduced collateral damage, and improved operational control. Wireless connectivity and real-time performance diagnostics are gaining traction in both military and law enforcement applications. These technologies support data-driven training and maintenance. Users demand precision and customization in real-time environments.
- For instance, the U.S. Army’s adoption of the XM157 Fire Control optic on its Next Generation Squad Weapon features integrated laser rangefinding, ballistic calculation, and wireless connectivity to assist targeting and data-driven training in operational environments.
Increasing Investments in Research, Development, and Defense Partnerships
The Small Arms and Light Weapons Market is seeing sustained investment in R&D initiatives, driven by both public and private sector collaboration. Governments fund innovation to develop next-generation systems that offer greater range, reduced recoil, and enhanced lethality. It leads to strategic alliances between defense contractors and weapons manufacturers. These partnerships accelerate prototyping, testing, and product deployment cycles. Global defense exhibitions showcase innovation pipelines. Countries prioritize indigenous weapon development to reduce import dependency.
Rising Focus on Export-Oriented Production and Regulatory Compliance
The Small Arms and Light Weapons Market is trending toward export-led manufacturing strategies, especially in Eastern Europe, Asia, and Latin America. It allows domestic producers to leverage cost advantages and expand their international footprint. Exporters face increasing pressure to align with international arms trade regulations and ethical compliance norms. Transparency in supply chains and traceability of components are becoming standard practices. Regulatory compliance enhances market credibility. Export-friendly policies stimulate growth across emerging production hubs.
Market Challenges Analysis
Stringent Regulatory Frameworks and Export Restrictions
The Small Arms and Light Weapons Market faces significant pressure from evolving international and domestic regulations. Governments and global bodies impose strict controls on manufacturing, sales, and cross-border transfers of weapons. It creates compliance complexities for producers, especially small and medium enterprises. Policies such as the Arms Trade Treaty and end-user certification requirements limit expansion into sensitive regions. Unpredictable embargoes and export bans disrupt supply chains and delay delivery timelines. Compliance costs and legal risks often outweigh potential market gains in high-risk zones.
Proliferation Risks and Illicit Trade Concerns
The Small Arms and Light Weapons Market must navigate persistent concerns around illegal trafficking and misuse of weapons. It faces scrutiny from advocacy groups and policymakers concerned about rising gun violence and conflict escalation. Poor control in post-conflict zones contributes to black-market circulation. Manufacturers encounter reputational and operational risks when weapons end up in unauthorized hands. International pressure to tighten transparency and tracking of sales impacts volume and profitability. These challenges hinder market stability and long-term planning.
Market Opportunities
Rising Defense Modernization Programs Across Emerging Economies
The Small Arms and Light Weapons Market presents strong growth potential through expanding defense budgets in Asia-Pacific, Latin America, and the Middle East. Governments are prioritizing military modernization to counter regional threats and strengthen homeland security. It opens new procurement contracts for advanced, lightweight, and modular weapons. Nations such as India, Brazil, and Saudi Arabia are investing in tactical upgrades and soldier lethality programs. Domestic manufacturing and joint ventures support localization and technology transfer. These trends offer long-term opportunities for established and new entrants.
Growing Demand for Smart Weapons and Tactical Enhancements
The Small Arms and Light Weapons Market can capitalize on increasing interest in smart firearms equipped with digital sights, biometric locks, and wireless diagnostics. It reflects a shift toward data-driven defense strategies and real-time battlefield intelligence. Law enforcement agencies seek connected solutions to improve accuracy, accountability, and performance tracking. Civilian consumers also show interest in personal defense weapons with advanced safety features. Manufacturers integrating electronics and AI-enabled components can access high-margin segments. Demand for innovation continues to reshape procurement strategies globally.
Market Segmentation Analysis:
By Product
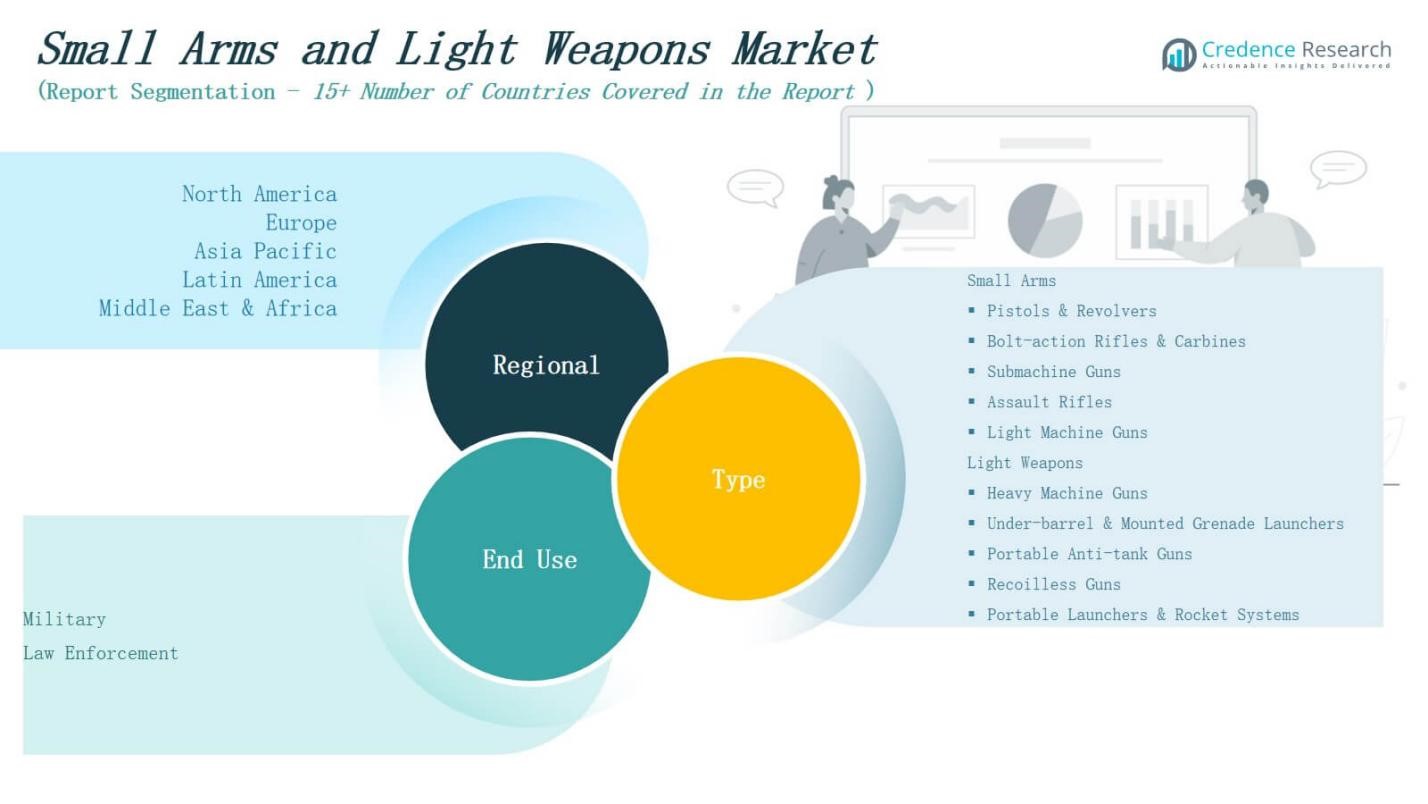
The Small Arms and Light Weapons Market is segmented into small arms and light weapons, each serving distinct operational needs. Small arms include pistols and revolvers, bolt-action rifles and carbines, submachine guns, assault rifles, and light machine guns. These are widely used in close-quarter combat, law enforcement, and civilian defense. Among them, assault rifles and pistols command strong demand due to their versatility, compactness, and ease of use. Light weapons comprise heavy machine guns, under-barrel and mounted grenade launchers, portable anti-tank guns, recoilless guns, and portable launchers and rocket systems. It supports military operations requiring high-impact firepower and mobility. Light weapons find extensive use in infantry, special operations, and anti-armor missions.
- For instance, the Glock 17 9mm pistol, widely adopted by police agencies globally, is known for its reliability and has been a standard sidearm for the UK Metropolitan Police since 2013.
By End Use
The Small Arms and Light Weapons Market is divided into military and law enforcement segments. Military forces dominate market share with large-scale procurement programs aimed at force modernization and threat preparedness. It supports the adoption of advanced automatic rifles, light machine guns, and portable launch systems. Law enforcement agencies focus on semi-automatic pistols, submachine guns, and non-lethal variants to ensure public safety and tactical flexibility. Rising internal security challenges and terrorism threats continue to drive demand in both segments. Strategic upgrades and international defense cooperation influence purchasing decisions.
- For instance, the U.S. Army awarded a contract to SIG Sauer for the Next Generation Squad Weapon (NGSW), including the XM7 rifle and XM250 automatic rifle, to replace the M4 and M249.
Segments:
Based on Product
Small Arms
- Pistols & Revolvers
- Bolt-action Rifles & Carbines
- Submachine Guns
- Assault Rifles
- Light Machine Guns
Light Weapons
- Heavy Machine Guns
- Under-barrel & Mounted Grenade Launchers
- Portable Anti-tank Guns
- Recoilless Guns
- Portable Launchers & Rocket Systems
Based on End Use
- Military
- Law Enforcement
Based on Region
North America
- U.S.
- Canada
- Mexico
Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
Latin America
- Brazil
- Argentina
- Rest of Latin America
Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis
North America
The North America Small Arms and Light Weapons Market size was valued at USD 5,619.09 million in 2018 to USD 8,877.66 million in 2024 and is anticipated to reach USD 15,201.07 million by 2032, at a CAGR of 6.9% during the forecast period. North America holds the largest market share, driven by high civilian firearm ownership, robust defense spending, and advanced manufacturing capabilities. The United States leads in both domestic demand and global exports of small arms. It benefits from strong institutional frameworks, mature distribution networks, and ongoing defense modernization programs. Law enforcement agencies across the U.S. and Canada continue to upgrade their armory. The presence of major players like Sturm, Ruger & Company and Colt’s Manufacturing supports innovation and production scale.
Europe
The Europe Small Arms and Light Weapons Market size was valued at USD 4,582.72 million in 2018 to USD 7,619.90 million in 2024 and is anticipated to reach USD 13,941.55 million by 2032, at a CAGR of 7.8% during the forecast period. Europe commands a substantial share of the global market, supported by regional security initiatives and NATO-aligned procurement. Countries like Germany, France, and the UK invest heavily in soldier modernization and counterterrorism efforts. It maintains a strong defense industrial base with manufacturers such as Heckler & Koch and FN Herstal. Stricter regulatory frameworks influence civilian ownership but allow controlled market growth. Cross-border cooperation and joint ventures enhance technology exchange.
Asia Pacific
The Asia Pacific Small Arms and Light Weapons Market size was valued at USD 3,222.69 million in 2018 to USD 5,195.84 million in 2024 and is anticipated to reach USD 9,142.36 million by 2032, at a CAGR of 7.3% during the forecast period. Asia Pacific is witnessing rapid market growth, led by increased defense budgets and internal security challenges. Countries such as China, India, and South Korea focus on troop preparedness and border defense. It supports procurement of rifles, carbines, and portable launchers. Indigenous production and technology transfer initiatives are expanding. The market benefits from a large defense personnel base and rising paramilitary operations.
Latin America
The Latin America Small Arms and Light Weapons Market size was valued at USD 1,314.91 million in 2018 to USD 1,929.00 million in 2024 and is anticipated to reach USD 2,953.35 million by 2032, at a CAGR of 5.4% during the forecast period. Latin America represents a moderate share of the global market, driven by internal security issues and anti-narcotics operations. Brazil and Mexico lead demand, with military and law enforcement agencies procuring weapons for urban crime control and counterinsurgency. It faces procurement challenges due to budget limitations and import dependencies. Domestic manufacturing in Brazil is expanding to reduce reliance on foreign suppliers. Regional instability continues to drive steady demand.
Middle East
The Middle East Small Arms and Light Weapons Market size was valued at USD 602.21 million in 2018 to USD 980.16 million in 2024 and is anticipated to reach USD 1,745.95 million by 2032, at a CAGR of 7.5% during the forecast period. The Middle East demonstrates strong growth due to regional conflicts, military expansion, and border security concerns. Countries such as Saudi Arabia, Israel, and the UAE invest in advanced weapon systems and tactical upgrades. It benefits from defense partnerships with Western manufacturers and increased local assembly initiatives. Law enforcement and counterterrorism units continue to modernize. The market is also influenced by government-to-government arms agreements.
Africa
The Africa Small Arms and Light Weapons Market size was valued at USD 219.41 million in 2018 to USD 310.70 million in 2024 and is anticipated to reach USD 447.35 million by 2032, at a CAGR of 4.6% during the forecast period. Africa holds the smallest market share but remains strategically significant due to ongoing insurgencies and border conflicts. Nations such as South Africa and Egypt lead procurement initiatives and regional distribution. It relies heavily on imports and donor-funded defense programs. Demand centers on rifles, carbines, and portable machine guns for military and peacekeeping missions. Regional instability and arms trafficking challenge consistent growth. Efforts to develop local production remain limited.
Key Player Analysis
- General Dynamics Corporation
- Heckler & Koch GmBH
- Sturm, Ruger & Company
- FN Herstal, S.A.
- Colt’s Manufacturing Company LLC
- SIG Sauer GmbH & Co.
- Lockheed Martin Corporation
- Carl Walther GmbH
- Beretta S.p.A
- Other Key Players
Competitive Analysis
The Small Arms and Light Weapons Market features a competitive landscape dominated by global defense manufacturers and specialized firearm producers. Key players such as General Dynamics Corporation, Beretta S.p.A, FN Herstal, and SIG Sauer focus on military contracts, innovation, and strategic partnerships. It remains highly fragmented, with companies competing on quality, reliability, and compliance with export regulations. Firms invest in R&D to enhance modularity, weight reduction, and smart features. Civilian demand supports product diversification, particularly in pistols and rifles. Regional manufacturers in Asia and Latin America aim to strengthen domestic capabilities through joint ventures and technology transfers. Market leaders benefit from established supply chains and long-standing government relationships. Pricing, performance, and product adaptability remain central to competitive positioning. Compliance with evolving international arms trade policies continues to influence market reach and expansion strategies.
Recent Developments
- In June 2025, TEMBO Defence signed a memorandum of understanding to set up a small-arms ammunition manufacturing facility in Amravati, Maharashtra, in partnership with a European firearms company that will purchase the full production output.
- In June 2025, SIG Sauer introduced the P211-GTO, a new double-stack 1911-style handgun, during its SIG NEXT 2025 event held from June 17–19.
- In May 2025, Rheinmetall formed a strategic partnership with Reliance Defence to produce medium- and heavy-caliber artillery ammunition at a new facility in Maharashtra.
- In June 2025, IWI’s Indian partner BSS Material Ltd completed successful trials of the AI-powered Negev NG-7 light machine gun with the Indian Army, demonstrating automated targeting capabilities at high altitudes.
Market Concentration & Characteristics
The Small Arms and Light Weapons Market exhibits moderate to high market concentration, with several global defense firms dominating supply to military, law enforcement, and civilian sectors. It features a mix of legacy manufacturers and regional players focused on specialized weapons and tactical systems. Companies compete on performance, durability, customization, and regulatory compliance. The market is characterized by long-term government contracts, export licensing challenges, and a steady demand cycle influenced by geopolitical instability and public security concerns. It supports continuous product innovation, including modular weapon platforms, lightweight materials, and digital enhancements. Entry barriers remain high due to strict legal frameworks, high capital investment, and technology requirements. Despite regulatory pressure, demand from civilian users and security forces ensures consistent revenue opportunities. The market favors players with global distribution, reliable supply chains, and strong R&D capabilities. It also shows a growing shift toward domestic production in emerging economies to reduce dependency on foreign imports.
Report Coverage
The research report offers an in-depth analysis based on Product, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Defense modernization programs will drive steady demand for modular and lightweight weapon systems.
- Civilian firearm ownership will continue to rise in regions with relaxed regulatory frameworks.
- Governments will invest more in indigenous weapon production to strengthen self-reliance.
- Smart weapon technologies with digital fire control systems will gain wider adoption.
- Export-oriented strategies will expand market reach for manufacturers in developing countries.
- Public-private partnerships will support innovation and manufacturing scale-up.
- Rising border conflicts and insurgencies will sustain procurement by military and paramilitary forces.
- Regulatory scrutiny will increase, requiring stricter compliance from arms producers.
- Law enforcement agencies will adopt more ergonomic and versatile weapons for urban operations.
- Use of advanced materials and additive manufacturing will reduce costs and improve weapon efficiency.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Geopolitical Conflicts and Border Security Concerns
Escalating regional conflicts, insurgency threats, and cross-border tensions are prompting governments to increase procurement of modern small arms and light weapons for military and paramilitary forces, driving market growth especially in Asia, the Middle East, and Africa.
Growing Civilian and Commercial Demand
Increasing civilian interest in firearms for self-defense, sport shooting, and hunting - particularly in North America and parts of Europe - along with regulatory reforms and e-commerce expansion, is fueling demand in the civilian and commercial segments.
Modernization of Military and Law Enforcement Agencies
Global efforts to replace aging armories with advanced, lightweight, and modular firearms are leading to large-scale procurement programs, with a focus on improved accuracy, adaptability, and mission-specific configurations for both military and law enforcement.
Technological Advancements and Manufacturing Innovation
Adoption of smart optics, modular weapon systems, lightweight materials, and 3D printing is enhancing weapon performance, enabling mass customization, and attracting end-users seeking improved efficiency and adaptability.
Export-Oriented Production and Public-Private Partnerships
Emerging economies are increasingly focusing on export-led manufacturing and forming public-private partnerships, which expands international market reach and supports domestic industry growth while navigating complex regulatory environments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Small Arms and Light Weapons Market?
What factors are driving the growth of the Small Arms and Light Weapons Market?
What are the key segments within the Small Arms and Light Weapons Market?
What are some challenges faced by the Small Arms and Light Weapons Market?
Who are the major players in the Small Arms and Light Weapons Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Military
- 1.2.2 Law Enforcement
- 1.2.3 Civilian
- 1.3 By Product
- 1.3.1 Pistols & Revolvers
- 1.3.2 Bolt-action Rifles & Carbines
- 1.3.3 Submachine Guns
- 1.3.4 Assault Rifles
- 1.3.5 Light Machine Guns
- 1.3.6 Heavy Machine Guns
- 1.3.7 Grenade Launchers
- 1.3.8 Portable Anti-tank & Recoilless Guns
- 1.3.9 Portable Launchers & Rocket Systems
- 1.4 By Technology
- 1.4.1 Conventional Weapons
- 1.4.2 Modular/Customizable Weapons
- 1.4.3 Smart Weapons & Digital Fire Control
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 24,913.25 million → 2032: USD 43,431.63 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Small Arms And Light Weapons Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Small Arms And Light Weapons Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Small Arms And Light Weapons Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Small Arms And Light Weapons Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Small Arms And Light Weapons Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Small Arms And Light Weapons Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Small Arms And Light Weapons Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Small Arms And Light Weapons Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 24,913.25 million → 2032: USD 43,431.63 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Small Arms And Light Weapons Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Military
- 12.3.7.2 Law Enforcement
- 12.3.7.3 Civilian
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Pistols & Revolvers
- 12.4.7.2 Bolt-action Rifles & Carbines
- 12.4.7.3 Submachine Guns
- 12.4.7.4 Assault Rifles
- 12.4.7.5 Light Machine Guns
- 12.4.7.6 Heavy Machine Guns
- 12.4.7.7 Grenade Launchers
- 12.4.7.8 Portable Anti-tank & Recoilless Guns
- 12.4.7.9 Portable Launchers & Rocket Systems
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Conventional Weapons
- 12.5.7.2 Modular/Customizable Weapons
- 12.5.7.3 Smart Weapons & Digital Fire Control
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Small Arms And Light Weapons End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Small Arms And Light Weapons Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Small Arms And Light Weapons Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Small Arms And Light Weapons Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 General Dynamics Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Heckler & Koch GmbH
- 18.4 Sturm, Ruger & Company
- 18.5 FN Herstal S.A.
- 18.6 Colt’s Manufacturing Company LLC
- 18.7 SIG Sauer GmbH & Co.
- 18.8 Lockheed Martin Corporation
- 18.9 Carl Walther GmbH
- 18.10 Beretta S.p.A
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

