
Market Overview:
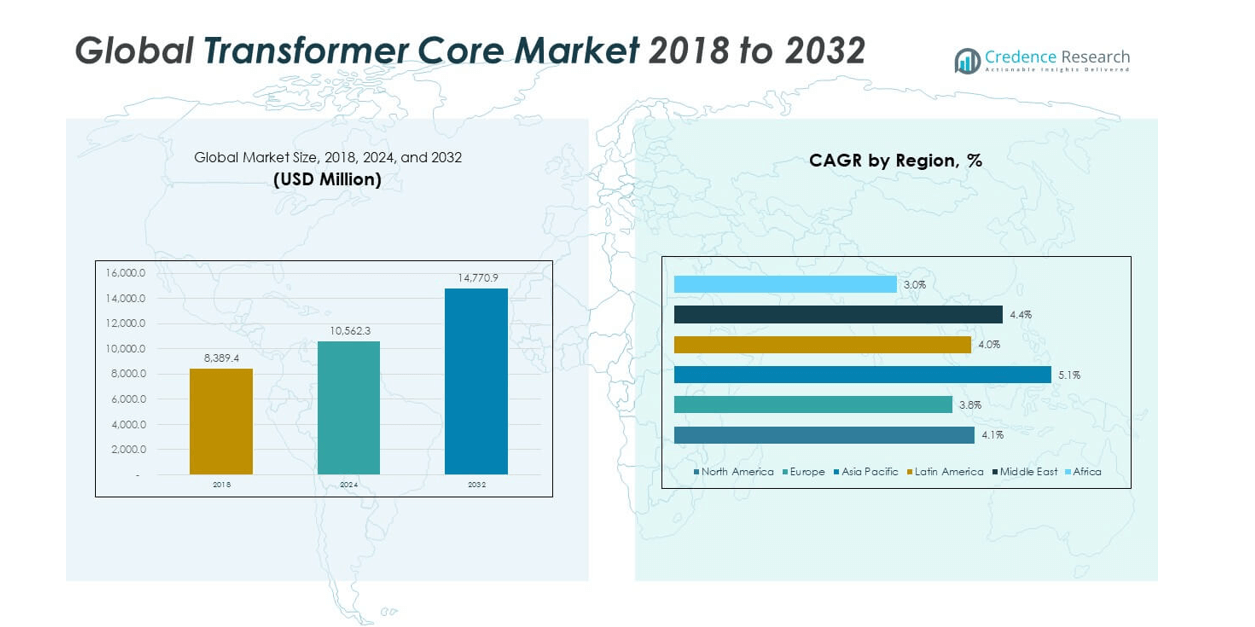
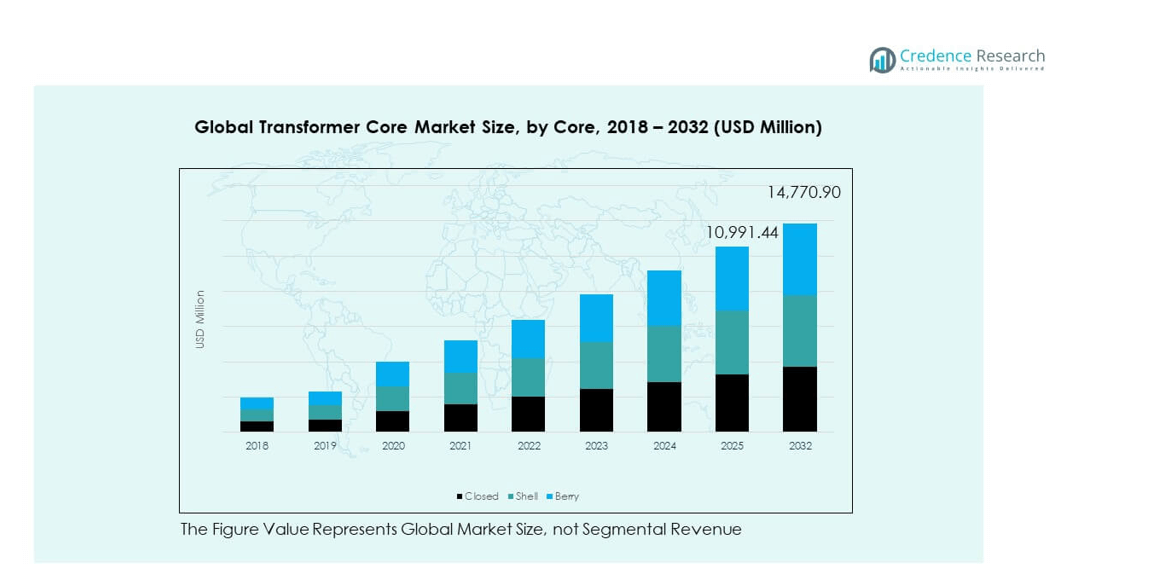
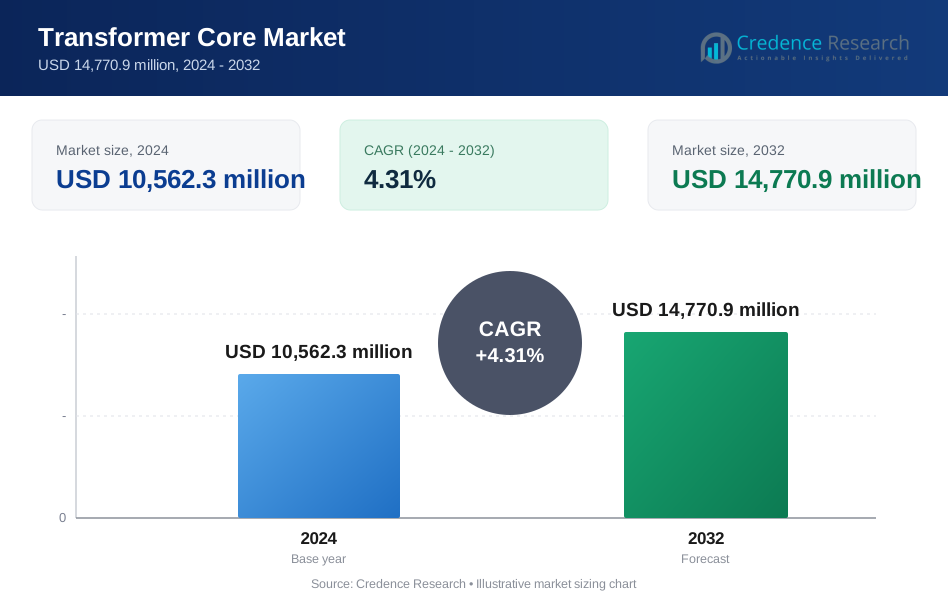
The Global Transformer Core Market size was valued at USD 8,389.4 million in 2018 to USD 10,562.3 million in 2024 and is anticipated to reach USD 14,770.9 million by 2032, at a CAGR of 4.31% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Transformer Core Market Size 2024 | USD 10,562.3 million |
| Transformer Core Market, CAGR | 4.31% |
| Transformer Core Market Size 2032 | USD 14,770.9 million |
The market growth is driven by rising electricity demand, rapid industrialization, and expanding power infrastructure worldwide. The shift toward renewable energy projects, such as wind and solar power, increases the need for efficient transformers with high-performance cores. Growing investments in smart grid technology and transmission networks are supporting adoption. Furthermore, the demand for energy-efficient solutions and regulatory pressure to reduce power losses push manufacturers to innovate with advanced materials and core designs, fueling consistent growth opportunities across industries.
Regionally, Asia-Pacific dominates the market due to strong power demand, industrial expansion, and government-backed infrastructure projects in China and India. North America follows, supported by upgrades in aging grid systems and renewable integration initiatives. Europe shows steady growth, driven by its focus on energy efficiency and sustainability targets. Meanwhile, Latin America and the Middle East & Africa are emerging markets, benefiting from urbanization, electrification, and rising investments in power generation and distribution infrastructure.
Market Insights:
- The Global Transformer Core Market was valued at USD 8,389.4 million in 2018, reached USD 10,562.3 million in 2024, and is projected to reach USD 14,770.9 million by 2032, growing at a CAGR of 4.31%.
- Asia Pacific held the largest share at 32% in 2024, followed by Europe at 26% and North America at 23%, driven by industrial expansion, renewable integration, and grid modernization.
- Asia Pacific is the fastest-growing region, supported by rapid electrification, government-backed infrastructure projects, and increasing manufacturing demand.
- In 2024, closed cores accounted for about 27% of the market, reflecting steady demand in power transformers due to efficiency benefits.
- Shell and berry cores together represented roughly 73% of the market in 2024, led by shell cores widely used in distribution and specialty applications.
Market Drivers:
Growing Electricity Consumption and Rising Infrastructure Development:
The Global Transformer Core Market benefits from the worldwide surge in electricity consumption driven by industrialization and urbanization. Expanding urban populations create pressure on utilities to increase capacity and reliability of power supply. Infrastructure development in emerging economies requires advanced transformers with efficient core designs to support growing demand. Renewable energy integration further stimulates transformer deployment across wind and solar power plants. Rising electrification in transportation and heating systems intensifies power consumption. Governments are increasing investments in energy infrastructure to meet rising demands. Manufacturers are responding with innovative materials that reduce power loss. The steady expansion of power grids ensures sustained growth in this market.
- For instance, Metglas Inc. expanded its South Carolina plant in 2023, doubling production capacity for HB1M Amorphous Steel used in efficient distribution transformers, directly supporting increased grid capacity. The steady expansion of power grids ensures sustained growth in this market.
Shift Toward Renewable Energy Projects and Smart Grid Integration:
The growing emphasis on renewable energy accelerates the adoption of transformer cores. Solar and wind projects need efficient transmission systems to handle variable energy loads. The Global Transformer Core Market aligns with government policies supporting clean energy expansion. Smart grid development improves grid stability and increases demand for energy-efficient transformer cores. Countries are modernizing networks to reduce carbon emissions and enhance power reliability. This transition compels utilities to install high-performance transformers across large-scale renewable installations. Transformer core innovations reduce inefficiencies in energy transfer during peak production. Global initiatives for sustainability strengthen the adoption of advanced core technologies.
- For instance, Arteche acquired RTR Energía in June 2025 to expand its smart grid and power electronics portfolio, reinforcing its role in supporting renewable energy infrastructure with advanced measurement and transformer solutions. Global initiatives for sustainability strengthen the adoption of advanced core technologies.
Technological Advancements and Demand for Energy-Efficient Solutions:
Energy efficiency standards drive innovation in transformer core technology. Utilities demand materials that limit energy wastage during transmission. The Global Transformer Core Market responds with advanced amorphous metal and nanocrystalline cores. These materials improve efficiency while reducing heat generation and operational costs. Governments impose strict efficiency guidelines to reduce overall power consumption. Growing awareness of sustainability among corporations and industries boosts adoption of efficient transformers. Continuous research fosters the development of lightweight cores with improved magnetic properties. These innovations enhance reliability while meeting environmental and operational targets.
Expansion of Transmission and Distribution Networks Worldwide:
Rising investments in transmission and distribution networks fuel core demand. Expanding cross-border electricity trade creates need for advanced transformer infrastructure. The Global Transformer Core Market grows in response to government-backed electrification projects in rural areas. Utilities invest heavily to modernize aging infrastructure in developed countries. Growing population density requires high-capacity transmission systems to ensure uninterrupted supply. Expanding industrial activity in energy-intensive sectors amplifies the requirement for efficient transformers. Companies are aligning production capacity with these developments to meet regional needs. These trends ensure long-term growth for transformer core manufacturers worldwide.
Market Trends:
Adoption of Advanced Core Materials Including Amorphous and Nanocrystalline Alloys:
The Global Transformer Core Market is experiencing growth through adoption of amorphous metal and nanocrystalline materials. These materials enhance efficiency by reducing no-load losses. Utilities prefer them to meet energy-saving mandates and reduce carbon footprints. Manufacturers are investing in large-scale production to make these materials cost-effective. The push for sustainable power transmission strengthens demand for innovative core solutions. Adoption is expanding across developed and emerging economies with varied energy policies. Research collaborations drive innovation in lightweight materials for improved performance. The trend ensures wider market acceptance of advanced transformer core technologies.
- For example, Ferroxcube International Holding B.V. announced a strategic partnership focused on magnetic components innovation to enhance transformer core performance in 2023. The trend ensures wider market acceptance of advanced transformer core technologies.
Growing Role of Digitalization and Smart Monitoring Solutions:
Digital monitoring technologies reshape the transformer landscape. The Global Transformer Core Market aligns with digital trends by integrating smart sensors into transformers. Utilities benefit from real-time performance tracking and predictive maintenance systems. This digital integration improves grid reliability and lowers maintenance costs. Growing focus on Industry 4.0 increases adoption of intelligent transformers. Utilities across regions embrace digital tools to manage complex grids more efficiently. Advanced analytics enhance detection of faults in transformer cores. The trend reinforces the role of smart grids in global power systems.
- For instance, Arteche and Mondragon joined forces in June 2025 to promote power electronics innovations that strengthen smart grid monitoring capabilities. The trend reinforces the role of smart grids in global power systems.
Rising Focus on Compact and Lightweight Transformer Designs:
Global demand is shifting toward compact transformers with smaller cores. The Global Transformer Core Market reflects this change with innovations in design and materials. Lightweight designs reduce installation space and overall equipment costs. Growing urban density accelerates adoption of compact solutions in power distribution. Transportation and renewable projects also benefit from smaller transformers. Advances in material science support the trend of downsized yet efficient cores. Companies are investing in R&D to meet this demand for optimized designs. This evolution enables flexible deployment in constrained urban and industrial environments.
Integration of Eco-Friendly Manufacturing Practices Across Core Production:
Manufacturers adopt sustainable practices in transformer core production. The Global Transformer Core Market reflects environmental goals through reduced emissions and recyclable materials. Companies invest in green technologies to meet regulatory expectations. The adoption of eco-friendly laminations reduces ecological impact. Growing consumer preference for sustainable energy solutions influences corporate strategies. Governments are encouraging low-emission production across the electrical industry. These practices enhance corporate image and strengthen competitiveness. Market adoption of green manufacturing techniques continues to grow steadily.
Market Challenges Analysis:
Volatile Raw Material Prices and Dependence on Import Supply Chains:
The Global Transformer Core Market faces constraints from fluctuating raw material prices. Steel and advanced alloys used in core production are vulnerable to supply chain disruptions. Rising global trade tensions and limited suppliers add uncertainty. Manufacturers experience pressure on margins when raw material costs escalate. Import dependence in several regions creates risks of shortages and delays. These issues affect production schedules and delivery commitments. Companies attempt to mitigate risks with long-term supply agreements. However, raw material instability remains a consistent challenge to profitability and market balance.
High Capital Costs and Complex Regulatory Requirements in Energy Infrastructure:
Investments in transformer infrastructure demand significant capital expenditure. The Global Transformer Core Market is affected by high upfront costs of modernized systems. Utilities in developing economies face financing challenges for large projects. Compliance with efficiency regulations adds design and testing complexities. Prolonged approval processes delay deployment and increase costs. Small and medium manufacturers struggle to match regulatory requirements and innovation standards. Rising operational expenses further pressure industry participants. These barriers hinder rapid adoption of advanced transformer core technologies across markets.
Market Opportunities:
Growing Electrification of Transport and Expansion of Renewable Energy Projects:
The Global Transformer Core Market finds opportunities in the electrification of transportation systems. Electric vehicles require strong charging infrastructure supported by efficient transformers. Renewable projects such as wind and solar farms expand rapidly worldwide. Demand for transformer cores rises to support these installations. Governments fund projects promoting green energy and sustainable mobility. Manufacturers are investing in tailored solutions for these fast-growing sectors. This expansion strengthens revenue streams and ensures long-term opportunities. The alignment with green policies enhances competitiveness in the global market.
Modernization of Grids and Rising Rural Electrification Programs:
Governments invest in modernizing grids and extending rural electrification. The Global Transformer Core Market benefits from these policies as utilities demand efficient transformers. Developing regions focus on improving access to electricity for economic growth. Developed economies replace aging infrastructure with smart, efficient systems. Expansion of cross-border energy trade supports demand for advanced cores. Companies provide innovative solutions to meet these diverse regional needs. Rural and urban electrification initiatives generate steady opportunities for manufacturers. These programs drive inclusive growth and long-term adoption of core technologies.
Market Segmentation Analysis:
By Core Segment
The Global Transformer Core Market is divided into closed, shell, and berry cores. Closed cores dominate due to their efficiency in minimizing energy losses, making them suitable for power transformers. Shell cores find adoption in distribution and specialty transformers because of their strong short-circuit withstand capability. Berry cores, while less common, serve niche applications where lightweight and compact design is essential. Each core type addresses specific grid and industrial needs, supporting diverse operational environments. The mix ensures balance between performance, cost efficiency, and technical suitability across industries.
- For instance, Nicore Magnetic Cores in 2025 emphasized advancements in silicon steel cores used predominantly in closed core transformers for power applications. The mix ensures balance between performance, cost efficiency, and technical suitability across industries.
By Type Segment
The market includes distribution transformers, power transformers, and instrument transformers. Distribution transformers lead demand, driven by residential and commercial grid expansion. Power transformers represent significant revenue contribution due to large-scale transmission projects and cross-border energy trade. Instrument transformers, though smaller in volume, play a vital role in ensuring safety and accuracy in energy measurement. It benefits from growing investments in smart grid infrastructure and automated monitoring systems. These segments align with rising power consumption patterns worldwide.
By Application Segment
Applications span residential and commercial, utility, and industrial sectors. Utilities hold the largest share, supported by grid modernization, renewable integration, and rising electricity demand. Residential and commercial segments expand steadily with urbanization and increasing energy access in emerging economies. Industrial applications register strong growth due to expanding manufacturing, mining, and heavy industries requiring high-capacity transformers. It continues to gain momentum as electrification accelerates across sectors. The demand pattern highlights the versatile role transformer cores play in energy distribution and industrial efficiency.
Segmentation:
By Core Segment
- Closed
- Shell
- Berry
By Type Segment
- Distribution Transformer
- Power Transformer
- Instrument Transformer
By Application Segment
- Residential & Commercial
- Utility
- Industrial
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America
The North America Transformer Core Market size was valued at USD 1,985.77 million in 2018 to USD 2,465.25 million in 2024 and is anticipated to reach USD 3,382.54 million by 2032, at a CAGR of 4.1% during the forecast period. North America holds a strong share in the Global Transformer Core Market, contributing around 23% in 2024. The region benefits from large-scale investments in grid modernization and renewable integration. The U.S. leads demand due to upgrades of aging infrastructure and expansion of smart grids. Canada and Mexico support growth with rising industrial activity and cross-border electricity trade. The market is driven by policies promoting efficiency and low-loss transmission systems. Industrial sectors with high energy intensity further stimulate adoption. Growing electrification of transport also boosts transformer core installations. It continues to strengthen its position with advanced manufacturing and innovation in core materials.
Europe
The Europe Transformer Core Market size was valued at USD 2,255.90 million in 2018 to USD 2,754.66 million in 2024 and is anticipated to reach USD 3,692.72 million by 2032, at a CAGR of 3.8% during the forecast period. Europe represents about 26% of the Global Transformer Core Market in 2024, supported by its strong regulatory focus on energy efficiency. Germany, France, and the UK lead adoption with sustainable energy projects and smart grid investments. Industrial expansion and renewable integration create steady demand across the region. Southern and Eastern Europe contribute with rising urbanization and growing electricity needs. Companies are investing in eco-friendly production techniques to align with EU sustainability policies. The market benefits from well-established distribution infrastructure. Adoption of digital monitoring in transformers is also increasing. It maintains momentum as energy transition policies reshape the electricity landscape.
Asia Pacific
The Asia Pacific Transformer Core Market size was valued at USD 2,536.11 million in 2018 to USD 3,348.72 million in 2024 and is anticipated to reach USD 4,973.36 million by 2032, at a CAGR of 5.1% during the forecast period. Asia Pacific dominates the Global Transformer Core Market with about 32% share in 2024. China leads due to massive grid expansion and strong renewable deployment. India, Japan, and South Korea add significant growth through urbanization and industrialization. Rapid electrification in Southeast Asia further enhances regional demand. Government-backed rural electrification programs are creating steady opportunities. The market benefits from high consumption levels driven by manufacturing and residential sectors. Cost advantages and domestic supply chains strengthen Asia Pacific’s leadership. It continues to expand with innovation and adoption of high-efficiency cores.
Latin America
The Latin America Transformer Core Market size was valued at USD 746.65 million in 2018 to USD 924.21 million in 2024 and is anticipated to reach USD 1,262.91 million by 2032, at a CAGR of 4.0% during the forecast period. Latin America accounts for about 9% of the Global Transformer Core Market in 2024. Brazil leads the region with investments in power generation and distribution. Argentina and other emerging economies contribute through urbanization and industrialization. The market benefits from infrastructure upgrades and government policies to expand electricity access. Renewable projects in solar and wind drive additional adoption. Utilities focus on reducing losses and improving reliability across grids. Rising energy demand in urban centers increases installation of advanced transformers. It gains further traction as governments prioritize sustainable and reliable electricity supply.
Middle East
The Middle East Transformer Core Market size was valued at USD 568.80 million in 2018 to USD 721.56 million in 2024 and is anticipated to reach USD 1,019.19 million by 2032, at a CAGR of 4.4% during the forecast period. The Middle East contributes around 7% of the Global Transformer Core Market in 2024. Growth is driven by expanding energy infrastructure in GCC countries. Investments in renewable power, particularly solar projects, strengthen demand. Oil and gas industries add to transformer requirements for energy-intensive operations. Israel and Turkey also contribute to the regional market with industrial expansion. Governments emphasize modernizing electricity infrastructure to meet growing urban populations. Cross-border power trade supports deployment of high-capacity transformers. It continues to benefit from both diversification initiatives and traditional energy demand.
Africa
The Africa Transformer Core Market size was valued at USD 296.15 million in 2018 to USD 347.95 million in 2024 and is anticipated to reach USD 440.17 million by 2032, at a CAGR of 3.0% during the forecast period. Africa represents about 3% of the Global Transformer Core Market in 2024. South Africa leads with industrial demand and grid upgrades, while Egypt follows with growing electricity projects. Other countries in Sub-Saharan Africa focus on electrification and renewable deployment. Rural electrification programs create consistent demand for distribution transformers. Limited infrastructure and investment capacity slow overall growth compared to other regions. The market gains momentum from foreign direct investments in energy projects. Industrialization and urbanization steadily increase transformer installations. It shows long-term potential as electricity access improves across the continent.
Key Player Analysis:
- Arteche
- Corefficient S de RL de CV
- Eilor Magnetic Cores
- Ferroxcube International Holding B.V.
- Fuji Electric Co. Ltd.
- KRYFS Power Components Ltd
- Metglas Inc
- Nicore Magnetic Cores
- Hyosung Corporation
- Mitsubishi Electric
- Other Key Players
Competitive Analysis:
The Global Transformer Core Market is moderately consolidated, with established multinational corporations and specialized regional players shaping competition. Leading companies focus on innovation in core materials, energy-efficient technologies, and expansion into renewable energy projects. Strategic partnerships, mergers, and acquisitions enhance market reach and strengthen supply chains. Regional players contribute by serving localized demand and offering cost-effective solutions. It reflects a balance between global giants with advanced R&D capabilities and smaller firms with niche expertise. Continuous investments in smart grid infrastructure and sustainability initiatives keep competition intense and innovation-driven.
Recent Developments:
- In August 2025, Zetwerk acquired a controlling stake in KRYFS Power Components Ltd., a leading transformer solutions manufacturer in India. This partnership aims to innovate and scale energy infrastructure manufacturing, especially in the high-voltage transformer segment.
- In June 2025, Arteche acquired RTR Energía, a Spanish company specializing in measurement and monitoring solutions for electrical networks, further consolidating its position as a leader in grid reliability and energy management solutions.
- In May 2025, Fuji Electric Co., Ltd. launched its new large-capacity semiconductor modules, including 1,700V and 2,300V SiC models, designed to improve efficiency in renewable energy systems and industrial power supplies.
Report Coverage:
The research report offers an in-depth analysis based on core, type, and application segments. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising demand for energy-efficient transformers will drive steady adoption.
- Renewable energy projects will expand the need for advanced transformer cores.
- Smart grid deployment will increase investments in high-performance transformers.
- Material innovations such as amorphous alloys will gain wider acceptance.
- Grid modernization in developed economies will stimulate replacement demand.
- Emerging markets will benefit from electrification and industrialization initiatives.
- Environmental regulations will accelerate adoption of low-loss core technologies.
- Partnerships and acquisitions will shape competitive dynamics.
- Digital monitoring integration will improve transformer performance and reliability.
- Regional supply chain development will enhance resilience and reduce dependency.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Electricity Demand and Infrastructure Expansion
Global industrialization and urbanization are driving up electricity consumption, necessitating the expansion and modernization of power infrastructure. This directly increases the need for efficient transformer cores to support reliable and scalable grid operations.
Renewable Energy Integration and Smart Grid Development
The shift toward renewable energy sources such as wind and solar requires advanced transformer cores capable of handling variable loads and supporting grid stability. Investments in smart grid technology further boost demand for high-performance, energy-efficient cores.
Technological Advancements in Core Materials
Innovations in amorphous metal and nanocrystalline alloys are enabling transformer cores with lower energy losses and improved efficiency. These advancements help utilities and manufacturers meet stricter energy efficiency standards and reduce operational costs.
Regulatory Pressure for Energy Efficiency and Loss Reduction
Governments and regulatory bodies are imposing stringent efficiency standards on power transmission and distribution, compelling manufacturers to develop transformer cores that minimize power losses and environmental impact.
Expansion of Transmission and Distribution Networks
Ongoing investments in expanding and upgrading transmission and distribution networks, especially in emerging markets and rural areas, are fueling steady demand for transformer cores tailored to diverse grid and industrial requirements.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Transformer Core Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Transformer Core Market projected to grow between 2025 and 2032?
Which Global Transformer Core Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Transformer Core Market?
Who are the leading companies in the Global Transformer Core Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Core Segment
- 1.2.1 Closed
- 1.2.2 Shell
- 1.2.3 Berry
- 1.3 By Type Segment
- 1.3.1 Distribution Transformer
- 1.3.2 Power Transformer
- 1.3.3 Instrument Transformer
- 1.4 By Application Segment
- 1.4.1 Residential & Commercial
- 1.4.2 Utility
- 1.4.3 Industrial
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 10,562.3 million → 2032: USD 14,770.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Transformer Core Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Transformer Core Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Transformer Core Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Transformer Core Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Transformer Core Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Transformer Core Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Transformer Core Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Transformer Core Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 10,562.3 million → 2032: USD 14,770.9 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Transformer Core Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Core Segment - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Closed
- 12.3.7.2 Shell
- 12.3.7.3 Berry
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Type Segment - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Distribution Transformer
- 12.4.7.2 Power Transformer
- 12.4.7.3 Instrument Transformer
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application Segment - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Residential & Commercial
- 12.5.7.2 Utility
- 12.5.7.3 Industrial
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Transformer Core End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Transformer Core Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Transformer Core Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Transformer Core Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Arteche
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Corefficient S de RL de CV
- 18.4 Eilor Magnetic Cores
- 18.5 Ferroxcube International Holding B.V.
- 18.6 Fuji Electric Co. Ltd.
- 18.7 KRYFS Power Components Ltd
- 18.8 Metglas Inc
- 18.9 Nicore Magnetic Cores
- 18.10 Hyosung Corporation
- 18.11 Mitsubishi Electric
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

