
Wafer Processing Equipment Market Overview:
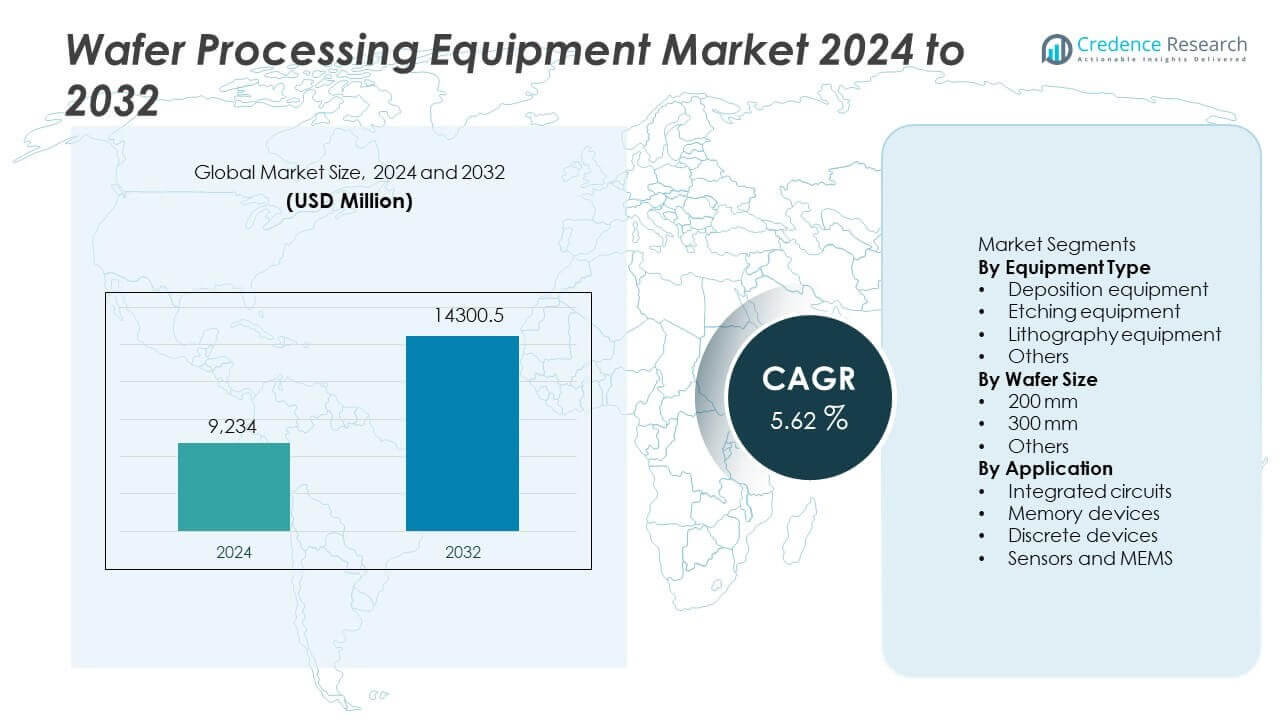
The Wafer Processing Equipment market was valued at USD 9,234 million in 2024 and is expected to reach USD 14,300.5 million by 2032, growing at a CAGR of 5.62% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Wafer Processing Equipment Market Size 2024 | USD 9,234 million |
| Wafer Processing Equipment Market, CAGR | 5.62% |
| Wafer Processing Equipment Market Size 2032 | USD 14,300.5 million |
Wafer Processing Equipment Market Insights
- Market growth is driven by rising demand for advanced semiconductor nodes, fab capacity expansion, and higher chip usage in automotive, AI, and industrial electronics.
- Key market trends include strong adoption of 300 mm wafer processing, which holds a segment share of 62.5%, and increasing demand for advanced lithography equipment with a 34.8% share.
- Competitive analysis shows a highly consolidated market, with leading players focusing on R&D investment, process precision, and long-term partnerships with major semiconductor fabs.
- Regionally, Asia Pacific leads with a 44.2% market share, followed by North America at 24.8% and Europe at 18.6%, reflecting concentration of semiconductor manufacturing activity.
Wafer Processing Equipment Market Segmentation Analysis:
By Equipment Type
By equipment type, lithography equipment dominates the Wafer Processing Equipment market with a market share of 34.8%. This dominance reflects its critical role in advanced node manufacturing and pattern precision. Chipmakers depend on lithography systems to achieve smaller geometries and higher yields. Rising demand for advanced logic and memory devices strengthens adoption. Continuous investment in process upgrades supports sustained equipment demand. High capital intensity and technological barriers limit supplier entry, reinforcing dominance. Deposition and etching equipment follow, supported by multi-layer device architectures. However, lithography remains central due to its direct impact on device performance and scaling.
- For instance, ASML deployed EUV systems capable of printing features below 13 nanometers, with source power exceeding 250 watts, enabling high-volume logic production.
By Wafer Size
By wafer size, 300 mm wafers lead the market with a market share of 62.5%. This leadership is driven by higher output efficiency and lower cost per chip. Large semiconductor fabs favor 300 mm wafers to maximize production scale. Advanced logic and memory manufacturing increasingly relies on this size standard. Equipment suppliers align product development with 300 mm fab requirements. Strong investment in new fabrication facilities sustains demand. The 200 mm segment remains relevant for mature nodes and specialty devices. However, volume growth concentrates around 300 mm wafer processing platforms.
- For instance, Applied Materials supplies 300 mm deposition platforms processing over 1,500 wafers per day, supporting advanced logic and DRAM lines.
By Application
By application, integrated circuits hold the largest share at 46.9%. Strong demand comes from consumer electronics, data centers, and automotive electronics. Continuous chip complexity growth drives equipment upgrades across fabs. Integrated circuit production requires multiple processing steps, increasing equipment utilization. Foundries invest heavily to meet capacity and technology needs. Memory devices follow, supported by data storage demand. Sensors and MEMS show steady growth but lower volumes. Discrete devices serve power and industrial uses. Integrated circuits remain dominant due to high-volume manufacturing and broad end-market demand.
Key Growth Drivers
Rising Demand for Advanced Semiconductor Nodes
Advanced semiconductor nodes strongly drive demand for Wafer Processing Equipment. Chipmakers continue to shrink feature sizes to improve performance and power efficiency. Advanced logic and memory devices require highly precise lithography, etching, and deposition tools. Increasing adoption of artificial intelligence, high-performance computing, and automotive electronics supports this demand. Foundries invest heavily in equipment upgrades to maintain technology leadership. Process complexity increases the number of processing steps per wafer. Higher tool utilization strengthens recurring demand. This driver supports continuous capital expenditure across leading semiconductor manufacturing regions.
- For instance, Tokyo Electron delivers plasma etching systems that achieve precise critical dimension control at advanced process nodes. These tools support the fabrication of gate-all-around structures with high etch uniformity maintained across large-diameter wafers.
Expansion of Semiconductor Fabrication Capacity
Global expansion of semiconductor fabrication facilities supports strong equipment demand. Governments and private players invest in new fabs to secure supply chains. Large-scale projects in Asia Pacific, North America, and Europe increase tool installations. Equipment suppliers benefit from both greenfield and brownfield investments. Capacity expansion addresses rising chip demand across electronics, automotive, and industrial sectors. Advanced and mature node fabs require different tool sets. Long construction timelines ensure multi-year equipment orders. This driver supports stable order backlogs and long-term revenue visibility.
- For instance, Lam Research supplies advanced deposition and etch platforms designed to maximize wafer throughput and output density across high-volume semiconductor manufacturing environments.
Growth of Automotive and Industrial Electronics
Automotive and industrial electronics continue to expand semiconductor demand. Electric vehicles, advanced driver assistance systems, and power electronics increase chip usage. These applications require reliable and high-quality wafers. Wafer Processing Equipment supports stringent performance and safety standards. Industrial automation also increases semiconductor integration. Demand spans logic, power, and sensor devices. Equipment suppliers develop tools for high-reliability production. Longer product lifecycles stabilize demand. This driver broadens application diversity and reduces reliance on consumer electronics cycles.
Key Trends & Opportunities
Adoption of Advanced Packaging and Integration Technologies
Advanced packaging technologies create new opportunities for Wafer Processing Equipment suppliers. Chiplet architectures and 3D integration increase process steps. Equipment demand rises for precise deposition and inspection. Manufacturers seek higher yield and performance improvements. Integration complexity increases equipment value per wafer. Suppliers expand offerings beyond traditional front-end tools. Collaboration with chip designers strengthens equipment innovation. This trend supports premium tool demand and higher average selling prices across advanced manufacturing nodes.
- For instance, KLA Corporation provides inspection systems detecting defects below 10 nanometers at wafer level.
Growing Investment in Domestic Semiconductor Manufacturing
Countries prioritize domestic semiconductor production to improve supply security. Policy support encourages local fab construction. Equipment demand rises in emerging manufacturing regions. Regional diversification reduces supply chain risk. Local fabs require complete tool ecosystems. Equipment suppliers expand regional service networks. Long-term contracts support market entry. This opportunity strengthens global equipment footprint. It also supports sustained demand across multiple geographic markets.
- For instance, Hitachi High-Tech supplies critical dimension scanning electron microscopes achieving resolution under 1 nanometer.
Key Challenges
High Capital Costs and Long Investment Cycles
High capital costs pose a major challenge for Wafer Processing Equipment adoption. Advanced tools require significant upfront investment. Fab construction timelines are lengthy and complex. Budget constraints affect equipment purchase timing. Smaller manufacturers face entry barriers. Market demand cycles influence capital spending decisions. Equipment suppliers manage order volatility. Long qualification processes delay revenue realization. This challenge increases dependence on large customers and stable financing conditions.
Technological Complexity and Rapid Innovation Pressure
Rapid technology evolution creates ongoing challenges for equipment manufacturers. Continuous innovation is required to meet shrinking node requirements. Research and development costs remain high. Tool obsolescence risks increase with faster technology shifts. Integration with evolving processes requires constant updates. Customer expectations for uptime and yield continue to rise. Skilled workforce shortages add pressure. This challenge demands sustained investment in innovation, talent, and customer support capabilities.
Regional Analysis
North America
North America holds a market share of 24.8% in the Wafer Processing Equipment market, supported by strong investments in advanced semiconductor manufacturing. The United States leads regional demand due to large-scale fab expansions and government-backed semiconductor programs. Advanced logic and memory production drives high adoption of lithography, etching, and metrology tools. The region also benefits from a strong presence of leading foundries and integrated device manufacturers. R&D-intensive manufacturing supports demand for next-generation equipment. Stable demand from automotive and defense electronics further strengthens equipment utilization across new and upgraded fabrication facilities.
Europe
Europe accounts for a market share of 18.6%, driven by rising investments in specialty semiconductors and automotive electronics. Countries such as Germany, France, and the Netherlands support demand through automotive, industrial, and power semiconductor production. The region emphasizes manufacturing precision and quality compliance, supporting steady equipment upgrades. Expansion of regional fabs under strategic semiconductor initiatives contributes to demand growth. Equipment adoption remains strong in mature-node and specialty wafer processing. Collaboration between equipment suppliers and research institutes further supports technology development and stable long-term demand.
Asia Pacific
Asia Pacific dominates the Wafer Processing Equipment market with a market share of 44.2%. The region benefits from the concentration of large semiconductor fabs in China, Taiwan, South Korea, and Japan. High-volume production of logic, memory, and foundry chips drives continuous equipment investments. Rapid expansion of 300 mm wafer fabs strengthens demand for advanced tools. Government support and cost-efficient manufacturing enhance regional competitiveness. Strong consumer electronics and data center demand further supports capacity expansion. Asia Pacific remains the primary growth engine due to scale-driven manufacturing activity.
Latin America
Latin America holds a market share of 6.1%, supported by growing electronics manufacturing and gradual semiconductor ecosystem development. Countries such as Brazil and Mexico contribute demand through assembly, testing, and limited wafer processing activities. Equipment demand focuses mainly on mature-node applications and specialty devices. Industrial and automotive electronics support incremental growth. Regional demand remains smaller compared to major hubs, but improving infrastructure and foreign investment support gradual expansion. Equipment suppliers target the region through service support and partnerships to capture emerging opportunities.
Middle East & Africa
The Middle East & Africa region accounts for a market share of 6.3%, reflecting early-stage semiconductor manufacturing development. Demand is driven by strategic investments in technology diversification and electronics manufacturing. Israel plays a key role due to its advanced semiconductor R&D and fabrication capabilities. Equipment demand focuses on advanced process development and specialized applications. Other countries contribute limited volumes due to developing manufacturing bases. Long-term national technology initiatives support gradual growth. The region shows steady potential as governments invest in high-tech industrial expansion.
Wafer Processing Equipment Market Segmentations:
By Equipment Type
- Deposition equipment
- Etching equipment
- Lithography equipment
- Others
By Wafer Size
- 200 mm
- 300 mm
- Others
By Application
- Integrated circuits
- Memory devices
- Discrete devices
- Sensors and MEMS
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis of the Wafer Processing Equipment market highlights the presence of key players including ASML Holding N.V., Applied Materials, Inc., Lam Research Corporation, Tokyo Electron Limited, and KLA Corporation. The market is highly consolidated, with competition centered on technological leadership, process precision, and long-term customer relationships. Leading suppliers benefit from strong intellectual property portfolios and deep integration with major semiconductor fabs. Continuous investment in research and development supports advanced node compatibility and yield optimization. High switching costs strengthen customer retention. Regional service networks and lifecycle support enhance competitive positioning. Smaller players compete through niche solutions and mature-node tools. Overall competition focuses on innovation pace, equipment reliability, and alignment with evolving semiconductor manufacturing roadmaps.
Key Player Analysis
- ASML Holding N.V.
- Applied Materials, Inc.
- Lam Research Corporation
- Tokyo Electron Limited
- KLA Corporation
- ASM International N.V.
- SCREEN Holdings Co., Ltd.
- Hitachi High-Tech Corporation
- Nikon Corporation
- Canon Inc.
Recent Developments
- In November 2024, SCREEN Semiconductor Solutions launched the SS-3200 200 mm wafer cleaning system.
- In July 2024, Applied Materials introduced new chip-wiring process innovations for higher performance-per-watt.
- In May 2024, KLA highlighted new broadband plasma optical inspection systems, including 3935 and 3920 EP.
Report Coverage
The research report offers an in-depth analysis based on Equipment Type, Wafer Size, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Wafer Processing Equipment market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Wafer Processing Equipment market projected to grow between 2024 and 2032?
Which Wafer Processing Equipment market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Wafer Processing Equipment market?
Who are the leading companies in the Wafer Processing Equipment market?
Which region commanded the largest share of the Wafer Processing Equipment market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 9,234 million → 2032: USD 14,300.5 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Wafer Processing Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Wafer Processing Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Wafer Processing Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Wafer Processing Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Wafer Processing Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Wafer Processing Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Wafer Processing Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Wafer Processing Equipment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 9,234 million → 2032: USD 14,300.5 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Wafer Processing Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Wafer Processing Equipment Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Wafer Processing Equipment Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Wafer Processing Equipment Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

