
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Adaptive Stroller Market Size 2024 | USD 510.6 million |
| Adaptive Stroller Market, CAGR | 7.9% |
| Adaptive Stroller Market Size 2032 | USD 938 million |
Market Overview:
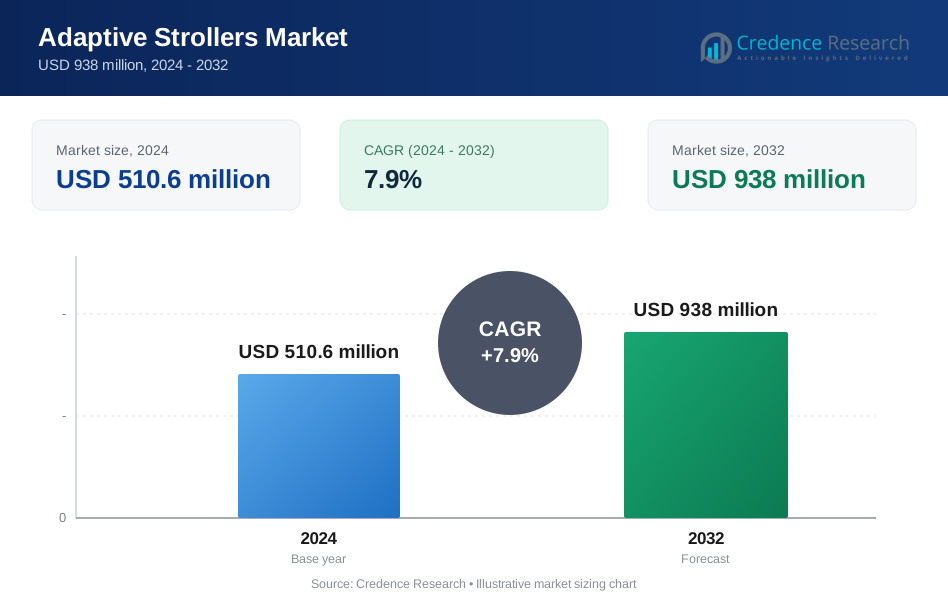
Adaptive Stroller Market size was valued at USD 510.6 million in 2024 and is anticipated to reach USD 938 million by 2032, at a CAGR of 7.9% during the forecast period (2024-2032).
Key drivers of the adaptive stroller market include the growing prevalence of disabilities among children, coupled with increasing healthcare expenditure and supportive government initiatives. The rising incidence of cerebral palsy, muscular dystrophy, and other mobility-related disorders further amplifies the demand for specialized strollers. Technological advancements such as lightweight materials, adjustable seating, and ergonomic designs enhance product functionality, driving consumer adoption. Additionally, the integration of smart features such as GPS tracking and sensor-based safety mechanisms is gaining traction among manufacturers. Furthermore, the rising focus on parental convenience and the availability of strollers with enhanced durability and foldability propel market growth. Additionally, increasing collaborations between manufacturers and healthcare institutions to develop specialized mobility solutions further stimulate market demand.
Regionally, North America holds a significant market share due to well-established healthcare infrastructure, high consumer awareness, and supportive reimbursement policies. The presence of key market players and continuous product innovation further strengthen the region’s dominance. Europe follows closely, driven by stringent safety regulations and rising adoption of assistive devices. Government-funded mobility aid programs and favorable insurance coverage policies contribute to market expansion in the region. The Asia-Pacific market is poised for substantial growth due to increasing disposable income, expanding healthcare accessibility, and growing awareness about adaptive mobility solutions. The rapid urbanization and improving retail distribution channels in countries like China and India are further driving product accessibility. Countries such as China and India present lucrative opportunities due to their large pediatric population and improving healthcare frameworks. Meanwhile, Latin America and the Middle East & Africa show steady market growth, supported by increasing healthcare investments and government-led accessibility programs. The rising involvement of non-profit organizations and international aid programs is also playing a crucial role in expanding accessibility to adaptive mobility solutions in these regions.
Market Insights:
- The adaptive stroller market was valued at USD 510.6 million in 2024 and is projected to reach USD 938 million by 2032, growing at a CAGR of 7.9% during the forecast period.
- Rising prevalence of mobility disorders such as cerebral palsy and muscular dystrophy is increasing the demand for specialized strollers, providing essential support for children with disabilities.
- Technological advancements in adaptive strollers, including lightweight materials, ergonomic designs, GPS tracking, and sensor-based safety features, are enhancing product functionality and consumer adoption.
- Government support and healthcare reimbursement policies in North America and Europe are improving affordability, while financial assistance programs and insurance coverage continue to drive adoption rates.
- Expanding e-commerce and retail distribution channels are increasing accessibility, allowing caregivers to explore a wider range of adaptive strollers both online and in specialty mobility stores.
- Asia-Pacific is experiencing the fastest market growth, driven by increasing disposable income, improving healthcare infrastructure, and growing awareness about assistive mobility solutions.
- Strategic collaborations between manufacturers and healthcare institutions are strengthening market penetration, fostering innovation, and improving accessibility to adaptive mobility solutions globally.
Market Drivers:
Rising Prevalence of Mobility Disorders Among Children:
The increasing incidence of mobility-related disorders, such as cerebral palsy, muscular dystrophy, and developmental disabilities, is a primary driver of the adaptive stroller market. With a growing number of children requiring specialized mobility solutions, the demand for adaptive strollers has surged. These strollers provide essential support, enabling children with physical disabilities to experience greater mobility and independence. For instance, according to the Centers for Disease Control and Prevention (CDC), approximately 1 out of 6 children in the United States experienced a developmental disorder or delay in 2022. Additionally, as medical advancements enhance early diagnosis rates, parents and caregivers are increasingly seeking high-quality mobility aids to improve their child’s quality of life.
Technological Advancements and Product Innovation:
Continuous technological advancements in adaptive strollers contribute significantly to market growth. Manufacturers are focusing on developing lightweight, ergonomic, and highly adjustable strollers to cater to the diverse needs of children with mobility challenges. Features such as reclining seats, customizable harness systems, shock-absorbing wheels, and foldable designs enhance both comfort and ease of use. For instance, Doona launched its all-in-one stroller and car seat, Doona X, in 2024, combining convenience and safety by offering seamless transitions between stroller and car seat. Additionally, the integration of smart technologies, including GPS tracking, automated braking systems, and sensory-responsive seating, is gaining traction among consumers. These innovations not only improve safety but also offer enhanced convenience for parents and caregivers.
Government Support and Healthcare Reimbursement Policies:
Supportive government initiatives and favorable healthcare reimbursement policies play a crucial role in driving the adaptive stroller market. Several countries offer subsidies and financial assistance programs to facilitate access to mobility aids for children with disabilities. For instance, ForwardHealth covers adaptive strollers for members who require seating, trunk, and/or head positional supports that are unavailable on a commercial stroller. In regions such as North America and Europe, insurance coverage and social welfare programs further ease the financial burden on families. Additionally, government regulations promoting inclusivity and accessibility in public spaces encourage the adoption of adaptive strollers, fostering market expansion.
Growing Awareness and Expanding Distribution Channels:
Rising awareness about assistive mobility solutions is another significant driver of market growth. Educational campaigns, healthcare advocacy programs, and the increasing role of non-profit organizations have helped highlight the importance of adaptive strollers for children with mobility impairments. For instance, Variety's My Stroller® Program is designed for children and youth who have a documented disability, providing adaptive strollers to eligible families. Furthermore, the expansion of retail and e-commerce distribution channels has improved product accessibility, allowing caregivers to explore a wide range of options. The growing presence of adaptive stroller brands in both online and offline retail spaces has enhanced market penetration, fueling further demand.
Market Trends:
Integration of Smart Features:
The adaptive stroller market is witnessing a rise in the integration of smart technologies aimed at enhancing safety, convenience, and user experience. Features such as GPS tracking, automated braking systems, and sensor-based adjustments are gaining traction among manufacturers and consumers. For instance, the Glüxkind Ella smart stroller incorporates adaptive push and brake assistance, allowing for hands-free operation and enhanced safety on various terrains. These advancements provide parents and caregivers with real-time monitoring and enhanced control over stroller functionality, ensuring greater security and ease of use. Additionally, Bluetooth-enabled connectivity allows for seamless integration with mobile applications, offering customized support settings and accessibility options.
Lightweight and Ergonomic Designs:
Manufacturers are increasingly focusing on lightweight yet durable materials to improve the overall design of adaptive strollers. Ergonomically designed strollers with enhanced adjustability, reclining seats, and shock-absorbing mechanisms provide greater comfort for children with mobility challenges. For instance, the Adaptive Star Axiom Endeavour 2 Special Needs Stroller features a multi-adjustable reclining seat back and independently height/angle adjustable foot buckets, offering superior comfort and support. The use of aluminum and high-strength composite materials ensures that strollers remain sturdy while remaining easy to maneuver. Foldable and travel-friendly designs are also gaining popularity, addressing the need for greater portability and storage convenience for caregivers.
Expanding Customization and Personalization Options:
The demand for customized adaptive strollers is growing as consumers seek solutions tailored to specific mobility needs. Adjustable seating positions, customizable harness systems, and modular components enable strollers to accommodate various disabilities effectively. For instance, the R for Rabbit Street Smart Auto Fold Stroller offers a personalized name plate option, allowing parents to add a unique touch to their child's mobility aid. Manufacturers are also offering a range of aesthetic customization options, such as different color choices and accessory add-ons, to enhance consumer appeal. This trend aligns with the broader shift toward personalized assistive mobility solutions.
Growth in Online Sales and Retail Expansion:
The expansion of e-commerce platforms and dedicated online stores has significantly improved accessibility to adaptive strollers. Consumers now have a wider selection of products, detailed product specifications, and customer reviews, aiding informed purchasing decisions. For instance, eSpecial Needs, an online retailer specializing in adaptive equipment, offers a comprehensive range of special needs strollers and pushchairs, making it easier for families to find suitable mobility solutions. Traditional retail channels are also expanding their product offerings, with healthcare equipment stores and specialty mobility retailers increasing their inventory of adaptive strollers. The rise in direct-to-consumer sales strategies is further strengthening market reach, contributing to overall industry growth.
Market Challenges Analysis:
High Cost and Limited Insurance Coverage:
One of the primary challenges in the adaptive stroller market is the high cost of specialized mobility solutions. Advanced adaptive strollers, equipped with ergonomic features, lightweight materials, and smart technologies, often come with a premium price tag, making them less accessible for many families. The manufacturing costs of these strollers are high due to the use of medical-grade materials and advanced engineering. While some regions provide healthcare reimbursements and financial assistance programs, coverage is often limited or varies significantly based on location and insurance policies. Many families, particularly in developing economies, struggle to afford these essential mobility aids, leading to a gap in accessibility. Additionally, the lack of government subsidies in several countries further exacerbates affordability concerns. The lack of standardized pricing and reimbursement structures further complicates affordability, hindering market expansion. As a result, the market faces constraints in reaching a wider consumer base, limiting its overall growth potential.
Limited Product Availability and Awareness:
Despite growing demand, adaptive strollers remain less widely available compared to conventional mobility aids. Limited distribution channels, particularly in emerging markets, restrict access to a diverse range of adaptive stroller options. Many regions still lack specialized retail outlets or dedicated online platforms that offer these mobility solutions. Many parents and caregivers are unaware of specialized strollers due to insufficient awareness campaigns and inadequate promotion by healthcare providers. A lack of training among healthcare professionals about assistive mobility solutions further reduces referrals and recommendations. Additionally, the lack of standardization in product specifications and regulatory guidelines across regions affects market penetration. Varying safety and quality standards in different countries create inconsistencies in product availability and consumer trust. Manufacturers face logistical challenges in expanding their reach while maintaining affordability and quality. Addressing these issues requires stronger collaboration between manufacturers, healthcare institutions, and policymakers to improve accessibility and ensure broader adoption of adaptive mobility solutions.
Market Opportunities:
The adaptive stroller market presents significant opportunities driven by increasing demand for specialized mobility solutions and advancements in product innovation. The rising awareness about assistive devices for children with mobility impairments is encouraging manufacturers to expand their product offerings with enhanced features. The growing integration of smart technologies, such as automated braking, GPS tracking, and sensor-based adjustments, offers manufacturers a competitive edge and improves consumer adoption. Additionally, the rising trend of customization, including adjustable seating, modular components, and aesthetic personalization, presents an opportunity for companies to cater to diverse consumer needs. Expanding research and development efforts to introduce cost-effective and lightweight adaptive strollers can further drive market growth, especially in price-sensitive regions.
Emerging markets in Asia-Pacific, Latin America, and the Middle East & Africa provide lucrative opportunities for expansion due to improving healthcare infrastructure and increasing government support for disability assistance programs. As healthcare accessibility improves, the demand for adaptive strollers is expected to rise in these regions, creating new revenue streams for manufacturers. The growth of e-commerce and online retail platforms enhances market reach by providing consumers with a wider selection of products and improved accessibility. Partnerships between manufacturers, healthcare institutions, and non-profit organizations can also help in expanding distribution networks and increasing awareness. Furthermore, government initiatives promoting inclusivity and mobility assistance create favorable conditions for market growth, allowing companies to tap into public procurement contracts and healthcare reimbursement programs. These factors collectively create a strong potential for expansion in the adaptive stroller market.
Market Segmentation Analysis:
By Type
The adaptive stroller market is segmented based on type into lightweight strollers, all-terrain strollers, and customizable strollers. Lightweight strollers are gaining popularity due to their ease of maneuverability and portability, making them suitable for daily use. All-terrain strollers are designed for enhanced stability and durability, allowing mobility on rough surfaces such as parks, sidewalks, and uneven terrains. These strollers are preferred by families seeking greater outdoor accessibility. Customizable strollers, offering adjustable seating, modular components, and personalized support features, are witnessing increased demand as they cater to specific mobility needs. Manufacturers are focusing on integrating ergonomic designs and smart features across all types to enhance usability and comfort.
By Application
Based on application, the market is categorized into hospitals and rehabilitation centers, home care, and specialized institutions. Hospitals and rehabilitation centers are key consumers of adaptive strollers, as they provide mobility support for children undergoing therapy and post-surgical recovery. The home care segment holds a significant share due to the growing preference for personalized mobility solutions that enhance independence. Specialized institutions, including schools and daycare centers for children with disabilities, are also driving market demand. The increasing emphasis on accessibility and inclusion in educational and childcare facilities is further contributing to the adoption of adaptive strollers across various applications.
Segmentations:
By Type
- Lightweight Strollers
- All-Terrain Strollers
- Customizable Strollers
By Application
- Hospitals and Rehabilitation Centers
- Home Care
- Specialized Institutions
By Region
- North America
- The US
- Canada
- Mexico
- Europe
- Germany
- France
- The UKUK.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a market share of 38%, making it the leading region in the adaptive stroller market. The strong presence of key manufacturers, advanced healthcare infrastructure, and supportive reimbursement policies contribute to market growth. The United States and Canada have well-established accessibility regulations that encourage the adoption of mobility solutions for children with disabilities. Government-funded programs and insurance coverage for assistive devices ease the financial burden on families, driving higher adoption rates. Technological advancements, including smart safety features and lightweight materials, further enhance product appeal. The increasing awareness of adaptive mobility solutions and the growing demand for customizable strollers continue to fuel market expansion across North America. The rising prevalence of mobility impairments among children has led to higher investments in research and development for advanced mobility solutions. Additionally, collaborations between healthcare institutions and manufacturers are strengthening product innovations and increasing accessibility.
Europe
Europe accounts for a market share of 29%, driven by stringent safety regulations and widespread adoption of assistive mobility devices. Countries such as Germany, the United Kingdom, and France are at the forefront due to their strong healthcare infrastructure and government-backed financial support for mobility aids. The presence of specialized mobility retailers and a well-developed e-commerce sector enhances product accessibility. The growing focus on inclusive mobility solutions in public spaces, educational institutions, and healthcare facilities further supports market expansion. Manufacturers in the region are investing in product innovations, including ergonomic designs and eco-friendly materials, to align with sustainability trends and consumer preferences. The European Union's initiatives to improve accessibility for individuals with disabilities are driving greater adoption of adaptive strollers. Additionally, increasing consumer preference for lightweight and foldable designs is influencing product development strategies in the region.
Asia-Pacific
Asia-Pacific holds a market share of 24%, experiencing the fastest growth in the adaptive stroller market. The rising pediatric population, increasing healthcare expenditure, and improving awareness of assistive mobility solutions drive market demand. Countries such as China, India, and Japan present significant growth opportunities due to expanding healthcare accessibility and government-led initiatives for disability support. The growing middle-class population and increasing disposable income levels contribute to higher adoption rates of adaptive strollers. The expansion of online retail platforms and improving distribution networks enhance product availability across urban and rural areas. Manufacturers are focusing on cost-effective production methods to cater to price-sensitive markets, further boosting market growth in Asia-Pacific. The rising participation of non-profit organizations in disability support programs is increasing awareness and accessibility of adaptive strollers. Furthermore, strategic partnerships between global brands and regional distributors are strengthening market penetration in developing countries.
Key Player Analysis:
- Invacare Corporation
- Sunrise Medical LLC
- Ottobock SE & Co. KGaA
- Medline Industries, LP
- Convaid (Etac Group)
- Drive DeVilbiss Healthcare
- Eurovema Mobility AB
- R82 A/S (Etac Group)
- Hoggi GmbH
- Meyra GmbH
- Thomashilfen
- Adaptive Star
- Assistive Technology, Inc.
- Deming Designs Inc.
- Ormesa
- Performance Health
Competitive Analysis:
The adaptive stroller market is highly competitive, with key players focusing on product innovation, strategic partnerships, and market expansion. Established manufacturers such as Invacare Corporation, Sunrise Medical LLC, and Ottobock SE & Co. KGaA dominate the market through advanced product offerings and strong distribution networks. Companies are investing in research and development to introduce lightweight, ergonomic, and customizable strollers that cater to specific mobility needs. For instance, Thomashilfen has developed adaptive strollers with electronic height modification, enabling caregivers to adjust the stroller's height based on the child's requirements, enhancing both versatility and safety. Market participants are also leveraging technological advancements, such as smart safety features and GPS tracking, to enhance user convenience and differentiate their products. Strategic collaborations with healthcare institutions and non-profit organizations further strengthen market presence. Additionally, increasing e-commerce penetration is enabling companies to expand their customer base. As demand rises, competition intensifies, driving continuous improvements in product quality, affordability, and accessibility to meet evolving consumer needs.
Recent Developments:
- In March 2024, Sunrise Medical LLC Launched the QUICKIE Q50 R Carbon, their lightest folding power wheelchair with a transport weight of only 32 lbs, showcasing advancements in lightweight mobility solutions.
- In January 2024, Medline Industries, LP Acquired United MedCo, a leading supplemental benefits administrator, to expand their health plans business and enhance services for Medicare Advantage, Managed Medicaid, and commercial insurance markets.
- In June 2024, Drive DeVilbiss Healthcare Acquired Mobility Designed's portfolio of products, including their innovative M+D Comfort Crutch. This acquisition enhances Drive DeVilbiss Healthcare's range of mobility aids and brings cutting-edge industrial design expertise to their operations.
- In September 2024, R82 A/S (Etac Group) Introduced the R82 Chilla, a new adaptive buggy designed for both city use and nature exploration. The Chilla offers innovative features such as toolless back recline, adjustable suspension, and the ability to be both front and rear-facing. It's designed to grow with the child, accommodating changing needs over the years.
Market Concentration & Characteristics:
The adaptive stroller market exhibits a moderate to high level of market concentration, with a few established players holding a significant share due to their strong brand presence, extensive distribution networks, and continuous product innovation. Companies such as Invacare Corporation, Sunrise Medical LLC, and Ottobock SE & Co. KGaA dominate the market, leveraging advanced mobility solutions and strategic partnerships to maintain a competitive edge. The market is characterized by ongoing technological advancements, including lightweight materials, ergonomic designs, and smart safety features that enhance usability and comfort. Additionally, regulatory standards and government support for mobility aid accessibility shape the competitive landscape. Increasing consumer preference for customizable and portable solutions is driving product diversification. While developed regions exhibit strong brand dominance, emerging markets present opportunities for new entrants due to rising healthcare investments and growing awareness of assistive mobility solutions.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing demand for adaptive strollers will be driven by rising awareness of assistive mobility solutions and growing support for children with disabilities.
- Technological advancements, including smart safety features, GPS tracking, and sensor-based adjustments, will enhance product functionality and consumer appeal.
- Manufacturers will focus on lightweight, ergonomic, and foldable designs to improve portability and ease of use for caregivers.
- Expanding e-commerce and online retail platforms will improve product accessibility, allowing consumers to explore a wider range of options.
- Government initiatives and financial assistance programs will continue to play a crucial role in improving affordability and market penetration.
- Emerging markets, particularly in Asia-Pacific and Latin America, will present significant growth opportunities due to improving healthcare infrastructure and increasing disposable income.
- Customization and personalization trends will gain traction, with consumers seeking strollers tailored to specific mobility needs and aesthetic preferences.
- Strategic collaborations between manufacturers, healthcare institutions, and non-profit organizations will strengthen distribution networks and raise awareness.
- Increasing focus on sustainability will drive the adoption of eco-friendly materials and energy-efficient manufacturing processes in stroller production.
- Continuous investments in research and development will lead to the introduction of innovative products, expanding the market’s growth potential and meeting evolving consumer demands.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Mobility Disorders Among Children
The increasing incidence of conditions such as cerebral palsy, muscular dystrophy, and developmental disabilities is driving demand for adaptive strollers, as more children require specialized mobility solutions for daily activities and independence.
Technological Advancements and Product Innovation
Continuous improvements in lightweight materials, ergonomic designs, and the integration of smart features like GPS tracking and sensor-based safety mechanisms are making adaptive strollers more functional and appealing, encouraging higher adoption rates.
Government Support and Healthcare Reimbursement Policies
Supportive government initiatives, subsidies, and favorable insurance coverage in regions like North America and Europe are making adaptive strollers more affordable and accessible for families, thus expanding the market.
Expanding Distribution Channels and E-commerce Growth
The proliferation of online retail platforms and specialty mobility stores is increasing product accessibility, allowing caregivers to compare and purchase adaptive strollers more easily, which is fueling market growth.
Growing Awareness and Advocacy for Assistive Mobility Solutions
Educational campaigns, non-profit programs, and healthcare advocacy are raising awareness about the benefits of adaptive strollers, leading to greater acceptance and demand among parents, caregivers, and institutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current and projected market size of the adaptive stroller market?
What are the key drivers of the adaptive stroller market?
Which application segment governs the world's demand for adaptive strollers?
Which segment is expected to post the highest CAGR during the forecast period?
Who are the major players in the global adaptive stroller market?
What are the major market drivers of the adaptive stroller industry?
What are the major market restraints of the adaptive stroller industry?
What are the major market opportunities in the adaptive stroller industry?
What opportunities exist in emerging markets?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Lightweight Strollers
- 1.2.2 All-Terrain Strollers
- 1.2.3 Customizable Strollers
- 1.3 By End User
- 1.3.1 Children with Cerebral Palsy
- 1.3.2 Children with Muscular Dystrophy
- 1.3.3 Children with Developmental Disabilities
- 1.4 By Application
- 1.4.1 Hospitals and Rehabilitation Centers
- 1.4.2 Home Care
- 1.4.3 Specialized Institutions
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 510.6 million → 2032: USD 938 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Adaptive Strollers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Adaptive Strollers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Adaptive Strollers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Adaptive Strollers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Adaptive Strollers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Adaptive Strollers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Adaptive Strollers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Adaptive Strollers Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 510.6 million → 2032: USD 938 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Adaptive Strollers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Lightweight Strollers
- 12.3.7.2 All-Terrain Strollers
- 12.3.7.3 Customizable Strollers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Children with Cerebral Palsy
- 12.4.7.2 Children with Muscular Dystrophy
- 12.4.7.3 Children with Developmental Disabilities
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hospitals and Rehabilitation Centers
- 12.5.7.2 Home Care
- 12.5.7.3 Specialized Institutions
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Adaptive Strollers End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Adaptive Strollers Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Adaptive Strollers Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Adaptive Strollers Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Invacare Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sunrise Medical LLC
- 18.4 Ottobock SE & Co. KGaA
- 18.5 Medline Industries, LP
- 18.6 Convaid (Etac Group)
- 18.7 Drive DeVilbiss Healthcare
- 18.8 Eurovema Mobility AB
- 18.9 R82 A/S (Etac Group)
- 18.10 Hoggi GmbH
- 18.11 Meyra GmbH
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

