
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
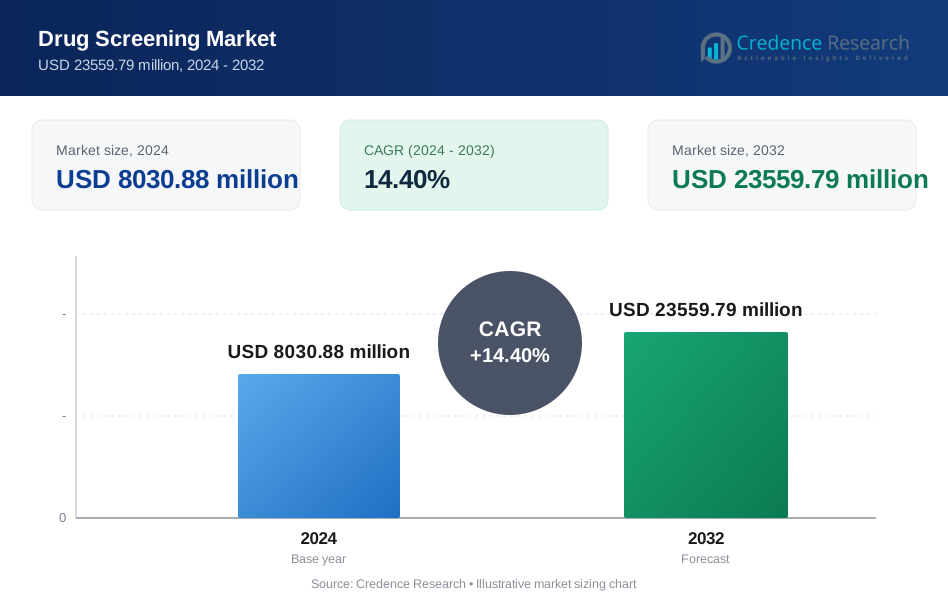
| Drug Screening Market Size 2024 | USD 8030.88 Million |
| Drug Screening Market, CAGR | 14.40% |
| Drug Screening Market Size 2032 | USD 23559.79 Million |
Market Overview
The Drug Screening market is projected to witness substantial growth, with its value expected to surge from USD 8030.88 million in 2024 to USD 23559.79 million by 2032, reflecting a remarkable compound annual growth rate of 14.40%.
The Drug Screening market is being propelled by several key drivers and trends. Heightened awareness and stringent regulations concerning workplace safety and substance abuse are fostering the adoption of drug screening solutions across various industries. Additionally, advancements in technology, such as the development of rapid testing kits and sophisticated analytical instruments, are enhancing the efficiency and accuracy of screening processes. Moreover, the growing prevalence of drug abuse and the increasing demand for preventive healthcare measures further contribute to the expansion of the market. These factors collectively drive innovation and investment in drug screening solutions, positioning the market for substantial growth in the foreseeable future.
Geographical analysis of the Drug Screening market reveals varying trends and opportunities across regions. North America dominates the market due to stringent regulations regarding drug screening in workplaces and the presence of major players such as Quest Diagnostics and Laboratory Corporation of America Holdings. Europe follows closely, driven by increasing awareness and government initiatives to combat substance abuse. Asia Pacific is witnessing rapid growth, fueled by expanding healthcare infrastructure and rising awareness among employers. Key players in the global Drug Screening market include Thermo Fisher Scientific Inc., Abbott Laboratories, and Siemens Healthineers, among others, who are actively engaging in strategic collaborations and product innovations to maintain their competitive edge.
Market Drivers
Alarming Rise in Global Drug and Alcohol Consumption:
A significant driver of the Drug Screening market is the alarming surge in global drug and alcohol use. For instance, the World Drug Report 2021 by the United Nations Office on Drugs and Crime (UNODC) estimated that about 5.5% of the population aged between 15 and 64 years have used drugs at least once in the past year. This equates to approximately 275 million people worldwide. Moreover, 36.3 million people, or 13% of the total number of persons who use drugs, suffer from drug use disorders. In terms of alcohol use, the World Health Organization (WHO) reported that the harmful use of alcohol results in the death of 3 million people annually. In 2018, the worldwide total consumption was equal to 6.2 litres of pure alcohol per person aged 15 years and older. These alarming statistics highlight the urgent need for accurate and reliable drug screening methods. Drug test accuracy statistics show that all four testing methods are 99% accurate when used correctly and contamination is avoided. However, certain types of drug screens are more susceptible to tampering or inaccurate readings than others.
Stricter Legislation and Workplace Drug Testing:
Governments worldwide are implementing stricter laws regarding drug use and driving under the influence (DUI), while many workplaces mandate drug testing for pre-employment, random, and reasonable suspicion scenarios. In terms of laws regarding drug use and DUI, the laws vary between countries. For example, in the United States, it is unlawful to drive a motor vehicle when the ability to do so is materially impaired by the consumption of alcohol or other drugs. In Canada, the rate of death from alcohol consumption remains high for a developed nation at 34 percent. As for workplace drug testing, according to Quest Diagnostics, the urine drug test positivity rate among the non-safety-sensitive workforce in the U.S. is at 4.6 percent, which is the highest level since 2001. A number of industries tested higher than the national average of 4.6%. Notably, these industries included Retail Trade (7.0%), Accommodation and Food Services (6.5%), and Transportation & Warehousing (5.5%).
Growing Pain Management Needs and Prescription Drug Abuse:
The increasing need for pain management fuels the use of prescription opioids and controlled substances, raising concerns about prescription drug abuse and diversion. For instance, the opioid epidemic is considered a public health emergency, with 136 deaths per day and climbing. Almost 50,000 people die every year from opioid overdose. Over 10 million people misuse opioids in a year. Opioids are a factor in at least 7 out of every 10 overdose deaths. In 2020, pharmacies filled 153 million opioid prescriptions. In terms of prescription drug abuse, 6% of Americans over the age of 12 abuse prescriptions in a year. 12% of prescription drug abusers are addicted. 59.277 million or 21.4% of people 12 and over have used illegal drugs or misused prescription drugs within the last year. In terms of drug diversion, it is estimated that there are 37,000 drug diverters each year nationwide. Drug diversion occurs when medication is redirected from its intended destination for personal use, sale, or distribution to others. It includes drug theft, use, or tampering.
Advancements in Drug Screening Technology and In-Home Testing Demand: Advancements in drug testing technologies, such as oral fluid testing and rapid point-of-care testing options, make screening faster, more accurate, and more convenient. Moreover, there's a growing demand for discreet and convenient drug testing options, including in-home testing kits and non-invasive methods, catering to personal use and court-ordered testing. These developments reflect a broader trend towards accessible and user-friendly drug screening solutions, driving market growth and innovation.
Market Trends
Expanding Testing Horizons:
In response to evolving needs and technological advancements, the Drug Screening market is witnessing a significant diversification of testing methods. For instance, the accuracy of drug testing methods varies. Drug test accuracy statistics show that all four testing methods (urine, hair, blood, and oral fluid) are 99% accurate when used correctly and contamination is avoided. However, certain types of drug screens are more susceptible to tampering or inaccurate readings than others. In terms of oral fluid testing, it has gained acceptance over the past decades as an alternative biological matrix for detecting drugs in forensic and clinical settings. Oral fluid testing offers simple, rapid, non-invasive, observed specimen collection. Based on workplace positivity rates, oral fluid positivity rates were comparable or slightly higher than urine. Overall drug positivity for oral fluid was 5.06% compared to 4.1% for urine. As for hair follicle testing, it can show whether someone used or abused drugs as far back as three months before the test. The accuracy statistics of hair follicle testing is also different for different substances. For example, studies have shown it to be superior to urine testing in detecting cocaine and opioids, but less reliable in detecting marijuana and alcohol. According to the results of a study, hair follicle drug testing correctly identified 52.3 percent of people who reported recent cannabis use, 65.2 percent of people who reported recent cocaine use, 24.2 percent of people who reported recent amphetamine use, and 2.9 percent of people who reported recent opioid use.
Innovative Solutions at the Forefront:
Rapid point-of-care testing emerges as a game-changer, enabling swift on-site screening with immediate results. In terms of roadside drug testing, over 2,550 drivers were arrested in 2022 on suspicion of drug driving in Ireland. In Australia, there were 507,207 roadside drug tests conducted in 2019, of those 10% were positive. In the US, more than 22% of drivers tested positive for illegal, prescription, or over-the-counter drugs. Biosensors have been used in drug discovery to facilitate the process of ion-channel-based drug discoveries. Regarding automation in drug testing procedures, a study found that automation adds significant improvements to most of the limitations inherent with point-of-care testing. Automation delivers semi-quantitative results, lower-level cutoffs, tailored drug panels, and error-free reporting. Particularly beneficial in workplace settings or roadside drug testing scenarios, this innovation enhances operational efficiency and decision-making processes. Moreover, the integration of advanced technologies like biosensors revolutionizes drug screening by enabling the detection of specific drug metabolites in sweat, blood, or breath samples. This real-time monitoring capability holds promise, especially in parole or probation situations where continuous surveillance is crucial. Additionally, the automation of laboratory processes streamlines drug testing procedures, ensuring standardization, reliability, and scalability. Furthermore, the integration of telemedicine platforms facilitates remote supervision of drug testing procedures and consultation with healthcare professionals, enhancing accessibility and support for individuals undergoing screening processes.
Market Challenges Analysis
Addressing False Positives and False Negatives:
Maintaining the accuracy and reliability of drug tests poses a significant challenge in the Drug Screening market. False positives and false negatives can have profound consequences, impacting individuals' livelihoods and organizational decisions. To mitigate these risks, standardized testing procedures, accurate test kits, and ensuring qualified personnel conduct interpretations are crucial. Investment in ongoing training and quality assurance measures is necessary to uphold the integrity of screening processes and minimize the occurrence of erroneous results.
Navigating the Rapidly Evolving Drug Landscape:
The rapid evolution of the drug landscape presents another challenge, with the emergence of new synthetic drugs continually challenging the effectiveness of existing screening panels. Staying ahead of these developments requires the adaptation of testing methods to detect novel substances effectively. This necessitates ongoing research and development efforts to enhance screening technologies and expand the scope of detectable substances. Additionally, collaboration with regulatory agencies and industry stakeholders is essential to anticipate emerging trends and implement proactive measures to address evolving drug threats.
Market Segmentation Analysis:
By Sample Type:
Urine samples dominate the Drug Screening market segment due to their widespread adoption and established reliability in detecting drug metabolites. This traditional sample type is favored for its convenience in collection and well-established testing methodologies. However, the segment faces challenges related to privacy concerns and potential adulteration, driving demand for alternative sample types. Oral fluid samples and hair samples represent promising segments witnessing steady growth. Oral fluid samples offer advantages such as non-invasiveness and the ability to detect recent drug use, making them increasingly popular, particularly in roadside testing and workplace scenarios. Similarly, hair samples provide a longer detection window, offering insights into historical drug use patterns, thus gaining traction in forensic and rehabilitation settings. As technology advances and acceptance of alternative sample types increases, these segments are expected to expand further.
By Product and Service:
Rapid testing devices emerge as a key segment experiencing significant growth, driven by the need for immediate results in various testing environments such as workplaces and point-of-care settings. These devices offer quick and convenient screening solutions, facilitating timely decision-making processes and enhancing operational efficiency. Additionally, advancements in technology contribute to the development of more accurate and user-friendly rapid testing devices, further fueling market expansion. As demand for on-the-spot testing continues to rise, this segment is poised for continued growth and innovation. The drug screening service segment is witnessing steady growth, fueled by the increasing outsourcing of screening processes by organizations seeking comprehensive testing solutions. Drug screening services offer expertise in sample collection, analysis, and result interpretation, catering to diverse industry needs and compliance requirements. Moreover, outsourcing drug screening tasks to specialized service providers allows organizations to focus on core operations while ensuring adherence to regulatory standards and quality assurance protocols. As the demand for accurate and reliable drug screening solutions continues to rise, the drug screening service segment is expected to remain a pivotal component of the market landscape, offering value-added services and comprehensive testing solutions to clients.
Segments:
Based on Sample Type:
- Urine samples
- Breath Samples
- Oral Fluid Samples
- Hair Samples
- Other Samples
Based on Product and Service:
- Drug screening
- Analytical Instruments
- Rapid Testing Devices
- Consumables
- Drug Screening Service
Based on End User:
- Drug Testing Laboratories
- Criminal Justice and Law Enforcement Agencies
- Hospitals
- Drug Treatment Centers
- Individual Users
- Pain Management Centers
- Schools and Colleges
- Workplaces
Based on the Geography:
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America currently holds the largest market share, accounting for approximately 40% of the global drug screening market. The region's strict regulations regarding workplace safety, the high incidence of substance abuse, and the presence of major industry players have contributed to its dominant position. The United States, in particular, has been at the forefront of implementing comprehensive drug testing policies across various sectors, including transportation, healthcare, and government organizations.
Europe
Europe follows closely behind, with a market share of around 30%. Countries like the United Kingdom, Germany, and France have implemented stringent regulations for drug screening in industries such as transportation and manufacturing. The region's focus on promoting workplace safety, reducing the societal impact of substance abuse, and the availability of advanced testing technologies have fueled market growth. Additionally, the increasing adoption of drug screening in the sports sector has further boosted the demand for reliable testing solutions in Europe.
Key Player Analysis
- Hoffmann -La Roche Ltd
- BioMerieux SA
- Express Diagnostics Int’l, Inc.
- Bio-Rad Laboratories Inc.
- Biomedical Diagnostics
- Danaher
- Synergy Health plc.
- Agilent Technologies
- Shimadzu Medical Pvt. Ltd.
- Alere Inc.
Competitive Analysis
In the competitive landscape of the Drug Screening market, leading players such as Hoffmann-La Roche Ltd, BioMerieux SA, and Express Diagnostics Int'l, Inc. stand out for their extensive product portfolios and established market presence. These companies offer a wide range of drug screening solutions, including analytical instruments, rapid testing devices, and consumables, catering to diverse industry needs. Bio-Rad Laboratories Inc., Danaher, and Agilent Technologies are recognized for their innovation-driven approach, continually investing in research and development to enhance the accuracy and efficiency of drug screening technologies. Additionally, companies like Shimadzu Medical Pvt. Ltd., Alere Inc., and Psychemedics Corporation specialize in specific niche areas, offering unique solutions such as hair follicle testing and point-of-care devices. With strategic partnerships, mergers, and acquisitions, these leading players strengthen their market positions and expand their global reach, driving competitiveness and innovation in the Drug Screening market.
Recent Developments
In February 2024, Mobile Health introduced a new rapid drug testing service in New York clinics for employers to screen and hire candidates easily.
In March 2023, Shenzhen Superbio Technology Co., LTD. (Superbio) received clearance from the United States Food and Drug Administration (FDA) on the first-ever point-of-care instrument intended for the qualitative detection of fentanyl in human urine and has fully released authorization to Bioeasy USA, Inc.(Bioeasy) of this product in the United States of America. In December 2022, PhoreMost Ltd. and ThinkCyte K.K announced a strategic research partnership to advance phenotypic drug screening using artificial intelligence (AI). Combining PhoreMost's expertise in phenotypic screening with ThinkCyte's AI capabilities, the collaboration aims to accelerate drug discovery processes, potentially yielding novel therapeutics.
In April 2022, Saladax Biomedical, Inc acquired a patent portfolio for antipsychotic drug testing from Janssen Pharmaceutica NV. This intellectual property (IP) portfolio includes 17 patent families. This strategy placed the company in a premier position in the antipsychotic drug testing field.
Market Concentration & Characteristics
In the Drug Screening market, market concentration and characteristics are notable for their dynamic interplay between established industry leaders and emerging players. Leading companies often possess extensive product portfolios, advanced technological capabilities, and global distribution networks, contributing to a significant market share. This concentration fosters competition, driving innovation and quality improvements in drug screening technologies and services. Additionally, the market exhibits characteristics of continual evolution, with rapid advancements in testing methodologies, sample types, and regulatory requirements shaping industry dynamics. Emerging trends such as the integration of telemedicine, personalized testing solutions, and emphasis on data security further characterize the market landscape. Furthermore, the market's susceptibility to regulatory changes and the growing demand for comprehensive screening solutions underscore the need for adaptability and agility among market participants. Overall, market concentration and characteristics reflect a dynamic ecosystem driven by innovation, regulatory compliance, and evolving customer demands in the Drug Screening market.
Report Coverage
The research report offers an in-depth analysis based on Sample Type, Product and Service, End User, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Continued Growth: The Drug Screening market is projected to witness sustained growth driven by increasing awareness of substance abuse and stringent regulatory frameworks.
- Technological Advancements: Ongoing innovations in drug screening technologies, such as biosensors and rapid testing devices, will enhance efficiency and accuracy.
- Expansion of Sample Types: There will be a continued expansion of sample types beyond urine to include oral fluid, hair, and other alternative samples, catering to diverse testing needs.
- Integration of Artificial Intelligence: Artificial intelligence and machine learning applications will play a significant role in data analysis, result interpretation, and predictive analytics.
- Rise in Point-of-Care Testing: The demand for rapid point-of-care testing solutions will increase, driven by the need for immediate results and convenience in various testing environments.
- Regulatory Compliance: Compliance with evolving regulatory standards and industry guidelines will remain a priority for companies to ensure quality and safety in drug screening practices.
- Emphasis on Privacy and Data Security: With the increasing use of electronic testing and data collection, ensuring data security and patient privacy will be paramount, driving investments in cybersecurity measures.
- Personalized Testing Solutions: There will be a growing trend towards personalized testing solutions tailored to individual needs and preferences, promoting accessibility and user experience.
- Expansion in Emerging Markets: Emerging markets, particularly in Asia-Pacific and Latin America, will present lucrative opportunities for market expansion due to increasing healthcare infrastructure and rising awareness.
- Integration with Healthcare Systems: Greater integration of drug screening with healthcare systems, including electronic medical records and telemedicine platforms, will facilitate seamless patient management and improve clinical outcomes.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Drug Screening market?
What factors are driving the growth of the Drug Screening market?
What are the key segments within the Drug Screening market?
What are some challenges faced by the Drug Screening market?
Who are the major players in the Drug Screening market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Drug Screening Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Drug Screening Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 8030.88 million → 2032: USD 23559.79 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Drug Screening Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Drug Screening Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Drug Screening Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Drug Screening Market Drivers
- 3.3 Drug Screening Market Restraints & Challenges
- 3.4 Drug Screening Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Drug Screening Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Drug Screening Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Drug Screening category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Drug Screening Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Drug Screening Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Drug Screening market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Drug Screening Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Drug Screening Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Drug Screening Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Drug Screening (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Drug Screening Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Drug Screening Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Drug Screening Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Drug Screening Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Drug Screening Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Drug Screening Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Drug Screening Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Drug Screening Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Drug Screening Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
