
Market overview
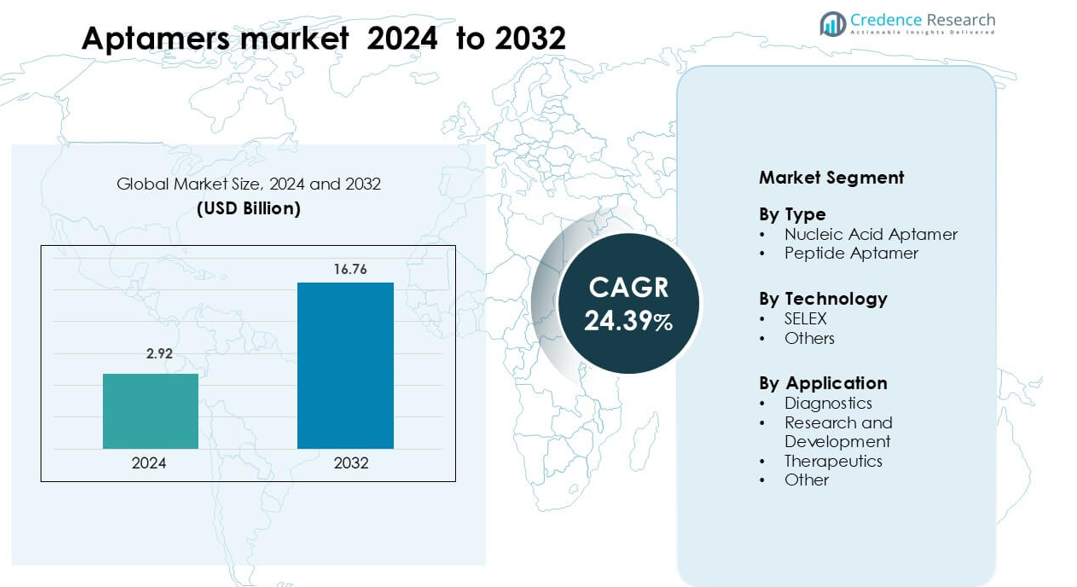
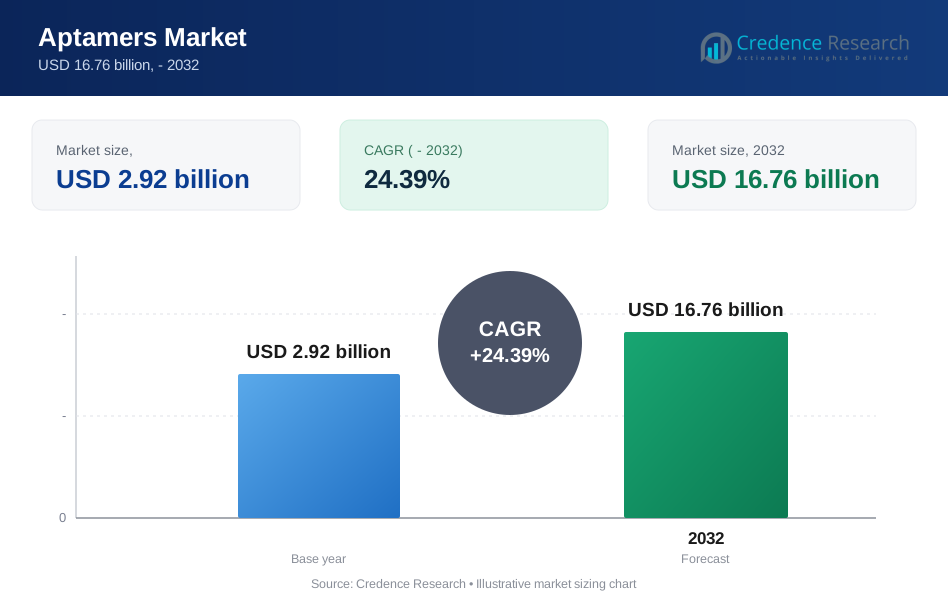
Aptamers market was valued at USD 2.92 billion in 2024 and is anticipated to reach USD 16.76 billion by 2032, growing at a CAGR of 24.39% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Apple Juice Market Size 2024 | USD 2.92 billion |
| Apple Juice Market, CAGR | 24.39% |
| Apple Juice Market Size 2032 | USD 16.76 billion |
The Aptamers market includes key players such as Aptagen, 2bind GmbH, AuramerBio, AMS Biotechnology Limited, Aptamer Group, Creative Biogene, Barrick Lab, IBA GmbH, TriLink BioTechnologies, and NeoVentures Biotechnology Inc. These companies expand their presence through advanced SELEX platforms, custom aptamer libraries, and partnerships with diagnostic and pharmaceutical firms. Product development focuses on higher target specificity, improved stability, and scalable manufacturing to serve diagnostics, therapeutics, and research applications. North America stands as the leading region, holding about 39.4% share in 2024, supported by strong biotech clusters, high R&D spending, and rapid adoption of molecular diagnostic technologies.
Market Insights
- The Aptamers market is valued at USD 2.92 billion in 2024 and is projected to reach USD 16.76 billion by 2032, growing at a CAGR of about 24.39 % during the forecast period.
- Strong demand in diagnostics acts as the key driver, with the segment holding about 46% share, driven by rapid testing needs, high binding accuracy, and expanding use in oncology and infectious disease detection.
- Market trends include rising automation in SELEX workflows, growing interest in point-of-care aptamer assays, and expanding R&D applications supported by advanced molecular screening platforms.
- Competitive landscape features companies such as Aptagen, 2bind GmbH, AuramerBio, AMS Biotechnology Limited, Aptamer Group, Creative Biogene, Barrick Lab, IBA GmbH, TriLink BioTechnologies, and NeoVentures Biotechnology Inc., all focusing on improved affinity, stability, and custom development services.
- North America leads the global market with about 39.4% share, followed by Europe at roughly 27.9%, while Asia-Pacific grows fastest with around 28.7% share, supported by strong biotech expansion.
Market Segmentation Analysis:
By Type
Nucleic acid aptamers lead this segment with about 72% share in 2024. These molecules dominate because researchers value their strong target affinity, chemical stability, and easy synthesis. Demand grows as labs adopt nucleic acid aptamers for biomarker discovery, drug targeting, and rapid diagnostics. Peptide aptamers grow at a steady pace due to higher structural diversity, but adoption remains lower because production is costlier and optimization takes longer. Rising use of nucleic acid formats in precision medicine continues to reinforce segment leadership.
- For instance, Avacta has developed Affimer reagents (a kind of peptide aptamer scaffold) that inhibit immune-complex binding by targeting FcγRIIIa, showing that peptide-based scaffolds can be used with high specificity in protein–protein interaction modulation.
By Technology
SELEX holds the dominant position with nearly 81% share in 2024. The process leads because SELEX enables systematic selection of high-affinity aptamers for complex biological targets. Growth rises as SELEX workflows become faster through automation and enhanced screening methods. The “Others” category, including cell-based and microfluidic platforms, expands as firms seek higher throughput, yet uptake stays smaller due to limited standardization. SELEX continues to lead adoption as researchers depend on its proven selection accuracy and reproducible performance.
- For instance, Capillary Electrophoresis (CE)-SELEX, as used in advanced labs, can complete aptamer selection in just 1–4 rounds, compared to the 8–20 rounds typical of conventional SELEX.
By Application
Diagnostics remain the largest application with around 46% share in 2024. Diagnostic use leads because aptamers help create rapid, sensitive tests for infectious diseases, cancer markers, and metabolic disorders. Healthcare labs prefer aptamer-based assays due to low batch variability and quick response time. Research and development follows as scientists apply aptamers for target validation and molecular screening. Therapeutics grow as firms explore aptamer-drug conjugates, but regulatory pathways remain longer. Strong demand for fast diagnostic tools drives the dominance of this segment.
Key Growth Drivers
Rising Adoption in Diagnostics
Demand rises as hospitals shift toward fast testing methods using aptamer-based tools. Many labs prefer aptamers because the molecules bind targets with strong accuracy. These traits support reliable detection of cancer markers and viral proteins. Diagnostic firms now design low-cost kits for wide testing use. The approach reduces batch variation and helps maintain steady output. Healthcare centers choose these kits to speed patient screening. Point-of-care devices also drive market growth. Many devices use aptamers to improve test sensitivity. Global disease surveillance programs increase testing needs. Research groups supply new sequences for advanced detection. Expanding screening programs raise consumable use. The trend strengthens demand across major markets.
- For instance, a group using graphene-oxide cell-SELEX selected 96 ssDNA aptamers over 11 rounds to target SARS-CoV-2; two aptamers showed dissociation constants (Kₙ) in the range of ~200–500 nM, and one (Apt 91) detected virus in over 97 % of clinical nasopharyngeal samples.
Growth in Targeted Therapeutics
Pharma firms explore aptamers for targeted drug delivery systems. Many companies value the strong binding features. The approach helps direct treatment with improved precision. Developers test aptamer-drug pairs for safer therapy. Early results show strong targeting strength. This benefit reduces unwanted effects and improves dose control. Firms build platforms for rapid aptamer selection. These tools shorten development cycles. Research improves sequence stability for longer drug action. Investment grows as the method supports precision therapy goals. Clinical trials expand in key disease areas. These studies drive interest from large drug makers.
- For instance, researchers engineered the DNA aptamer sgc8c (which binds PTK7 on ALL cells) conjugated to doxorubicin via a hydrazone linker; in cell assays, this sgc8c–DOX conjugate internalized efficiently into CCRF-CEM cells and exhibited therapeutic potency similar to free DOX but with much lower non-target cell toxicity.
Expansion in Research Applications
Research centers use aptamers for protein tracking and cell studies. Many labs trust the high binding accuracy. The approach supports clean and repeatable results. Universities adopt aptamers for low-cost experiments. The method helps students access reliable tools. Scientists use advanced SELEX platforms for faster selection. Automation expands research output. Many studies test new targets each year. These results broaden market reach. Growth continues as funding supports biomarker programs. Global research networks share new formats. This knowledge flow strengthens adoption worldwide.
Key Trends and Opportunities
Shift Toward Automated SELEX Platforms
Automation makes selection steps faster and cleaner. Many labs adopt compact systems. The tools support high-throughput screening tasks. This change improves sequence quality and yield. Firms launch improved devices for faster rounds. Automation reduces manual errors. Many researchers value consistent results. Companies bundle software for quicker data checks. Adoption grows across small labs. These gains help widen aptamer discovery use. The trend supports lower selection time. Market interest rises as automation improves workflow strength.
- For instance, the HAPIscreen method uses a 384-well (and potentially 1,536-well) automated format, shortening the time from enriched SELEX pools to high-affinity aptamer identification by at least 50%.
Rising Focus on Point-of-Care Tools
Point-of-care kits use aptamers for rapid testing. These tools support quick checks in clinics. Many kits run without complex hardware. Developers build light and sturdy formats. The approach improves emergency screening speed. Governments support quick testing systems. This support encourages wider deployment. Aptamers help improve device sensitivity. Many firms target rural areas. Growth accelerates in emerging regions. These trends create new product lines. Market players expand supply networks.
- For instance, Zentek uses single-stranded DNA aptamers in a portable electrochemical sensor that gives saliva-based COVID-19 test results in under 10 minutes using minimal hardware.
Key Challenges
Complex Regulatory Pathways
Therapeutic aptamers face long review steps. Many agencies require deep safety checks. This increases development time. Companies must run wide trials. These trials demand high resources. Small firms face pressure. Many projects slow without funding. Delays impact launch timelines. Developers must meet strict quality rules. These rules add heavy workload. Market entry becomes slower. Growth in therapeutics gets limited. These hurdles challenge new players.
Stability and Delivery Limitations
Some aptamers need improved stability. Molecules may degrade inside the body. This reduces treatment impact. Firms test chemical fixes. These fixes raise cost levels. Delivery systems remain under development. Many formats need better shielding. Weak delivery lowers product success. Research tries new carriers. Carriers add extra steps. These challenges slow therapeutic growth. Market players push for improved designs. Continuous work is required.
Regional Analysis
North America
In 2024, North America accounted for about 39.4% share of the global Aptamers market, based on regional revenue estimates from Verified Market Research The region benefits from a mature biotechnology ecosystem, strong university–industry links, and high healthcare spending. Extensive clinical pipelines for aptamer-based oncology and ophthalmology drugs further reinforce leadership. The U.S. alone contributed over 40% of global aptamers revenue in 2023, which underlines regional dominance. Supportive regulators and robust venture funding continue to drive adoption of aptamer platforms in diagnostics, therapeutics, and drug discovery workflows.
Europe
The Aptamers market in Europe represented roughly 27.9% global share in 2024, calculated from regional revenue of about 0.85 billion against total regional sales. Grand View Research also reported that Europe captured 25.3% share in 2023, confirming its role as the second-largest regional cluster. Growth in 2024 is supported by strong pharma and biotech bases in Germany, the U.K., and France, where nucleic acid aptamers dominate type demand Increasing approvals of advanced molecular diagnostics, together with EU funding for precision medicine and in-vitro diagnostic innovation, continue to expand use of aptamer assays and research tools.
Asia-Pacific
In 2024, Asia-Pacific held an estimated 28.7% share of the global Aptamers market, derived from regional revenue of about 0.876 billion versus the summed regional total. Horizon data show Asia-Pacific aptamers revenue at 494.7 million in 2023, which already equated to just over one-fifth of global sales and was growing at more than 26% CAGR. China, Japan, India, and South Korea drive demand through rapid expansion of biotech infrastructure, strong government funding, and rising clinical research activity. The region is now the fastest-growing Aptamers market, with extensive opportunities in oncology diagnostics, infectious disease testing, and low-cost research reagents.
Latin America
Latin America accounted for a smaller but meaningful 1.1% share of the global Aptamers market in 2024, based on a regional valuation of 0.035 billion Grand View Research reported 140.2 million aptamers revenue for Latin America in 2023, which translates to roughly 6% of global turnover in that year, reflecting early but accelerating adoption. Brazil and Mexico lead regional demand as laboratories modernize molecular diagnostics and pharmaceutical quality testing. Key drivers include growing oncology and infectious disease burdens, interest in cost-effective biosensors, and partnerships bringing international aptamer platforms into local clinical laboratories and research institutes.
Middle East & Africa
The Middle East & Africa held about 2.9% share of the global Aptamers market in 2024, derived from a regional value of 0.087 billion against combined regional revenue. Market Data Forecast separately reported Middle East & Africa aptamers revenue near 14.91 million for 2024 in a narrower segment view, confirming a relatively small but growing base. Adoption concentrates in Gulf Cooperation Council countries, Israel, and South Africa, where healthcare investment and advanced diagnostic infrastructure are expanding. Growth in 2024 is driven by rising cancer diagnostics, imported high-end analyzers that integrate aptamer assays, and national strategies to upgrade laboratory capabilities across tertiary hospitals and reference labs.
Market Segmentations
By Type
- Nucleic Acid Aptamer
- Peptide Aptamer
By Technology
- SELEX
- Others
By Application
- Diagnostics
- Research and Development
- Therapeutics
- Other
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive Landscape Competitive landscape in the Aptamers market features key companies such as Aptagen, 2bind GmbH, AuramerBio, AMS Biotechnology Limited, Aptamer Group, Creative Biogene, Barrick Lab, IBA GmbH, TriLink BioTechnologies, and NeoVentures Biotechnology Inc. These players compete by advancing SELEX efficiency, improving chemical stability, and expanding custom aptamer development services. Many firms invest in automation to shorten selection cycles and increase throughput for diagnostics, therapeutics, and research applications. Strategic collaborations with pharma and diagnostic developers strengthen market reach, while new product launches focus on higher binding affinity and improved assay performance. Companies also expand manufacturing capabilities to support rising demand for nucleic acid aptamers across oncology, infectious diseases, and biomarker discovery.
Key Player Analysis
- Aptagen
- 2bind GmbH
- AuramerBio
- AMS Biotechnology Limited
- Aptamer Group
- Creative Biogene
- Barrick Lab
- IBA GmbH
- TriLink BioTechnologies
- NeoVentures Biotechnology Inc.
Recent Developments
- In October 2024, GmbH: 2bind announced a new Co-CEO leadership team, with Dr. Maximilian Plach and Dr. Cosimo Kropp leading the CRO’s expansion in biophysical services, including its aptamer discovery and characterization offerings for pharma and biotech partners
- In September 2024, Aptagen secured a contract from the FDA’s Center for Biologics Evaluation and Research to develop Amb a 1-specific aptamers to measure the biological potency of commercial ragweed pollen extracts, strengthening its position as a specialist aptamer developer for regulated applications
Report Coverage
The research report offers an in-depth analysis based on Type, Technology, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Aptamers market will expand rapidly as demand rises for high-specificity diagnostic tools.
- Therapeutic aptamers will gain traction as stability and delivery technologies improve.
- Automation in SELEX processes will shorten development cycles and increase adoption across labs.
- Point-of-care devices will integrate more aptamer-based assays to support faster clinical decisions.
- Pharma collaborations will strengthen as companies explore aptamer-drug conjugates for targeted treatments.
- Research institutions will increase aptamer use for biomarker discovery and molecular screening.
- Advances in chemical modification will improve aptamer durability for complex clinical environments.
- Emerging markets in Asia-Pacific will accelerate growth through expanding biotechnology infrastructure.
- Regulatory clarity will improve, supporting smoother development pathways for therapeutic products.
- New companies will enter the market with innovative platforms, raising competition and technological advancement.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Adoption in Diagnostics
Hospitals and laboratories are increasingly using aptamer-based diagnostic tools for rapid, accurate detection of cancer markers and infectious diseases. The high binding specificity and low batch variability of aptamers make them ideal for point-of-care and high-throughput testing, driving strong demand in this segment.
Growth in Targeted Therapeutics
Pharmaceutical companies are investing in aptamer-drug conjugates for targeted drug delivery, leveraging aptamers' strong binding affinity to improve treatment precision and reduce side effects. This trend is supported by ongoing clinical trials and advancements in aptamer stability and delivery technologies.
Expansion in Research Applications
Research institutions and universities are adopting aptamers for protein tracking, biomarker discovery, and molecular screening due to their reproducibility, chemical stability, and cost-effectiveness. Automation in SELEX workflows further accelerates aptamer discovery and broadens research use.
Shift Toward Automated SELEX Platforms
Automation of SELEX (Systematic Evolution of Ligands by Exponential Enrichment) processes is reducing selection time and increasing throughput, making aptamer discovery more efficient and accessible. This technological advancement is enabling faster development cycles and supporting wider adoption across diagnostics, therapeutics, and research.
Rising Focus on Point-of-Care Tools
The integration of aptamers into portable, rapid diagnostic devices is expanding access to high-sensitivity testing in clinics and remote settings. Government support for quick testing systems and the need for decentralized healthcare solutions are fueling the growth of aptamer-based point-of-care assays.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Aptamers market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Aptamers market projected to grow between 2025 and 2032?
What is the global aptamers marketplace?
What are the essential programs of aptamers?
What factors are driving the growth of the worldwide aptamers marketplace?
What are the benefits of the usage of aptamers over antibodies?
What are the key demanding situations inside the worldwide aptamers market?
What are the important areas contributing to the worldwide aptamers marketplace?
What are the potentialities for the worldwide aptamers market?
Who are the leading companies in the Aptamers market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Nucleic Acid Aptamer
- 1.2.2 Peptide Aptamer
- 1.3 By Technology
- 1.3.1 SELEX
- 1.3.2 Others
- 1.4 By Application
- 1.4.1 Diagnostics
- 1.4.2 Research and Development
- 1.4.3 Therapeutics
- 1.4.4 Other
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2.92 billion → 2032: USD 16.76 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Aptamers Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Aptamers Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Aptamers Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Aptamers Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Aptamers Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Aptamers Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Aptamers Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Aptamers Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2.92 billion → 2032: USD 16.76 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Aptamers Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Nucleic Acid Aptamer
- 12.3.7.2 Peptide Aptamer
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 SELEX
- 12.4.7.2 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Diagnostics
- 12.5.7.2 Research and Development
- 12.5.7.3 Therapeutics
- 12.5.7.4 Other
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Aptamers End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Aptamers Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Aptamers Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Aptamers Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Aptagen
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 2bind GmbH
- 18.4 AuramerBio
- 18.5 AMS Biotechnology Limited
- 18.6 Aptamer Group
- 18.7 Creative Biogene
- 18.8 Barrick Lab
- 18.9 IBA GmbH
- 18.10 TriLink BioTechnologies
- 18.11 NeoVentures Biotechnology Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

