
Market Overview:
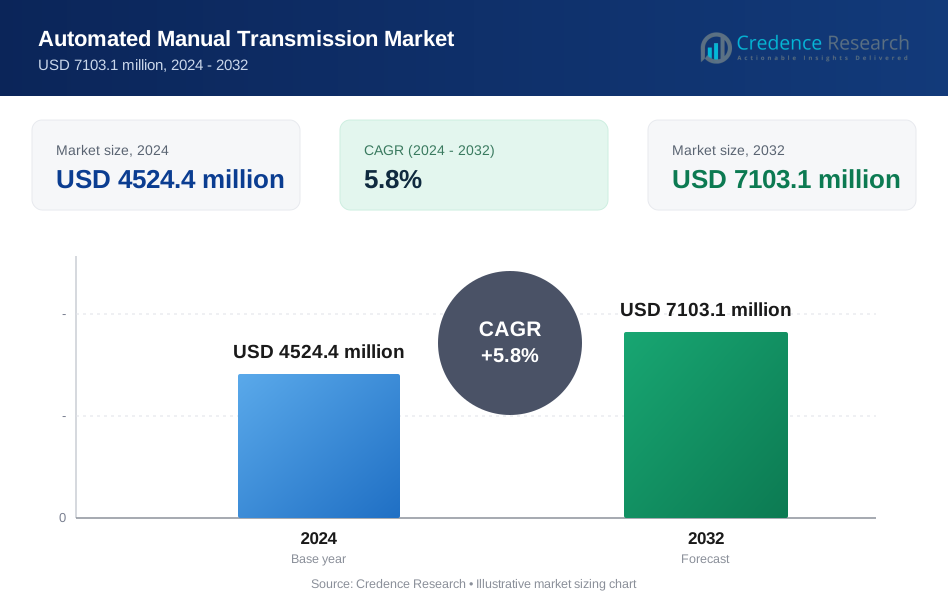
The Automated Manual Transmission (AMT) Market size was valued at USD 4524.4 million in 2024 and is anticipated to reach USD 7103.1 million by 2032, at a CAGR of 5.8% during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Automated Manual Transmission (AMT) Market Size 2024 | USD 4524.4 million |
| Automated Manual Transmission (AMT) Market, CAGR | 5.8% |
| Automated Manual Transmission (AMT) Market Size 2032 | USD 7103.1 million |
Key drivers influencing the AMT market include increasing consumer demand for smoother driving experiences combined with affordability compared to fully automatic transmissions. The integration of AMT technology offers the benefits of manual gear efficiency with automated control, making it attractive to manufacturers and end-users seeking a balance between performance and cost. Additionally, stringent emission regulations and rising fuel efficiency requirements are encouraging automakers to adopt AMT systems, especially in emerging markets. Growing urbanization and traffic congestion also support AMT adoption, as it enhances driving comfort in stop-and-go conditions. The rising penetration of electric and hybrid vehicles equipped with advanced transmission systems is further boosting the adoption of AMT technology worldwide.
Regionally, Asia Pacific dominates the AMT market due to high passenger vehicle demand, expanding automotive production, and strong adoption in India, China, and Japan. Europe follows with widespread integration of AMT in commercial and passenger vehicles, while North America shows steady adoption supported by consumer preference for advanced vehicle technologies and premium driving comfort. Latin America and the Middle East are also emerging as potential growth regions, supported by increasing urban mobility needs and gradual technological adoption.

Market Insights:
- The Automated Manual Transmission (AMT) Market was valued at USD 4524.4 million and is projected to reach USD 7103.1 million by 2032, registering a CAGR of 5.8% during the forecast period.
- Rising demand for cost-effective automation in vehicles is driving adoption, with AMT offering smoother driving experiences at lower costs compared to fully automatic systems.
- Stringent emission regulations and the need for improved fuel efficiency are pushing automakers to integrate AMT solutions that optimize performance and reduce environmental impact.
- Increasing urbanization and heavy traffic congestion are fueling the demand for AMT, as it provides comfort and convenience in frequent stop-and-go driving conditions.
- The growing penetration of electric and hybrid vehicles is creating new opportunities, with AMT systems enhancing energy efficiency, range, and overall performance.
- Asia Pacific leads the market with 47% share, supported by strong adoption in India, China, and Japan, followed by Europe with 28% and North America with 17%.
- Latin America and the Middle East collectively hold 8% share, with steady growth expected due to rising urban mobility needs and gradual acceptance of advanced transmission systems.
Market Drivers:
Rising Demand for Cost-Effective Automation in Vehicles
The Automated Manual Transmission (AMT) Market is driven by the rising preference for affordable automation in passenger and light commercial vehicles. Consumers in cost-sensitive markets seek transmission systems that provide driving comfort without the higher price tag of fully automatic transmissions. AMT systems bridge this gap by combining manual gearbox efficiency with automated gear shifting. It has become a preferred choice for manufacturers aiming to deliver enhanced value in compact and mid-sized vehicle segments.
- For instance, Maruti Suzuki’s Fronx model equipped with its Auto Gear Shift (AGS) transmission has an ARAI-certified fuel efficiency of 22.89 kilometers per liter.
Stringent Emission Regulations and Fuel Efficiency Requirements
Growing regulatory pressures to reduce emissions and improve fuel efficiency are strongly influencing the adoption of AMT systems. The Automated Manual Transmission (AMT) Market benefits from its ability to optimize gear shifts for better fuel economy while maintaining compliance with global emission standards. Automakers are increasingly adopting AMT to meet regulatory targets while ensuring consumer affordability. It is positioned as a sustainable solution that balances environmental responsibility with economic viability.
- For instance, the Tata Punch offers a 5-speed AMT option that delivers an ARAI-claimed mileage of 18.8 kilometers per liter, successfully balancing automatic convenience with fuel-conscious performance.
Increasing Urbanization and Traffic Congestion Supporting Adoption
Urban population growth and rising traffic congestion are creating significant demand for transmission systems that reduce driver fatigue. The Automated Manual Transmission (AMT) Market gains momentum in urban settings, where frequent gear shifts in stop-and-go traffic make manual driving less convenient. AMT technology offers seamless gear transitions that improve comfort and reduce physical strain. It has emerged as a practical solution that enhances driving experiences in densely populated regions.
Integration of AMT in Electric and Hybrid Vehicle Platforms
The rapid expansion of electric and hybrid vehicles is opening new opportunities for AMT technology. The Automated Manual Transmission (AMT) Market is witnessing innovation as manufacturers integrate advanced AMT systems into next-generation vehicle platforms. This integration improves power efficiency and driving range while supporting smooth performance. It strengthens the role of AMT as a versatile transmission solution aligned with the industry’s shift toward electrification.
Market Trends:
Advancements in Transmission Technology and Integration with Smart Mobility
The Automated Manual Transmission (AMT) Market is witnessing significant advancements in gear-shift precision, electronic control units, and software optimization, which are improving driving comfort and fuel efficiency. Automakers are focusing on refining clutch control and shift responsiveness to deliver a smoother experience comparable to fully automatic systems. The integration of AMT technology with smart mobility solutions, such as connected vehicles and telematics, is gaining momentum across global markets. It is also being aligned with digital platforms that enable predictive maintenance and real-time performance monitoring. The growing adoption of artificial intelligence and machine learning in automotive electronics is further enhancing AMT capabilities. These innovations strengthen the position of AMT as a cost-efficient yet technologically advanced transmission option for both passenger and commercial vehicles.
- For instance, ZF Friedrichshafen celebrated a significant production milestone, having produced 500,000 units of its TraXon automated manual transmission system at its main plant.
Expansion Across Electric, Hybrid, and Emerging Market Segments
The Automated Manual Transmission (AMT) Market is expanding its footprint beyond traditional combustion-engine vehicles into electric and hybrid platforms. Manufacturers are developing advanced AMT systems that optimize energy efficiency, range, and driving performance in next-generation vehicles. It is also gaining strong traction in emerging markets such as India, China, and Southeast Asia, where urbanization and rising vehicle ownership drive demand for affordable automated solutions. Regional governments are supporting the adoption of efficient transmission systems through incentives and stricter emission norms. The trend of lightweight vehicle design and the use of eco-friendly materials in AMT components further support market growth. With rising global investments in automotive innovation, AMT is becoming an integral part of evolving mobility ecosystems.
- For instance, in India, Maruti Suzuki has sold over 1 million cars equipped with its Auto Gear Shift (AGS) technology.
Market Challenges Analysis:
Perception Issues and Competitive Pressure from Alternative Transmissions
The Automated Manual Transmission (AMT) Market faces challenges due to consumer perceptions regarding shift lag and performance limitations compared to fully automatic and dual-clutch transmissions. While AMT offers affordability, some buyers associate it with lower refinement, which affects its acceptance in premium vehicle categories. Competing technologies such as CVT and DCT provide smoother transitions and advanced features, creating strong competition. It is crucial for manufacturers to address these performance concerns through continuous technological upgrades. Market adoption in developed economies remains limited as consumers prefer advanced transmission options with higher comfort levels.
Cost Sensitivity and Aftermarket Maintenance Concerns
The Automated Manual Transmission (AMT) Market also encounters hurdles from cost-sensitive buyers who weigh repair and maintenance expenses before adoption. AMT systems, though affordable initially, often require specialized servicing that raises long-term ownership costs. It is a barrier in emerging markets where price and ease of service strongly influence buying decisions. Lack of widespread technical expertise in local service networks further complicates adoption in rural and semi-urban areas. The balance between affordability, durability, and after-sales support will define how effectively AMT can expand its global reach.
Market Opportunities:
Growing Demand in Emerging Markets and Entry-Level Vehicle Segments
The Automated Manual Transmission (AMT) Market presents strong opportunities in emerging economies where affordability and fuel efficiency drive consumer preferences. Rising urbanization and traffic congestion in countries like India, China, and Brazil create a favorable environment for AMT adoption in entry-level passenger vehicles. It offers an attractive balance between cost and convenience, making it a preferred choice among first-time buyers. Expanding middle-class populations with rising disposable incomes further support market penetration. Government initiatives promoting cleaner and more efficient mobility solutions are also expected to accelerate AMT demand in these regions.
Expansion into Electric, Hybrid, and Commercial Vehicle Platforms
The Automated Manual Transmission (AMT) Market has opportunities to expand its role in electric and hybrid vehicles, where optimized transmission efficiency enhances range and driving performance. Automakers are exploring AMT integration into next-generation platforms to meet evolving sustainability goals. It also holds potential in light and heavy commercial vehicles, where fuel savings and reduced driver fatigue provide operational benefits. Growing investments in automotive innovation and the shift toward smart, connected mobility solutions strengthen AMT’s relevance. Strategic partnerships between technology providers and manufacturers are expected to unlock new growth avenues globally.
Market Segmentation Analysis:
By Speed
The Automated Manual Transmission (AMT) Market by speed is segmented into four-speed, five-speed, six-speed, and above six-speed configurations. Four-speed and five-speed systems dominate in entry-level and compact vehicles, offering a balance of affordability and basic automation. Six-speed and above systems are gaining preference in mid-sized and premium models, where smoother transitions, improved fuel efficiency, and enhanced performance are key requirements. It is expected that demand for higher-speed configurations will rise as automakers prioritize advanced driving comfort and compliance with evolving emission standards.
- For instance, Volkswagen paired its advanced 7-speed DSG automated transmission with the 1.2 TSI engine in the Polo, a combination capable of producing a maximum torque of 175 Newton-meters.
By Vehicle Type
The Automated Manual Transmission (AMT) Market is divided into passenger vehicles, light commercial vehicles, and heavy commercial vehicles. Passenger vehicles represent the largest share, driven by growing consumer demand for affordable automation in urban markets. Light commercial vehicles are adopting AMT systems to improve efficiency, reduce driver fatigue, and optimize operations in logistics and urban transport. Heavy commercial vehicles, though slower in adoption, are recognizing the benefits of fuel savings and improved drivability, particularly in markets with rising infrastructure and freight activity. It is evident that AMT technology is becoming versatile across segments, providing value in cost-sensitive categories while expanding its role in higher-capacity vehicles with advanced performance needs.
- For instance, Volvo Trucks enhanced its D13-equipped powertrains by integrating the I-Shift AMT with a new, more efficient one-box aftertreatment system, achieving a weight reduction of approximately 17 pounds.
Segmentations:
By Speed
- Four-Speed
- Five-Speed
- Six-Speed
- Above Six-Speed
By Vehicle Type
- Passenger Vehicles
- Light Commercial Vehicles
- Heavy Commercial Vehicles
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia Pacific Dominating with Strong Vehicle Production and Affordability Focus
Asia Pacific accounts for 47% of the Automated Manual Transmission (AMT) Market, making it the leading regional contributor. The region continues to expand rapidly, supported by strong automotive production bases in India, China, and Japan. The market is driven by growing urban populations, rising demand for affordable mobility, and increasing adoption in compact and mid-sized vehicles. It benefits from supportive government policies encouraging fuel-efficient technologies and compliance with emission standards. The presence of leading automakers and suppliers further enhances the regional value chain, positioning Asia Pacific as the fastest-growing hub for AMT solutions.
Europe Benefiting from Advanced Automotive Infrastructure and Sustainability Goals
Europe holds 28% share of the Automated Manual Transmission (AMT) Market, reflecting its advanced automotive infrastructure and stringent regulatory environment. The region emphasizes sustainable transportation and energy efficiency, which drives the integration of AMT systems in both passenger and commercial vehicles. It supports emission reduction targets while offering consumers a balance between performance and affordability. The market is reinforced by innovation in lightweight materials and advanced electronics that enhance AMT functionality. Strong research and development activities combined with sustainability commitments continue to shape Europe’s role in the global AMT landscape.
North America and Emerging Markets Offering Steady Growth Potential
North America represents 17% of the Automated Manual Transmission (AMT) Market, supported by steady consumer demand for advanced vehicle technologies. The region shows consistent adoption in passenger cars and growing application in light commercial vehicles and fleet operations. It is particularly valued in logistics and urban transport segments where efficiency and reduced driver fatigue provide clear benefits. Latin America and the Middle East contribute a combined 8% share, reflecting emerging adoption driven by urban mobility requirements and regulatory shifts. These regions are expected to record steady growth as consumer awareness of AMT benefits strengthens.
Key Player Analysis:
- FCA US LLC
- AB Volvo
- WABCO
- Aisin World Corp. of America
- Detroit Diesel Corporation
- ZF Friedrichshafen AG
- Allison Transmission Inc.
- Shaanxi Fast Gear Co. Ltd.
- MACK TRUCKS
- Eaton
Competitive Analysis:
The Automated Manual Transmission (AMT) Market is characterized by moderate competition, with global and regional players focusing on cost efficiency, fuel savings, and technological refinement. Leading automotive manufacturers and transmission system suppliers are investing in advanced electronic control units and software upgrades to improve gear-shift precision and driving comfort. It is witnessing rising collaboration between OEMs and technology providers to expand applications across passenger, commercial, electric, and hybrid vehicles. Key players differentiate through product affordability, durability, and integration with eco-friendly vehicle platforms to address regulatory and consumer demands. It is also shaped by competition from alternative technologies such as CVT and DCT, which offer smoother performance and challenge AMT adoption in premium segments. Companies that successfully combine innovation with cost-effectiveness are expected to strengthen their market position and capture emerging opportunities across Asia Pacific, Europe, and other growth-oriented regions.
Recent Developments:
- In June 2025, Volvo Construction Equipment (Volvo CE) reached an agreement with Lantmännen to acquire the business operations of Swecon in Sweden, Germany, and the Baltics.
- In May 2025, Bilia agreed to acquire BRK Lastvagnar Holding AB, a company that handles sales and services for Volvo Trucks in central Sweden.
- In March 2025, ZF announced it is progressing with its strategic realignment, expecting group sales to exceed €40 billion in 2025 after generating €41.4 billion in the previous year.
Market Concentration & Characteristics:
The Automated Manual Transmission (AMT) Market demonstrates a moderately concentrated structure, with a mix of global automotive leaders and regional manufacturers competing for market share. It is influenced by strong demand in emerging economies, where affordability and fuel efficiency remain critical buying factors. Leading companies focus on integrating advanced electronics, lightweight materials, and software-driven controls to enhance performance and compliance with emission standards. The market is characterized by high penetration in compact and mid-sized vehicles, with growing applications in electric and hybrid platforms. It reflects a balance between cost competitiveness and innovation, with manufacturers emphasizing partnerships and localized production to strengthen their presence across diverse regions.
Report Coverage:
The research report offers an in-depth analysis based on Speed, Vehicle Type and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Automated Manual Transmission (AMT) Market will continue to expand as consumer demand for affordable automation in passenger and commercial vehicles strengthens.
- It will gain traction in emerging economies, where cost-conscious buyers value fuel efficiency and driving comfort over premium transmission alternatives.
- The market will benefit from technological advancements in electronic control units and software, enhancing gear-shift precision and reliability.
- It will experience wider integration into electric and hybrid platforms, supporting the global shift toward sustainable and efficient mobility.
- The adoption of lightweight materials and eco-friendly components will shape product development, aligning AMT systems with environmental regulations.
- It will face ongoing competition from CVT and DCT technologies, pushing manufacturers to improve AMT refinement and responsiveness.
- The market will see higher adoption in fleet and logistics operations due to its contribution to fuel savings and reduced driver fatigue.
- It will attract investments in research and development aimed at improving durability and lowering long-term maintenance costs.
- The growing emphasis on connected vehicles and smart mobility will create opportunities for AMT systems integrated with digital platforms.
- It will maintain steady growth globally, with Asia Pacific leading, while Europe, North America, and emerging markets contribute to balanced expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Automated Manual Transmission (AMT), and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Automated Manual Transmission (AMT) market projected to grow between 2024 and 2032
What are the primary factors fueling the growth of the Automated Manual Transmission (AMT) market?
Who are the major players in the Automated Manual Transmission Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Automated Manual Transmission Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Automated Manual Transmission Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4524.4 million → 2032: USD 7103.1 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Automated Manual Transmission Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Automated Manual Transmission Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Automated Manual Transmission Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Automated Manual Transmission Market Drivers
- 3.3 Automated Manual Transmission Market Restraints & Challenges
- 3.4 Automated Manual Transmission Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Automated Manual Transmission Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Automated Manual Transmission Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Automated Manual Transmission category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Automated Manual Transmission Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Automated Manual Transmission Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Automated Manual Transmission market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Automated Manual Transmission Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Automated Manual Transmission Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Automated Manual Transmission Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Automated Manual Transmission (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Automated Manual Transmission Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Automated Manual Transmission Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Automated Manual Transmission Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Automated Manual Transmission Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Automated Manual Transmission Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Automated Manual Transmission Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Automated Manual Transmission Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Automated Manual Transmission Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Automated Manual Transmission Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
