
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Balloon Catheter Market Size 2024 | USD 3068 Million |
| Balloon Catheter Market, CAGR | 9.13% |
| Balloon Catheter Market Size 2032 | USD 6171.75 Million |
Market Overview:
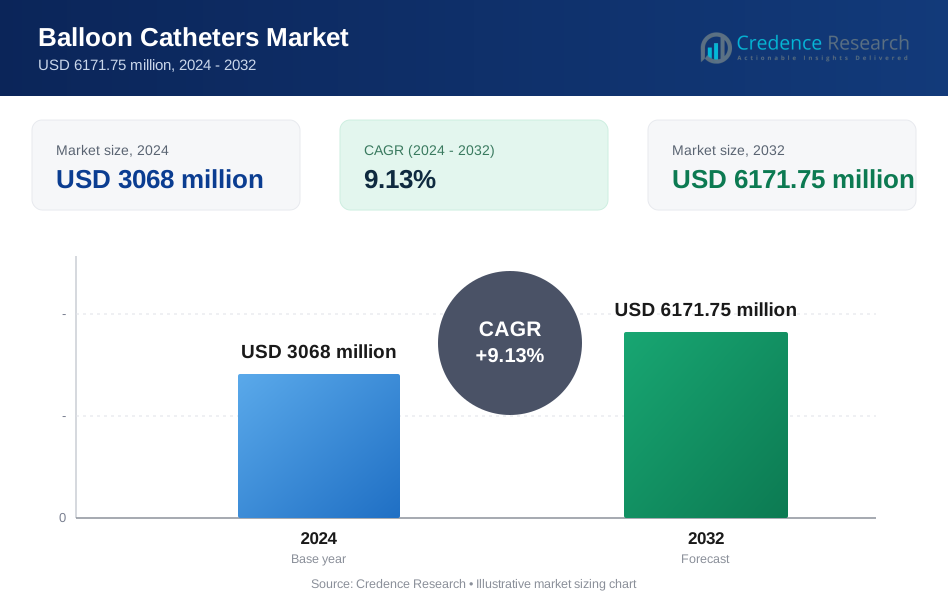
Balloon Catheter Market size was valued at USD 3068 million in 2024 and is anticipated to reach USD 6171.75 million by 2032, at a CAGR of 9.13% during the forecast period (2024-2032).
Several key drivers are contributing to the growth of the balloon catheter market. The rising incidence of cardiovascular diseases, driven by lifestyle changes and an aging population, has led to a higher demand for balloon catheter-based procedures. The increased focus on early detection and prevention of heart-related ailments is also driving demand for these devices. Furthermore, advancements in catheter technology, such as the development of drug-eluting balloon catheters, are enhancing the effectiveness of treatments and boosting their adoption. These innovations are offering improved clinical outcomes and reducing the risk of restenosis. The increasing preference for minimally invasive surgeries, which reduce recovery times and complications, is another critical factor accelerating market growth. Additionally, the growing number of ambulatory surgical centers (ASCs) and the increasing acceptance of outpatient procedures are expanding the use of balloon catheters, making procedures more accessible and cost-effective.
Regionally, North America dominates the balloon catheter market, accounting for a significant share due to the high prevalence of cardiovascular diseases, advanced healthcare infrastructure, and high healthcare spending in the region. The region also benefits from strong reimbursement policies and technological advancements, which further fuel market growth. Europe follows closely, driven by similar factors such as increasing healthcare awareness and the growing elderly population. The rise in private healthcare spending and the adoption of state-of-the-art medical technologies are also propelling market demand. The Asia Pacific region is expected to experience the highest growth during the forecast period, fueled by the improving healthcare infrastructure, increasing medical tourism, and rising awareness regarding advanced medical technologies in emerging economies like India and China. The expansion of healthcare access in rural areas and government initiatives promoting health innovations further enhance the region’s growth prospects.
Market Insights:
- The Balloon Catheter Market is projected to grow from USD 3,068 million in 2024 to USD 6,171.75 million by 2032, at a CAGR of 9.13% during the forecast period.
- The rising incidence of cardiovascular diseases, driven by aging and lifestyle factors, is increasing the demand for balloon catheter-based procedures.
- Technological advancements like drug-eluting balloon catheters are improving treatment effectiveness and patient outcomes, driving market adoption.
- The growing preference for minimally invasive surgeries is boosting the demand for balloon catheters across various medical fields.
- Expanding healthcare infrastructure and medical tourism in emerging markets, especially in Asia Pacific, are creating growth opportunities.
- High development costs for advanced balloon catheters are creating affordability challenges, particularly in emerging markets.
- North America holds a 40% market share, Europe follows with 30%, and Asia Pacific is expected to experience the highest growth, with a 20% market share.
Market Drivers:
Rising Incidence of Cardiovascular Diseases
The Balloon Catheter Market is experiencing robust growth due to the increasing prevalence of cardiovascular diseases (CVDs), particularly coronary artery diseases, which are often treated using balloon catheter-based procedures. An aging population and lifestyle factors such as poor diet, lack of physical activity, and stress contribute to a higher risk of CVDs. This trend has led to a higher demand for minimally invasive solutions like balloon angioplasty, which can restore blood flow without the need for open-heart surgery. Healthcare providers are increasingly adopting balloon catheters to meet the growing need for effective cardiovascular interventions.
Advancements in Balloon Catheter Technology
Technological innovations have been a significant driver in the Balloon Catheter Market. Developments like drug-eluting balloon catheters have improved the effectiveness of treatments, reducing restenosis rates and improving long-term patient outcomes. These advancements are making balloon catheters more effective in treating complex conditions, such as multi-vessel coronary disease. With continuous progress in materials and design, balloon catheters are becoming more reliable, durable, and customizable to meet the unique needs of patients. These technological improvements are expanding the adoption of balloon catheters globally.
- For example, Medtronic's FDA-approved IN.PACT 018 PTA Balloon Catheter is designed for peripheral arterial disease, treating lesions up to 360 mm in length within vessels measuring 4–7 mm in diameter, reflecting advancements in drug delivery and structural design.
Growing Preference for Minimally Invasive Surgeries
Minimally invasive surgeries are becoming the preferred option in modern healthcare, and balloon catheter procedures align with this trend. Patients are increasingly seeking alternatives that reduce recovery time, minimize hospital stays, and lower the risk of complications. Balloon catheterization, with its ability to treat cardiovascular, urological, and neurovascular conditions through small incisions, is gaining popularity due to these advantages. This shift toward less invasive procedures is significantly boosting the demand for balloon catheters in hospitals and outpatient centers worldwide.
- For instance, a study published by the National Institutes of Health reported that 250 patients identified reduced recovery time as a key benefit of minimally invasive surgery, demonstrating a strong patient-driven demand for such procedures.
Expanding Healthcare Infrastructure and Medical Tourism in Emerging Markets
The rapid development of healthcare infrastructure in emerging economies, particularly in the Asia Pacific region, is driving the growth of the Balloon Catheter Market. Increased investment in hospitals, medical centers, and diagnostic facilities is expanding the reach of advanced medical treatments. Furthermore, the rise in medical tourism, especially for cardiac procedures, is pushing the demand for balloon catheterization in these regions. With the growing availability of high-quality healthcare services at lower costs, patients from developed countries are also opting for balloon catheter treatments abroad.
Market Trends:
Technological Advancements Driving Market Innovation
The Balloon Catheter Market is witnessing a surge in technological advancements that are improving the efficiency and outcomes of catheter-based procedures. One of the most notable trends is the development of drug-eluting balloon catheters, which release therapeutic drugs during the procedure to reduce the risk of restenosis and enhance long-term effectiveness. Innovations in balloon catheter materials, such as bioresorbable polymers, are improving the performance of devices by reducing complications and enhancing compatibility with vascular tissues. These advancements are not only improving patient outcomes but also making balloon catheterization procedures safer and more accessible. The continuous push for innovation is driving the market forward, particularly in regions with high demand for advanced medical technologies.
- For instance, the SCAAR registry in Sweden reported outcomes for 1,129 patients treated with paclitaxel-eluting balloons, demonstrating improved results for devices using a contrast agent as a drug carrier compared to those without.
Shift Towards Minimally Invasive Procedures and Outpatient Settings
Another significant trend in the Balloon Catheter Market is the increasing preference for minimally invasive procedures, particularly in outpatient settings. Balloon catheterization is becoming the go-to solution for treating a wide range of conditions due to its ability to minimize surgical risks and reduce recovery time. The growing emphasis on patient comfort and faster recovery is leading healthcare providers to adopt balloon catheter procedures more widely. Furthermore, the rise in ambulatory surgical centers (ASCs) and outpatient clinics is creating new opportunities for the adoption of balloon catheters, as these facilities are optimized for procedures that require shorter recovery periods and less intensive care. This trend is expanding the market by making treatments more accessible to a broader patient base while reducing healthcare costs.
- For instance, the systematic review by Alfirevic et al. (2014) on outpatient cervical ripening with balloon catheters included 8,292 women across 26 studies and reported that outpatient procedures reduced time in labor and delivery units by an average of 7.24 hours compared to inpatient procedures.
Market Challenges Analysis:
High Cost and Affordability Issues
One of the major challenges facing the Balloon Catheter Market is the high cost of advanced catheter technologies. The development and manufacturing of drug-eluting and specialized balloon catheters require significant investment in research and development, driving up the overall cost of these devices. This can create affordability issues, particularly in emerging markets where healthcare budgets are more limited. Hospitals and clinics in these regions may be hesitant to adopt high-cost technologies, limiting the widespread adoption of balloon catheter procedures. The challenge of balancing innovation with cost-effectiveness remains a key obstacle for market growth.
- For instance, Viant transferred the manufacturing of a balloon catheter to Costa Rica and successfully achieved its cost savings target while maintaining the highest product quality standards, demonstrating that strategic manufacturing relocation can improve affordability for healthcare providers.
Regulatory Hurdles and Market Entry Barriers
The Balloon Catheter Market is also faced with regulatory hurdles that can slow the approval process for new products and technologies. Stringent regulations set by agencies like the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) often result in lengthy approval times, delaying market entry for innovative balloon catheter products. These regulatory barriers can hinder companies from quickly responding to market demands and technological advancements, limiting the competitive edge of some players. Navigating these regulations requires significant resources and expertise, creating additional challenges for companies seeking to expand their market presence.
Market Opportunities:
Growth in Minimally Invasive Surgery Adoption
The Balloon Catheter Market presents significant opportunities with the growing adoption of minimally invasive surgeries. As healthcare providers shift toward less invasive treatment options, balloon catheters offer an effective solution for procedures such as angioplasty, urological, and neurovascular treatments. This trend is driven by benefits like reduced recovery times, smaller incisions, and fewer complications. Hospitals and outpatient centers increasingly prefer these procedures, expanding the demand for balloon catheters. The rise in healthcare awareness and patient preference for quicker, less invasive treatments creates a strong growth opportunity for market players.
Expansion in Developing Regions
Developing regions, particularly in Asia Pacific and Latin America, offer untapped growth potential for the Balloon Catheter Market. These areas are experiencing rapid advancements in healthcare infrastructure, improving access to advanced medical treatments. As the prevalence of chronic conditions like cardiovascular diseases rises, the demand for balloon catheter procedures will grow. Healthcare providers in these regions are actively seeking cost-effective and high-quality catheter solutions. Companies that focus on providing affordable, region-specific products can leverage this expanding market, capturing a larger share of the growing demand for minimally invasive procedures.
Market Segmentation Analysis:
By Product
The Balloon Catheter Market is segmented by product type, including angioplasty balloon catheters, drug-eluting balloon catheters, and specialty balloon catheters. Angioplasty balloon catheters hold the largest share, as they are extensively used in cardiovascular procedures, particularly for coronary artery diseases. Drug-eluting balloon catheters are gaining traction due to their ability to release drugs that reduce restenosis and improve long-term patient outcomes. Specialty balloon catheters, such as those used in urological and neurovascular procedures, are also contributing to market growth, driven by advancements in medical technology.
- For instance, according to Eurostat, a total of 1,100,000 transluminal coronary angioplasty procedures using balloon catheters were performed across 25 EU countries in 2021.
By Indication
The Balloon Catheter Market is also segmented by indication, with cardiovascular diseases taking the largest share. Balloon catheters are widely used in angioplasty and stent placement for coronary artery diseases. Other significant indications include peripheral artery diseases, urological disorders, and neurovascular treatments. The demand for balloon catheters in these segments is rising as healthcare systems increasingly adopt minimally invasive techniques for various conditions, enhancing both procedure efficiency and patient recovery times.
- For instance, the BioPath paclitaxel-coated balloon catheter successfully treated 24 peripheral artery disease lesions in a pilot study, achieving 100% angiographic success without requiring additional interventions.
By End-User
The Balloon Catheter Market is segmented by end-user into hospitals, ambulatory surgical centers (ASCs), and specialty clinics. Hospitals dominate the market, due to the high volume of procedures performed and their capacity for advanced treatments. ASCs are emerging as key players, driven by the increasing trend of outpatient surgeries and minimally invasive procedures. Specialty clinics are also expanding their share, particularly for specific indications like urological or neurovascular conditions, offering specialized services to a growing patient base.
Segmentations:
By Product
- Angioplasty Balloon Catheters
- Drug-Eluting Balloon Catheters
- Specialty Balloon Catheters
By Indication
- Cardiovascular Diseases
- Peripheral Artery Diseases
- Urological Disorders
- Neurovascular Treatments
By End-User
- Hospitals
- Ambulatory Surgical Centers (ASCs)
- Specialty Clinics
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America - Leading Market with Strong Healthcare Infrastructure
North America holds the largest share of the Balloon Catheter Market, contributing 40% of the global market value. This is attributed to the region's advanced healthcare infrastructure, high prevalence of cardiovascular diseases, and widespread adoption of minimally invasive procedures. The United States plays a central role in driving market growth due to its strong focus on innovation, research, and development in medical technologies. The increasing elderly population and heightened awareness about cardiovascular health further drive demand for balloon catheter procedures in this region, ensuring North America's dominance.
Europe - Steady Growth with Aging Population and Regulatory Support
Europe commands a significant share of the Balloon Catheter Market, contributing 30% to the global market. This growth is driven by the region's aging population, strong regulatory frameworks, and widespread access to advanced medical treatments. Countries like Germany, France, and the UK are key contributors, benefiting from high healthcare spending and a growing preference for minimally invasive procedures. The European focus on preventive care and effective healthcare reforms is expected to further boost the market, solidifying its position as one of the top regions for balloon catheter adoption.
Asia Pacific - Rapid Growth with Expanding Healthcare Access
The Asia Pacific region holds 20% of the global Balloon Catheter Market share and is projected to experience the highest growth rate. This growth is fueled by expanding healthcare infrastructure in countries such as China, India, and Japan. The rise in medical tourism, increasing awareness of chronic diseases like cardiovascular conditions, and greater access to healthcare are all contributing factors to the region's growth. With a rapidly growing middle class and a rising demand for affordable healthcare solutions, the region is poised to see continued adoption of balloon catheter technologies in the coming years.
Key Player Analysis:
- MicroPort Scientific Corporation
- Biotronik SE & Co. KG
- Medtronic
- Braun Melsungen AG
- BD (Becton, Dickinson and Company)
- Boston Scientific
- Teleflex Medical OEM
- Meril Life Sciences Pvt. Ltd.
- Abbott Laboratories
- Terumo Corporation
- Cook Medical
- Cordis (a Cardinal Health company)
Competitive Analysis:
The Balloon Catheter Market is competitive, with major players like Medtronic, Boston Scientific, and Abbott Laboratories leading through continuous innovation and advanced product offerings, such as drug-eluting balloon catheters. These companies focus on research and development to enhance treatment outcomes and cater to various medical specialties, including cardiovascular and neurovascular procedures. Smaller companies like Cook Medical and Teleflex Medical contribute by offering cost-effective solutions and specialized products. Strategic collaborations, mergers, and acquisitions are common as companies aim to expand their presence, particularly in emerging markets such as the Asia Pacific region, where increasing healthcare infrastructure and medical tourism drive demand for advanced catheter technologies.
Recent Developments:
- In February 2025, Medtronic Neurovascular announced a partnership with Brainomix to integrate AI-powered stroke imaging into clinical practice across Western Europe.
- In May 2025, Medtronic announced plans to spin off its diabetes business within 18 months, creating a new, stand-alone diabetes technology company.
- In March 2025, Boston Scientific announced a definitive agreement to acquire SoniVie Ltd., a developer of the TIVUS™ Intravascular Ultrasound System, for up to $540 million. The transaction is expected to close in the first half of 2025
- In April 2025, Cook Medical announced a collaboration with Mendaera™ Inc. to develop advanced solutions for needle-based interventions in urological procedures, integrating Cook’s EchoTip technology with Mendaera’s handheld robotics.
Market Concentration & Characteristics:
The Balloon Catheter Market exhibits moderate concentration, with a few key players, such as Medtronic, Boston Scientific, and Abbott Laboratories, holding significant market share. These companies dominate through technological advancements and a broad range of product offerings across various medical specialties. Smaller players, including Cook Medical and Teleflex Medical, contribute with specialized and cost-effective solutions, ensuring a competitive landscape. The market is characterized by continuous innovation, with companies focusing on the development of drug-eluting balloon catheters and other advanced technologies. High research and development investments, strategic partnerships, and geographic expansion are key traits of the market, as companies seek to cater to the growing demand for minimally invasive procedures. With expanding healthcare infrastructure in emerging markets, especially in Asia Pacific, the market is evolving to meet new regional demands.
Report Coverage:
The research report offers an in-depth analysis based on Product, Indication, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Balloon Catheter Market is expected to experience significant growth, driven by the increasing prevalence of cardiovascular diseases and the rising demand for minimally invasive procedures.
- Technological advancements, such as the development of drug-eluting balloon catheters and improved balloon materials, are enhancing treatment outcomes and expanding the range of treatable conditions.
- The growing preference for outpatient procedures and the expansion of ambulatory surgical centers are contributing to the increased adoption of balloon catheter-based interventions.
- Emerging markets, particularly in the Asia Pacific region, are witnessing rapid growth due to improving healthcare infrastructure and rising patient awareness.
- The integration of artificial intelligence and robotics in endovascular procedures is poised to enhance the precision and efficiency of balloon catheter applications.
- Regulatory advancements and favorable reimbursement policies in developed regions are facilitating the widespread adoption of advanced balloon catheter technologies.
- Collaborations and partnerships among key industry players are accelerating innovation and expanding market reach.
- The increasing geriatric population is driving the demand for balloon catheter procedures, as older adults are more susceptible to cardiovascular diseases.
- Rising healthcare expenditures and government initiatives in emerging economies are improving access to advanced medical devices, including balloon catheters.
- Ongoing research and development efforts are focused on enhancing the safety, efficacy, and cost-effectiveness of balloon catheter technologies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Balloon Catheter Market?
What factors are driving the growth of the Balloon Catheter Market?
Which region is leading in the Balloon Catheter Market?
Which region is expected to grow the fastest in the Balloon Catheter Market?
How do advancements in balloon catheter technology affect the market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Balloon Catheters Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Balloon Catheters Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3068 million → 2032: USD 6171.75 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Balloon Catheters Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Balloon Catheters Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Balloon Catheters Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Balloon Catheters Market Drivers
- 3.3 Balloon Catheters Market Restraints & Challenges
- 3.4 Balloon Catheters Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Balloon Catheters Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Balloon Catheters Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Balloon Catheters category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Balloon Catheters Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Balloon Catheters Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Balloon Catheters market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Balloon Catheters Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Balloon Catheters Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Balloon Catheters Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Balloon Catheters (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Balloon Catheters Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Balloon Catheters Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Balloon Catheters Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Balloon Catheters Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Balloon Catheters Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Balloon Catheters Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Balloon Catheters Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Balloon Catheters Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Balloon Catheters Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
