
Battery Backup Market
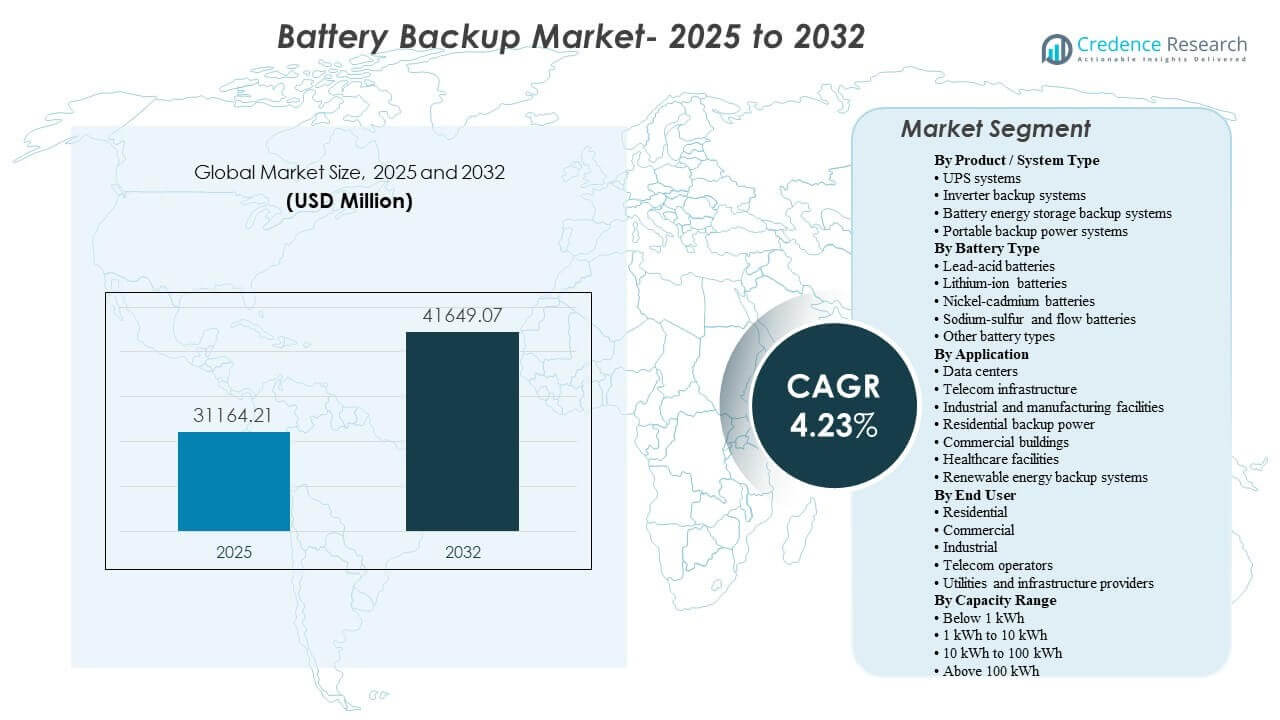
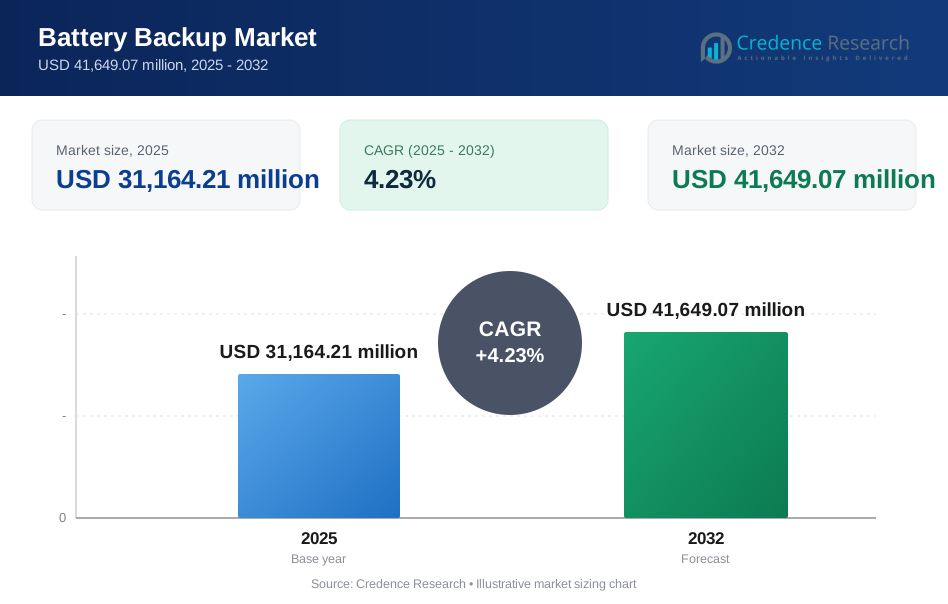
The global Battery Backup Market size was estimated at USD 31,164.21 million in 2025 and is expected to reach USD 41,649.07 million by 2032, growing at a CAGR of 4.23% from 2025 to 2032. Demand is primarily supported by rising uptime requirements across digital infrastructure and critical facilities, where power-quality protection and short-to-medium duration resilience remain operational priorities. Growth momentum is additionally supported by expanding deployments across Asia Pacific and steady replacement cycles in mature commercial and industrial installations.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Battery Backup Market Size 2025 | USD 31,164.21 million |
| Battery Backup Market, CAGR | 4.23% |
| Battery Backup Market Size 2032 | USD 41,649.07 million |
Key Market Trends & Insights
- The Battery Backup Market is projected to expand from USD 31,164.21 million in 2025 to USD 41,649.07 million by 2032, reflecting a 4.23% CAGR over 2025–2032.
- Asia Pacific accounted for 34% share in 2025, reflecting the region’s scale in infrastructure expansion and backup adoption across industrial and residential settings.
- North America represented 29% share in 2025, supported by high penetration of backup solutions in commercial facilities and mission-critical environments.
- Data centers represented 35% share (2023) within UPS battery backup power demand, reflecting the continued dominance of critical-load applications in backup investments.
- Lithium-ion accounted for 87.6% share (2025) in portable power station demand, indicating accelerating preference for higher energy density and lifecycle characteristics in compact backup formats.
Segment Analysis
Battery backup demand is shaped by a mix of mission-critical uptime needs and distributed resilience requirements. Data centers and telecom sites continue to prioritize low-transfer-time backup, stable power conditioning, and monitoring integration, supporting adoption of modern UPS platforms and higher-performance battery configurations. In parallel, residential and small commercial demand remains anchored in practical runtimes, ease of installation, and cost-performance tradeoffs, which sustains inverter-based and compact storage-backed solutions in many markets.
Across battery chemistries, lithium-ion adoption strengthens in use cases where lifecycle value, footprint reduction, and faster response are prioritized, especially in higher-value commercial and infrastructure environments. Lead-acid continues to maintain relevance in established UPS ecosystems where familiarity, serviceability, and replacement networks remain strong. Longer-duration technologies such as flow systems remain more aligned to stationary storage-backed backup requirements rather than compact continuity applications.
By Product / System Type Insights
UPS systems remain central to the market due to their role in providing seamless continuity and power conditioning for sensitive loads, and they accounted for the largest share at 41% in 2025. Data center and telecom applications favor architectures that support scalability, redundancy, and remote monitoring to reduce operational risk. Inverter backup systems retain relevance for residential and small commercial users where cost sensitivity and straightforward deployment guide purchasing. Battery energy storage backup systems gain traction where resilience is paired with energy management goals, particularly in facilities that value flexibility beyond short ride-through.
By Battery Type Insights
Lithium-ion batteries continue to expand their role in backup deployments where lifecycle economics and footprint constraints influence procurement decisions, and they held the largest share at 50% in 2025. The preference is reinforced in applications that require frequent cycling, compact form factors, or simplified maintenance practices. Lead-acid batteries remain widely deployed in conventional UPS environments due to established supply chains and service familiarity. Nickel-cadmium batteries persist in selected industrial contexts where robustness under harsh operating conditions matters, while sodium-sulfur and flow batteries are more often aligned with stationary, longer-duration backup needs.
By Application Insights
Data centers are a core application segment because service continuity and downtime avoidance are tightly linked to business risk and compliance expectations. Telecom infrastructure relies on backup to maintain network availability across distributed sites and edge deployments, driving demand for robust solutions and remote monitoring. Industrial and manufacturing facilities deploy backup to protect automation systems and reduce disruption from power events that can affect yield and safety. Residential backup power adoption is shaped by outage preparedness and the growing linkage between home energy storage and distributed generation. Healthcare facilities prioritize continuity for essential systems and critical equipment, supporting stable demand for reliable backup configurations.
By End User Insights
Residential buyers typically prioritize right-sized capacity, ease of use, and reliable operation during outages, supporting steady uptake of inverter and compact storage solutions. Commercial users focus on protecting IT loads, security systems, and building services where short disruptions can create operational and reputational costs. Industrial end users emphasize durability, serviceability, and integration with site electrical infrastructure to ensure predictable performance under variable conditions. Telecom operators require resilient backup across many locations and often value standardized platforms that simplify fleet management. Utilities and infrastructure providers increasingly consider storage-backed backup configurations where resilience planning intersects with grid-support and continuity requirements.
By Capacity Range Insights
Below 1 kWh solutions are commonly adopted for targeted loads such as networking equipment, lighting, and essential electronics where portability and affordability drive selection. The 1 kWh to 10 kWh range remains a primary band for residential backup needs because it aligns with typical household critical-load coverage and practical system sizing. The 10 kWh to 100 kWh range supports expanded resilience for small commercial facilities and larger homes, especially where backup is paired with distributed generation. Above 100 kWh systems are typically aligned with commercial, industrial, and infrastructure settings that require higher runtime capacity and system-level integration.
Battery Backup Market Drivers
Rising critical-load uptime requirements across digital infrastructure
The expansion of digital services increases the operational cost of downtime, reinforcing investment in backup power continuity. Data centers require stable power quality and immediate ride-through capability to protect IT loads. Telecom networks depend on distributed backup to maintain service availability during power interruptions. Monitoring and manageability features further strengthen replacement demand as operators seek predictable performance and remote diagnostics.
Increasing adoption of distributed backup in residential and small commercial settings
Outage preparedness continues to influence household and small business decisions regarding backup power solutions. Residential buyers often seek practical runtimes for essential appliances and connectivity loads. Inverter-based and compact storage-backed systems provide accessible pathways for backup adoption in many markets. Growth is also supported by improving product usability and safer, more integrated deployment options.
Transition toward higher-performance battery configurations and lower total cost of ownership
Battery choice increasingly affects lifecycle cost, footprint, and maintenance requirements in backup deployments. Lithium-ion adoption grows in applications where longer service life and reduced maintenance align with operational priorities. Space-constrained installations also favor solutions that deliver higher energy density and simplified cabinet layouts. This transition supports both new deployments and retrofit upgrades within installed UPS and backup ecosystems.
- For instance, Eaton states that its 9PX lithium-ion UPS delivers 8 to 10 years of life expectancy, recharges to up to 90% in 3 hours, provides 2 to 3 times longer battery life than lead-acid alternatives, and can deliver up to double the runtime at typical loads compared with equivalent VRLA models.
Industrial continuity and process protection requirements
Manufacturing and industrial facilities face operational risk from power disturbances that can impact automation, quality, and safety systems. Backup investments are used to protect sensitive controls, reduce downtime-related losses, and maintain safe operations. Industrial users also value robust designs that withstand site conditions and support serviceability. The breadth of industrial applications supports diverse system sizing and chemistry selection across the market.
- For instance, ABB’s PCS100 UPS-I is positioned for industrial protection in ratings from 150 kVA to 3000 kVA, and ABB reports installed systems totaling hundreds of MVA at manufacturers including Samsung and other LCD plants, while ABB’s UPS portfolio also specifies up to 96% overall efficiency and overload capability of 150% for 1 minute in critical power applications.
Battery Backup Market Challenges
Battery backup deployments face cost and configuration complexity challenges that vary by use case and system size. Upfront investment, installation requirements, and the need for compatible electrical infrastructure can slow decision-making in price-sensitive segments. Maintenance and lifecycle management requirements also differ by chemistry and operating environment, which can increase ownership complexity for buyers without dedicated technical support.
- For instance, Tesla states that each Megapack is delivered fully assembled with up to 3 MWh of storage and 1.5 MW of inverter capacity, and the company says a 250 MW / 1 GWh plant can be deployed in less than three months on a three-acre footprint, which highlights how product-level engineering can directly reduce installation complexity and deployment time at utility scale.
Supply chain variability and performance standardization remain additional barriers in some regions. Battery availability, component lead times, and compliance considerations can influence project timelines and equipment choices. Buyers may also face tradeoffs among runtime, footprint, and serviceability, especially in constrained installations. These constraints increase the importance of vendor service coverage, diagnostics, and robust warranty structures.
Battery Backup Market Trends and Opportunities
The market continues to shift toward smarter, more connected backup systems with greater monitoring and control functionality. Remote diagnostics, predictive maintenance, and software integration improve operational visibility for commercial and infrastructure buyers. Modular designs and scalable architectures also support faster deployment and staged expansion for evolving critical-load needs.
- For instance, Vertiv’s Liebert EXL S1 UPS integrates Vertiv LIFE Services for remote diagnostic and preventive monitoring, supports parallel operation of up to 8 units, covers a 625–1200 kVA/kW range, and reaches up to 99% efficiency in Dynamic Online mode, which demonstrates how suppliers are combining digital oversight with scalable high-capacity backup platforms.
Another opportunity is the growth of storage-backed backup configurations that combine resilience with energy management capabilities. Systems that support flexible sizing and integration with distributed generation can address both continuity and optimization goals. This creates expansion potential in commercial buildings, industrial facilities, and selective residential applications. Product differentiation increasingly centers on lifecycle value, footprint efficiency, and integrated service ecosystems.
Regional Insights
North America
North America held 29% share in 2025, supported by strong demand from commercial facilities and mission-critical environments that prioritize uptime and power quality. Data center growth and edge expansion support continued investment in UPS systems and scalable backup configurations. Replacement demand is reinforced by lifecycle upgrades and monitoring-driven operations practices. Buyer emphasis often centers on reliability, service coverage, and compliance-aligned deployment.
Europe
Europe accounted for 22% share in 2025, driven by modernization of facility power infrastructure and continuity requirements across commercial and industrial operations. Backup demand is supported by replacement cycles and the need for predictable performance in critical environments. Energy management priorities also influence interest in storage-backed backup in selected applications. Purchasing decisions typically emphasize reliability, safety, and integration into building and IT operations.
Asia Pacific
Asia Pacific led the market with 34% share in 2025, supported by large-scale infrastructure expansion and broad adoption across industrial, telecom, and residential segments. Rapid digitalization contributes to higher backup penetration in IT, edge, and network deployments. Demand is also influenced by diversified requirements ranging from compact residential backup to higher-capacity commercial and industrial systems. Scale and variety across end users encourage a wide mix of system types and battery chemistries.
Latin America
Latin America represented 8% share in 2025, supported by backup needs in commercial facilities and telecom infrastructure where continuity is critical. Adoption is influenced by power-quality concerns and the need to protect essential loads across distributed sites. Growth opportunities emerge in commercial buildings and critical services where downtime risk is increasingly recognized. The market often values cost-effective solutions with strong serviceability and availability.
Middle East & Africa
Middle East & Africa accounted for 7% share in 2025, supported by critical infrastructure projects, expanding telecom requirements, and selective growth in data center capacity. Backup demand is reinforced by continuity needs in healthcare and essential services. Deployment patterns vary significantly by country, shaped by infrastructure investment cycles and procurement practices. Vendors with strong project execution and service coverage are typically better positioned in complex installations.
Competitive Landscape
Competition is shaped by product reliability, total cost of ownership, monitoring ecosystems, and the breadth of service and channel coverage. Suppliers differentiate through scalable UPS architectures, integrated battery cabinets, and software platforms that improve visibility and maintenance planning. Portfolio breadth across residential, commercial, industrial, and infrastructure applications strengthens positioning by enabling consistent vendor selection across multiple use cases. Partnerships and product line refresh cycles are used to address changing battery preferences and evolving buyer requirements.
Schneider Electric continues to compete through a broad portfolio that spans UPS systems and backup power solutions across residential, commercial, and critical-load environments. The company’s positioning benefits from integrated power management capabilities and a strong ecosystem for monitoring and lifecycle support. Product continuity across multiple power classes supports standardized deployment strategies for enterprise and infrastructure buyers. Service reach and established channel presence further support adoption and replacement demand.
The industry research and growth report includes detailed analyses of the competitive landscape of the market and information about key companies, including:
- Schneider Electric
- APC by Schneider Electric
- Eaton Corporation
- ABB Ltd.
- Emerson Electric Co.
- CyberPower Systems
- Tripp Lite
- Delta Greentech
- Tesla, Inc.
- LiftMaster
- Vertiv Group Corp.
- Mitsubishi Electric Corporation
- Toshiba Corporation
- Huawei Technologies Co., Ltd.
Qualitative and quantitative analysis of companies has been conducted to help clients understand the wider business environment as well as the strengths and weaknesses of key industry players. Data is qualitatively analyzed to categorize companies as pure play, category-focused, industry-focused, and diversified; it is quantitatively analyzed to categorize companies as dominant, leading, strong, tentative, and weak.
Recent Developments
- In May 2025, ABB expanded its UPS portfolio with new PowerValue models for enterprise data centers, including lithium-battery-based systems aimed at power protection and backup reliability. ABB highlighted longer runtime, lower maintenance, cost-effectiveness, and battery management system integration as key features of the new launch.
- In July 2025, Honeywell announced the acquisition of Nexceris’ Li-ion Tamer business to strengthen its battery fire detection and life-safety portfolio for lithium-ion battery applications. Honeywell said Li-ion Tamer’s off-gas detection technology helps identify thermal runaway risks early, making the acquisition relevant to battery backup, energy storage, and data center safety solutions.
- In November 2025, Trina Storage signed an MoU with Pacific Green Energy Group to deliver up to 5 GWh of battery energy storage systems between 2026 and 2028. The partnership is intended to support large-scale storage deployments that improve grid reliability and expand advanced battery-backed power infrastructure in Australia and other international markets.
- In December 2025, Farmers Electric Cooperative and Base Power launched the first residential battery program in Farmers’ Northeast Texas service area, offering members an affordable whole-home backup solution. Under the partnership, Base Power said it will deploy 20 MW of dispatchable capacity through networked residential battery systems, while Farmers uses the systems for peak shaving and energy arbitrage without affecting member bills.
Report Scope
| Report Attribute | Details |
| Market size value in 2025 | USD 31,164.21 million |
| Revenue forecast in 2032 | USD 41,649.07 million |
| Growth rate (CAGR) | 4.23% (2025–2032) |
| Base year | 2025 |
| Forecast period | 2026–2032 |
| Quantitative units | USD million |
| Segments covered | By Product / System Type, By Battery Type, By Application, By End User, By Capacity Range |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Key companies profiled | Schneider Electric; APC by Schneider Electric; Eaton Corporation; ABB Ltd.; Emerson Electric Co.; CyberPower Systems; Tripp Lite; Delta Greentech; Tesla, Inc.; LiftMaster; Vertiv Group Corp.; Mitsubishi Electric Corporation; Toshiba Corporation; Huawei Technologies Co., Ltd. |
| No. of Pages | 324 |
Segmentation
By Product / System Type
- UPS systems
- Inverter backup systems
- Battery energy storage backup systems
- Portable backup power systems
By Battery Type
- Lead-acid batteries
- Lithium-ion batteries
- Nickel-cadmium batteries
- Sodium-sulfur and flow batteries
- Other battery types
By Application
- Data centers
- Telecom infrastructure
- Industrial and manufacturing facilities
- Residential backup power Commercial buildings
- Healthcare facilities
- Renewable energy backup systems
By End User
- Residential
- Commercial
- Industrial
- Telecom operators
- Utilities and infrastructure providers
By Capacity Range
- Below 1 kWh
- 1 kWh to 10 kWh
- 10 kWh to 100 kWh
- Above 100 kWh
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the Battery Backup Market size and forecast?
What is the CAGR for the Battery Backup Market during 2025–2032?
Which application segment is the largest in the Battery Backup Market?
What factors are driving growth in the Battery Backup Market?
Which region leads the Battery Backup Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 31,164.21 million → 2032: USD 41,649.07 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2025
- 2.6.2 Forecast Period: 2025-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Battery Backup Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Battery Backup Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2025-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2025-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Battery Backup Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2025-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Battery Backup Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Battery Backup Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Battery Backup Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Battery Backup Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Battery Backup Market Outlook, 2025-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 31,164.21 million → 2032: USD 41,649.07 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Battery Backup Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Battery Backup Geographic Market Outlook, 2025-2032
- 13.1 Regional Market Size and Share, 2025
- 13.2 Regional Market Forecast, 2025-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Battery Backup Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2025-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Battery Backup Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2025
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2025-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

